


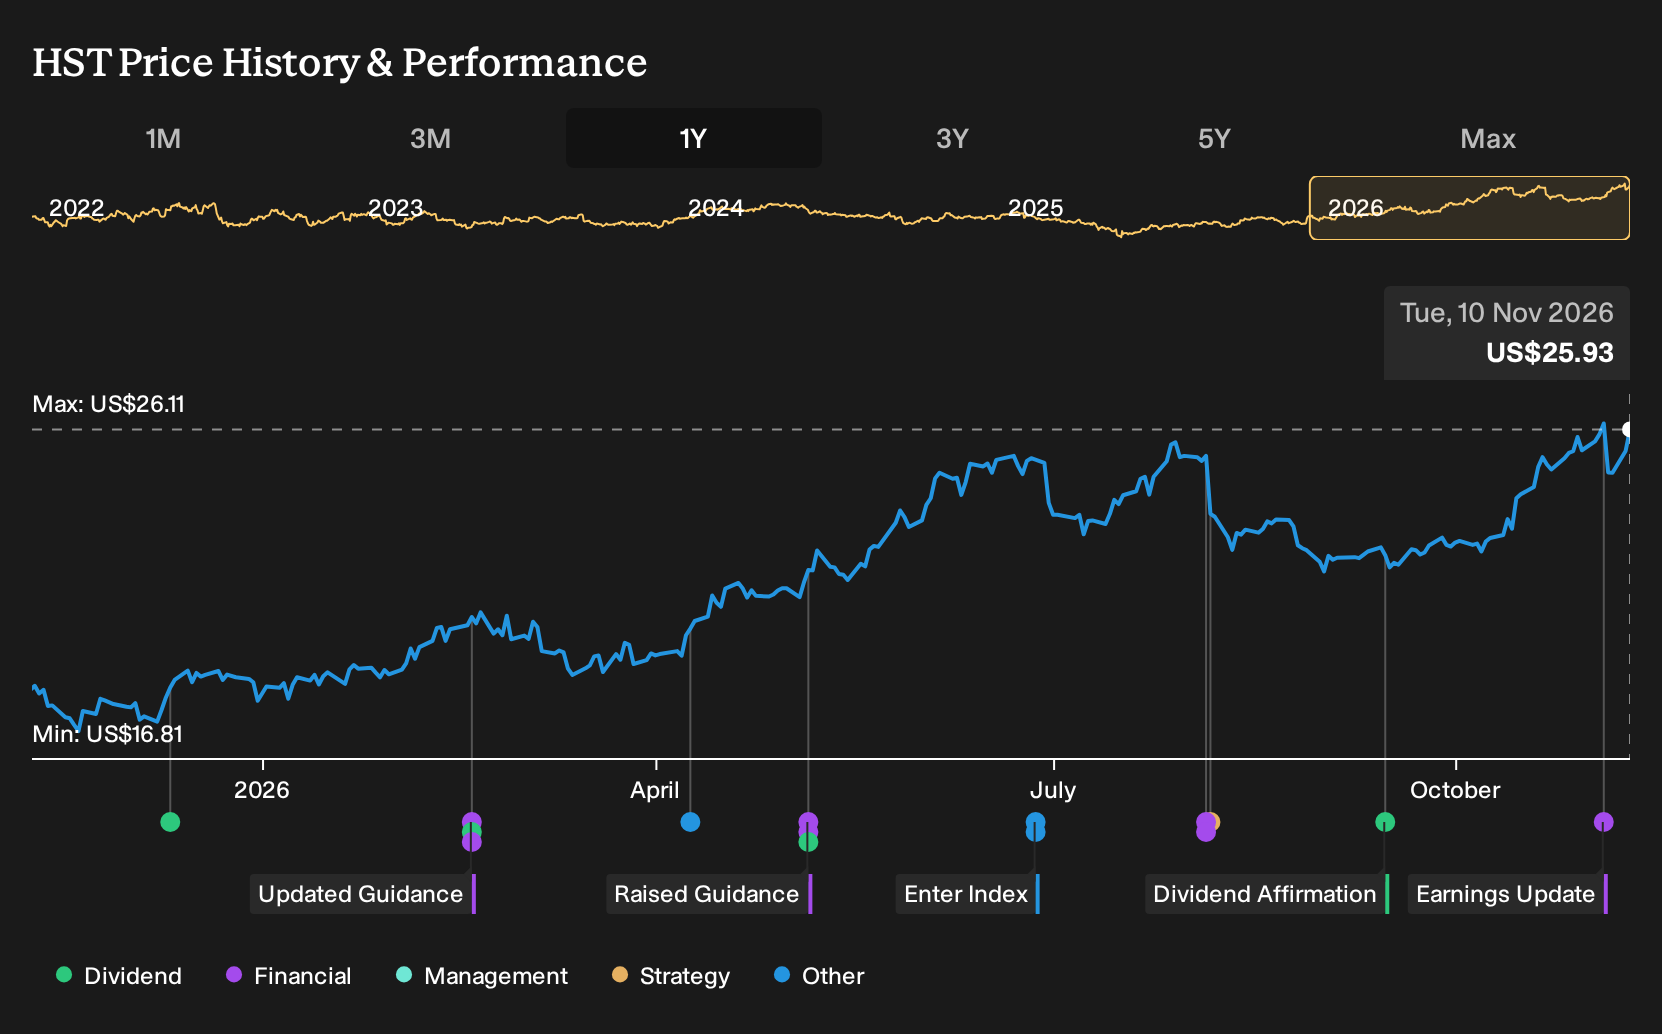
- Host Hotels & Resorts reported third quarter 2026 revenue of US$1,347 million and net income of US$70 million, while also disclosing year to date net income of US$801 million and an expansion of its portfolio with the 1 Hotel Brooklyn Bridge and a Dallas/Fort Worth property.
- The combination of modest top line growth, sharply lower quarterly earnings, and fresh luxury acquisitions highlights the tension between near term profit pressure and a longer term push into higher end and more geographically diverse assets.
- We will now assess how Host Hotels & Resorts' Brooklyn luxury acquisition fits into its existing investment narrative and risk balance.
Contrast Host Hotels & Resorts' luxury expansion with other potential opportunities by reviewing a curated 35 high quality undervalued stocks that currently combine solid cash flows with balance sheet strength.
Host Hotels & Resorts Investment Narrative Recap
For Host Hotels & Resorts, the big picture an investor needs to buy into is straightforward. You need to believe the luxury and upper upscale portfolio can keep converting leisure, group and event travel into steady cash flow, even while business transient demand faces structural pressure from hybrid work. The analyst consensus Narrative on Simply Wall St focuses on renovation-led RevPAR gains and resilient affluent travel as key supports.
The short-term swing factor now is execution on earnings quality while funding heavy capex. Third quarter net income of US$70 million on US$1,347 million of revenue points to some profit pressure, so the immediate risk is that weaker margins coincide with ongoing storm, climate and renovation disruption.
The most relevant update here is the third quarter and nine-month 2026 earnings release. Host Hotels & Resorts reported quarterly revenue of US$1,347 million and net income of US$70 million, with year-to-date revenue at US$4,632 million and net income of US$801 million. Earnings per share for the quarter were US$0.10 basic and diluted from continuing operations.
For you as a shareholder, that keeps the focus on whether future RevPAR and EBITDA contributions from upgraded and acquired luxury assets can support these earnings levels while capex and weather risks remain significant. It also frames the next few quarters as a check on the analyst Narrative that assumes relatively flat revenue, shrinking margins and declining earnings over the next three years.
Host Hotels & Resorts' current earnings are about US$1.0b, with analyst consensus pointing to US$831.3 million of earnings on roughly flat revenue by 2029. This implies a decline of about US$168.7 million from today's level and a revenue base of about US$6.4b in that forecast year.
Uncover why Host Hotels & Resorts' fair value indicates that earnings expectations are roughly in line with its current price.
Exploring Other Perspectives
For a different angle, focus on how bullish analysts treated Host Hotels & Resorts’ capex heavy plan as a potential upside catalyst. Before this latest earnings and acquisition update, the most optimistic forecasts still had earnings drifting from about US$936.0 million to US$766.5 million on revenue near US$6.6b. Those projections came with higher implied P/E multiples and a view that upgraded resorts and richer out of room spending could support a premium valuation. You now have fresh information that those models did not include, so it makes sense to compare these more upbeat scenarios with the baseline narrative and decide which assumptions feel closer to how you see the business.
Explore another Host Hotels & Resorts fair value estimate, including one that suggests up to 17% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Host Hotels & Resorts research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Host Hotels & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Host Hotels & Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Host Hotels & Resorts?
Once you have a view on Host Hotels & Resorts, it helps to line that up against a few very different watchlist candidates using the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, review a curated 35 high quality undervalued stocks that blend resilient balance sheets with strong cash generation.
- If capital preservation and smoother return profiles sit higher on your priority list, consider screening a 30 resilient stocks with low risk scores that may offer lower volatility alongside solid fundamentals.
- To broaden your opportunity set beyond widely followed large caps, scan a 20 high quality undiscovered gems that pair healthy financials with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com