


Kansas City, Missouri-based Evergy, Inc. (EVRG), generates, transmits, distributes, and sells electricity. Valued at $20.4 billion by market cap, the company generates electricity through coal, landfill gas, uranium, and natural gas and oil sources, as well as solar, wind, other renewable sources.
Shares of this utility company have outperformed the broader market over the past year. EVRG has gained 14.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, EVRG stock is up 22%, surpassing the SPX’s 9.9% rise on a YTD basis.
Zooming in further, EVRG’s outperformance is also apparent compared to State Street Utilities Select Sector SPDR ETF (XLU). The exchange-traded fund has declined 2.6% over the past year. Moreover, EVRG’s double-digit returns on a YTD basis outshine the ETF’s 2.3% gains over the same time frame.
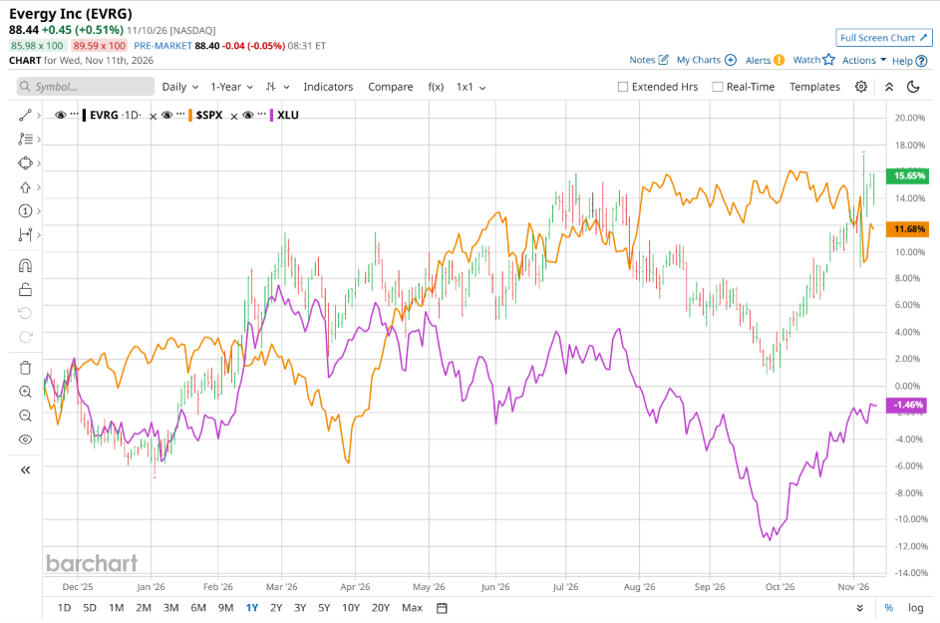
EVRG has outperformed, driven by strong operational execution, favorable weather conditions, and surging electricity demand from large commercial customers and data centers. The regulated utility has benefited from robust retail load growth, leading to consecutive quarters of better-than-expected earnings, multiple upward revisions to its full-year guidance, and an increased dividend payout. This fundamental business strength, paired with a clear multi-year capital investment strategy and a confident long-term growth outlook, has reinforced investor confidence and driven the stock higher.
On Nov. 5, EVRG shares closed up by 1.4% after reporting its Q3 results. Its adjusted EPS of $2.58 topped Wall Street expectations of $2.30. Evergy expects full-year adjusted EPS in the range of $4.35 to $4.50.
For the current fiscal year, ending in December, analysts expect EVRG’s EPS to grow 15.1% to $4.41 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Among the 15 analysts covering EVRG stock, the consensus is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, one “Moderate Buy,” and five “Holds.”
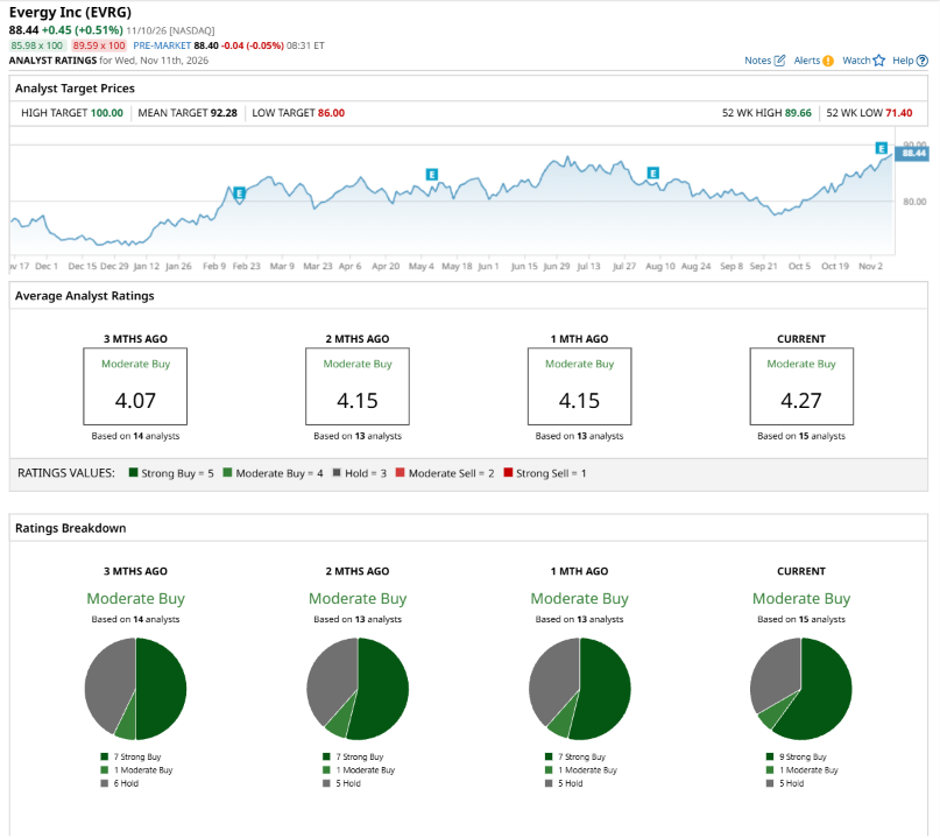
This configuration is more bullish than a month ago, with seven analysts suggesting a “Strong Buy.”
On Oct. 26, RBC Capital analyst Stephen D’Ambrisi maintained a “Buy” rating on EVRG and set a price target of $98, implying a potential upside of 10.8% from current levels.
The mean price target of $92.28 represents a 4.3% premium to EVRG’s current price levels. The Street-high price target of $100 suggests an upside potential of 13.1%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.