


New Britain, Connecticut-based Stanley Black & Decker, Inc. (SWK) is a diversified global provider of hand tools, power tools and related accessories, mechanical access and electronic security solutions, healthcare solutions, engineered fastening systems, and more. Valued at $17.3 billion by market cap, the company offers onshore and offshore pipeline construction and inspection services.
Shares of this leading manufacturer of hand and power tools have notably outperformed the broader market over the past year. SWK has gained 71.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, SWK stock is up 56.8%, surpassing the SPX’s 9.9% rise on a YTD basis.
Zooming in further, SWK’s outperformance looks more pronounced compared to the State Street Industrial Select Sector SPDR ETF (XLI). The exchange-traded fund has gained about 9.4% over the past year. Moreover, SWK’s double-digit gains on a YTD basis outshine the ETF’s 8.8% returns over the same time frame.
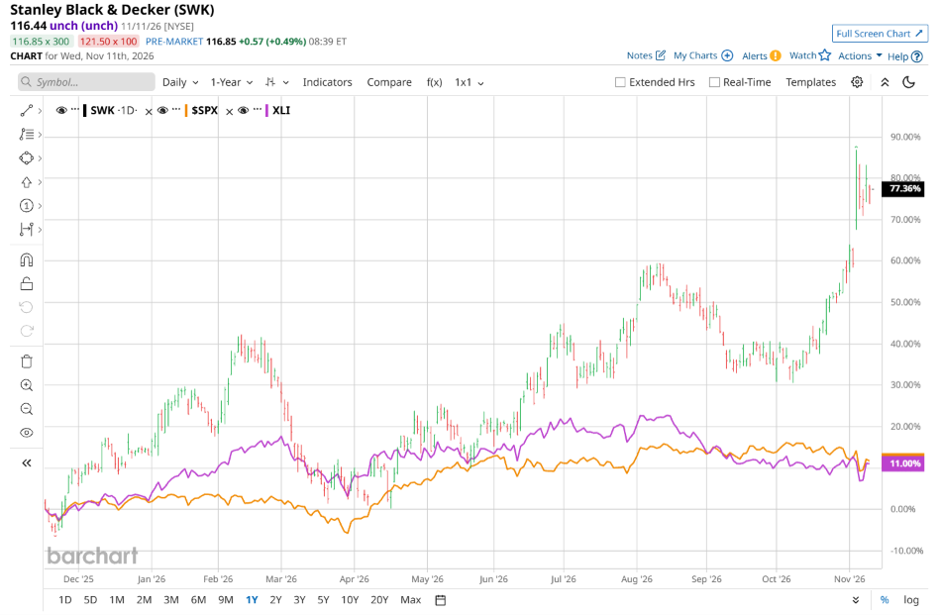
SWK delivered strong outperformance, driven by robust organic growth in core brands like DEWALT, STANLEY, and CRAFTSMAN, alongside disciplined supply chain execution and margin expansion in the Tools & Outdoor segment. Management highlighted that tariff refunds, targeted brand investments, and favorable product mix bolstered earnings, while strategic actions, such as the pending divestiture of the Excel mower business and share repurchases, further streamlined operations. Looking ahead, raised guidance reflects continued momentum from product innovation and productivity measures, though leadership noted that ongoing steel and component inflation will necessitate continued pricing and cost-control discipline.
On Nov. 4, SWK shares jumped over 13% after reporting its Q3 results. Its adjusted EPS of $2.31 beat Wall Street expectations of $1.54. The company’s revenue was $3.73 billion, beating Wall Street forecasts of $3.72 billion. SWK expects full-year adjusted EPS in the range of $5.95 to $6.25.
For the current fiscal year, ending in December, analysts expect SWK’s EPS to grow 30.8% to $6.11 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 15 analysts covering SWK stock, the consensus is a “Moderate Buy.” That’s based on four “Strong Buy” ratings, and 11 “Holds.”
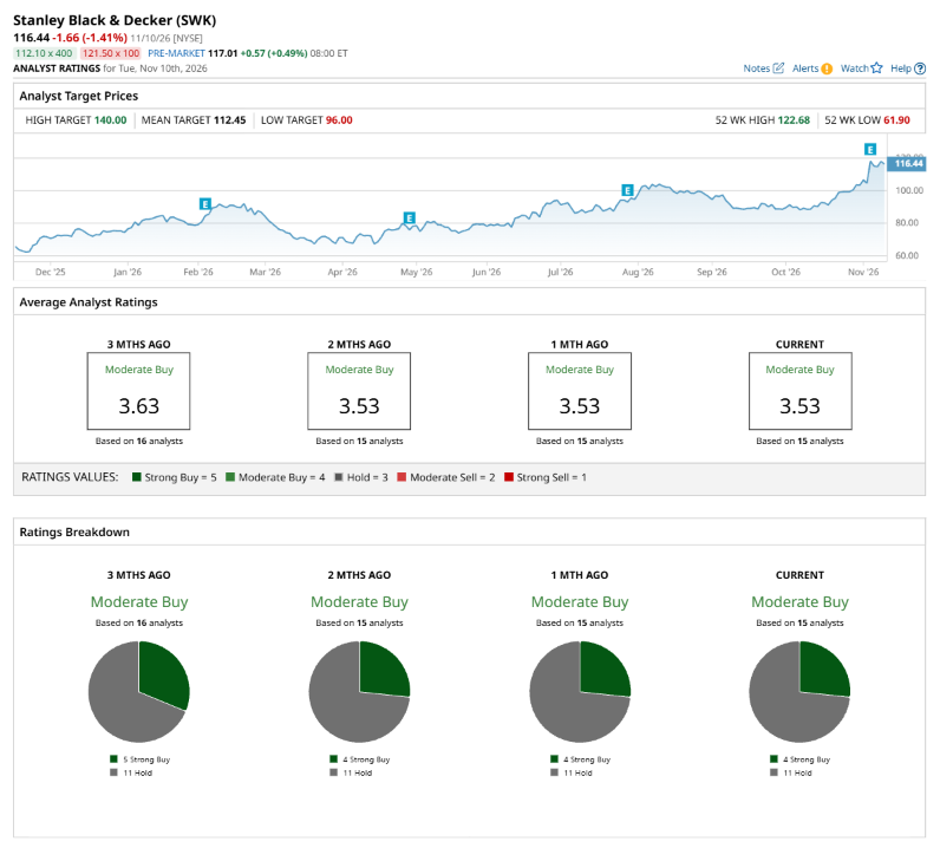
This configuration is less bullish than three months ago, with five analysts suggesting a “Strong Buy.”
On Nov. 5, Sam Reid from Wells Fargo & Company (WFC) assigned a “Hold” rating to SWK, with a price target of $115.
While SWK currently trades above its mean price target of $112.45, the Street-high price target of $140 suggests an upside potential of 20.2%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.