


Selective Insurance Group (SIGI) is drawing attention after investment income emerged as a key support for earnings, helped by higher yields, growing invested assets, and relatively stable interest rates.
At a share price of US$103.34, Selective Insurance Group has seen momentum pick up, with a 30 day share price return of 22.7% and a year to date share price gain of 23.7%. The 1 year total shareholder return of 33.4% suggests recent strength building on a longer record of more moderate gains over three and five years.
Scan beyond Selective Insurance Group and review other insurers and financials showing resilient earnings support with 30 resilient stocks with low risk scores.
Bulls point to resilient investment income and a US$5.9b market value that barely trails analyst targets. Bears worry the recent 30 day surge already prices that in. Which case does Selective Insurance Group’s valuation actually support next?
Most Popular Narrative: 1% Overvalued
Against a last close of $103.34, the analyst consensus Narrative on Simply Wall St anchors Selective Insurance Group’s fair value at $101.86 using a 7.24% discount rate. This points to a slight premium that now needs earnings execution to hold.
The main thing that has to go right is that Selective Insurance Group continues to successfully re underwrite weaker books, manage social inflation in casualty lines, and scale its E&S and Personal Lines portfolios without eroding underwriting discipline.
The current valuation implies the share price does not fully credit Selective Insurance Group for its recent double digit operating ROE, strong E&S profitability, and growing contribution from net investment income.
See why 11 investors see Selective Insurance Group as 1% overvalued.
Result: Fair Value of $101.86 (OVERVALUED)
Still, Selective Insurance Group faces pressure if casualty claim severities continue to drive reserve hits or if tighter underwriting further slows Standard Commercial Lines premium momentum.
Find out about the key risks to this Selective Insurance Group narrative.
Another View: DCF Points To A Very Different Fair Value
The earlier discussion framed Selective Insurance Group as slightly overvalued relative to a US$101.86 fair value. A second lens tells a different story. The Simply Wall St DCF model estimates future cash flows at US$201.51 per share, which is far above the current US$103.34 price and paints SIGI as deeply undervalued. Which valuation anchor do you treat as more reliable when both are built on reasonable but very different assumptions?
For readers who want to understand how this long term cash flow view is built, the next step is to review the full SWS DCF model in detail with Look into how the SWS DCF model arrives at its fair value.
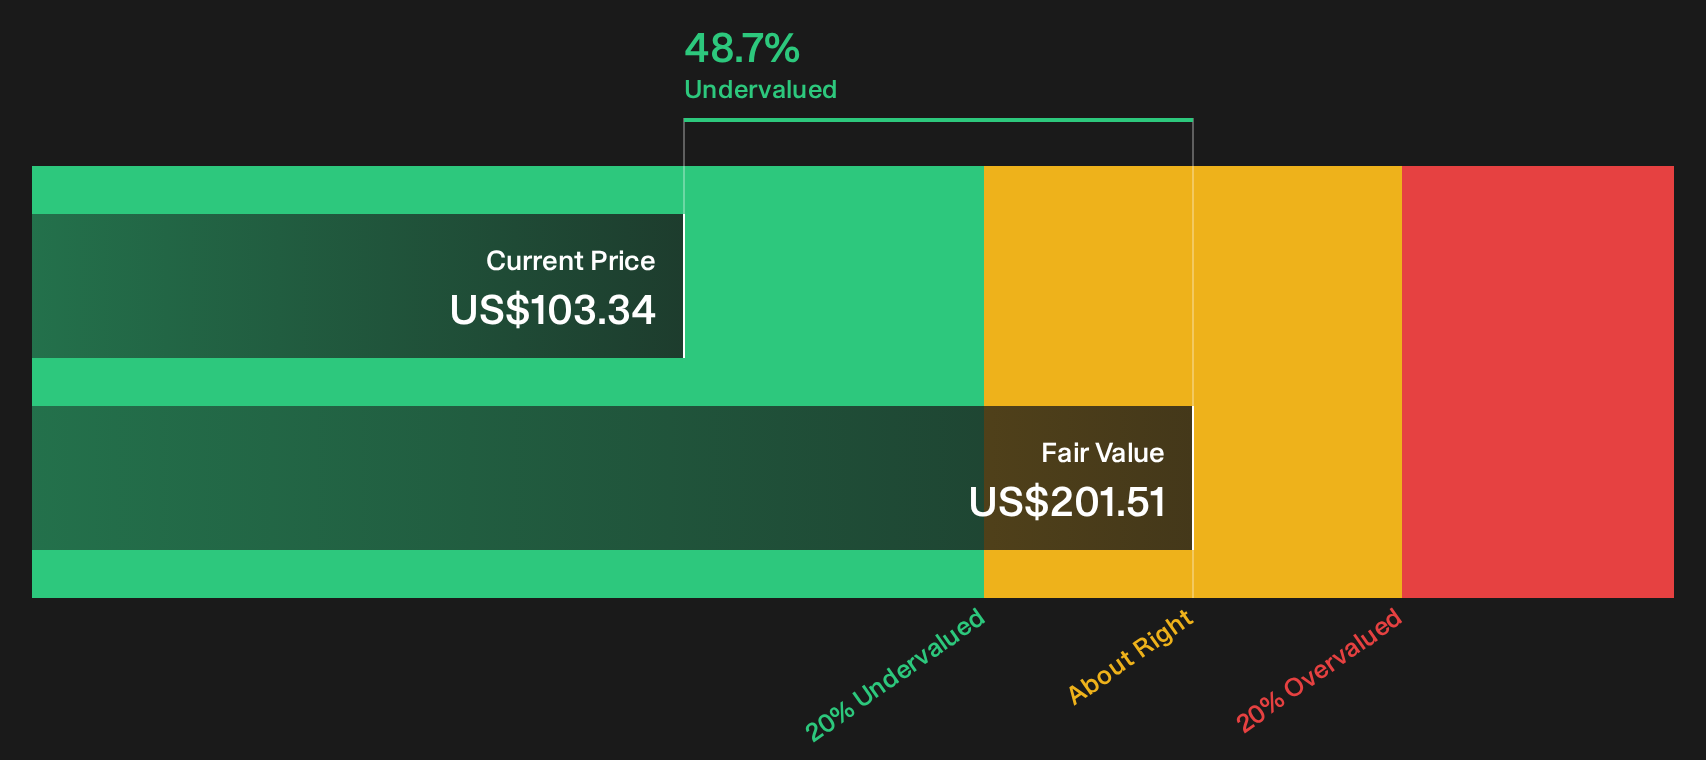
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Selective Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Selective Insurance Group so far. If you want to move fast and build your own view from the ground up, weigh the upside against the downside with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Selective Insurance Group?
If you stop with just one insurer, you risk missing opportunities where quality, pricing power, and balance sheet strength line up more clearly than they do today.
- Target potential mispricings by scanning for companies that combine solid fundamentals with appealing valuations through the 35 high quality undervalued stocks.
- Build a cash flow focused watchlist by reviewing companies offering stronger yield support using the 5 dividend fortresses.
- Prioritise resilience and capital strength by filtering for financially robust businesses with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com