


Inflation is running hotter again, rate hike chatter is back on the table, and suddenly the quiet world of insurers is getting a lot more interesting. When borrowing costs move, the value of long-term cash piles and investment portfolios can shift in ways that catch many investors off guard. This article looks at three U.S. property and casualty insurance stocks exposed to this inflation and interest rate story, and explains how their investment income may influence your portfolio decisions.
The three insurers discussed below are just a starting sample of this idea. The full screen surfaced 26 more U.S. property and casualty groups with equally compelling investment income stories that are not covered here. To go deeper into the theme, identify your own shortlist, and analyze which balance sheets and portfolios best fit your risk preferences, head straight to the U.S. Property & Casualty Insurers with Investment Income Tailwinds screener.
Selective Insurance Group (SIGI)
Selective Insurance Group sits squarely in the U.S. Property & Casualty Insurers with Investment Income Tailwinds theme. The analyst consensus Narrative on Simply Wall St highlights why its underwriting focused model and bond heavy portfolio have drawn fresh attention as rates and inflation stay elevated.
Selective Insurance Group writes commercial, personal, E&S and flood cover for U.S. businesses, local governments and individuals, generating about US$3.8b from Standard Commercial Lines, US$624m from E&S, US$394m from Standard Personal and US$577m from Investments, with a market value near US$5.9b.
"The increasing contribution from net investment income, with after tax NII of about US$119m in 2Q 2026 and updated 2026 guidance of US$480m, is supported by an A plus rated fixed income portfolio and could remain a key driver of overall earnings."
What happens if a single unseen pressure quietly reshapes how far those earnings improvements can run before underwriting needs to catch up?
That hidden pressure is exactly what the full narrative for Selective Insurance Group unpacks, showing where earnings could decouple from underwriting and how investment income might quietly reshape the story.

Everest Group (EG)
Everest Group fits the U.S. Property & Casualty Insurers with Investment Income Tailwinds theme through its mix of traditional underwriting and a large investment portfolio. The analyst consensus Narrative on Simply Wall St highlights how that combination is being reshaped by one specific funding channel.
"The growing use of third party capital through Mt. Logan, which reached about US$3.4b of assets under management by July 2026, is increasing fee based income and underwriting capacity without equivalent balance sheet leverage. This can support future underwriting income and return on equity."
This raises a question about what happens to Everest Group’s margins if a single assumption changes regarding how long that fee rich capital remains available to support reinsurance.
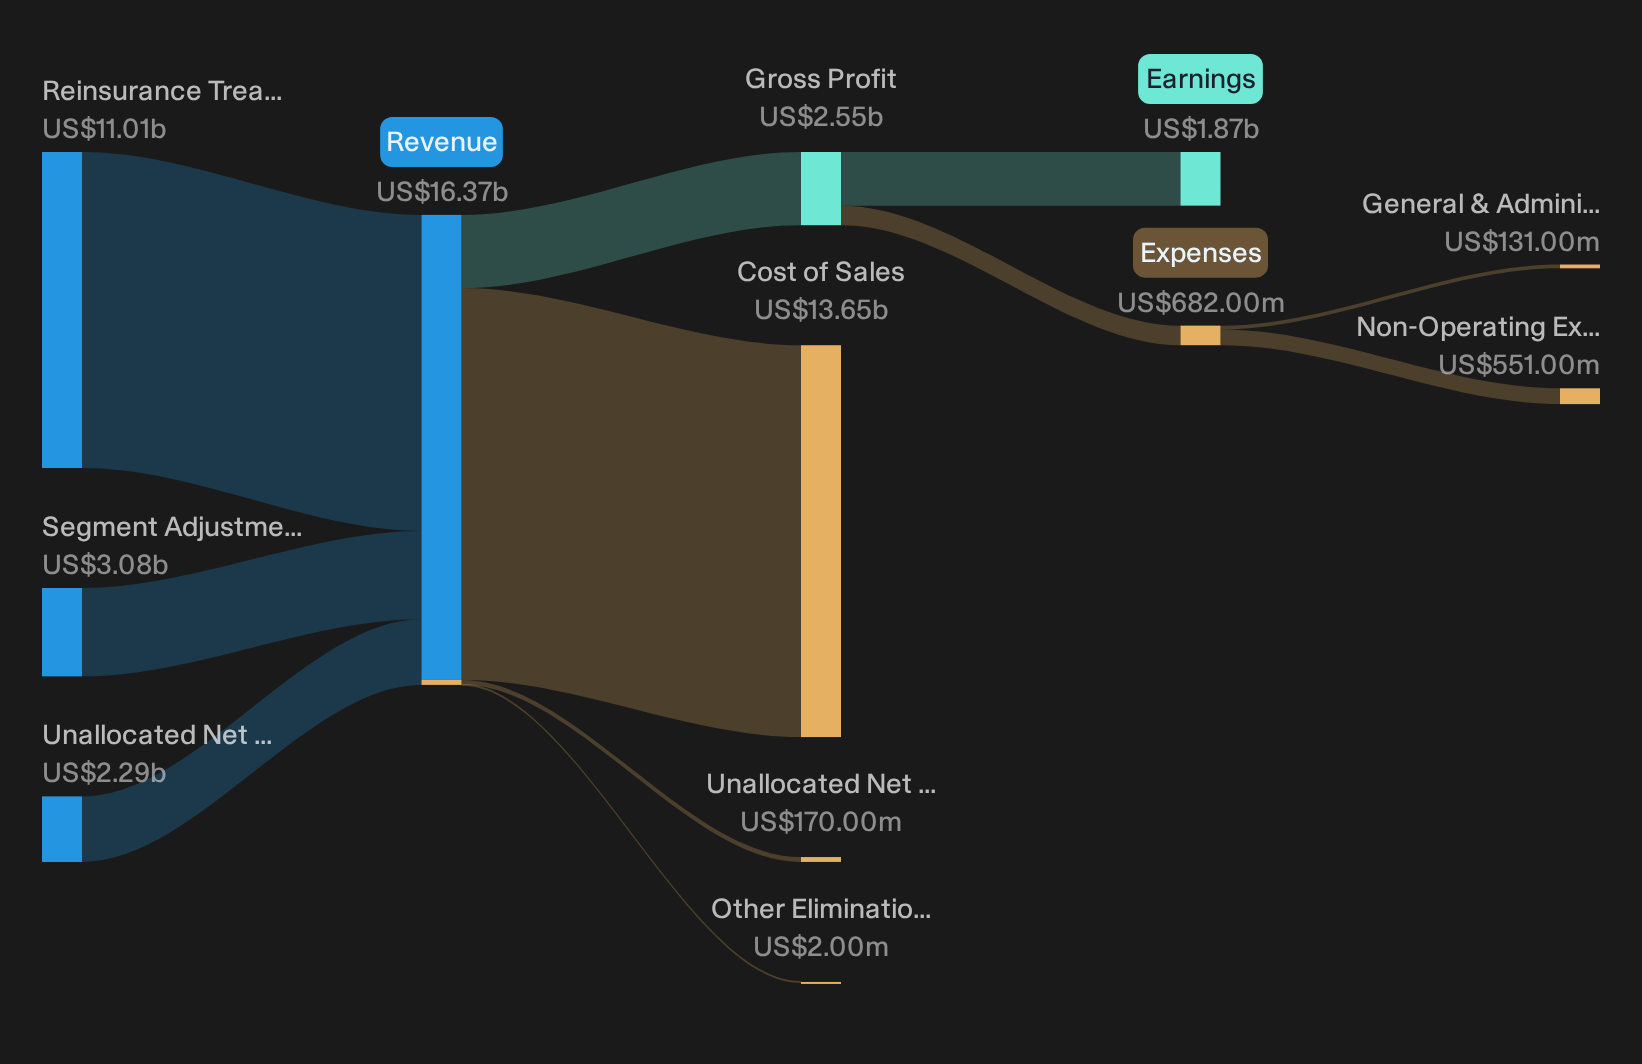
Everest Group is a global property and casualty insurer and reinsurer whose core business is writing treaty and facultative cover for commercial risks, with about US$11.0b from Reinsurance Treaty, US$3.1b from Segment Adjustment items and US$2.3b of unallocated net investment income, and a market value near US$15.3b.
That single assumption about funding stickiness is exactly what the full narrative for Everest Group unpacks. It reveals where Everest Group’s fee engine could accelerate or where margins could quietly decouple.
Kinsale Capital Group (KNSL)
Kinsale Capital Group is a pure-play specialty U.S. property and casualty insurer that leans heavily on excess and surplus business. This fits the theme of underwriting-focused carriers with meaningful float that can benefit from higher reinvestment yields as rates stay elevated.
The group generates about US$2.0b from Excess and Surplus Lines Insurance in the United States and has a market value near US$8.7b.
The bullish analyst Narrative on Simply Wall St argues that Kinsale Capital Group is built for a higher-for-longer rate backdrop. In this environment, disciplined specialty underwriting and a growing float can turn persistent inflation into a potential earnings lever rather than just a cost problem.
"Continued mix shift toward smaller excess and surplus accounts, where submissions, quotes and bind orders are growing in the mid single digits and several casualty and niche property divisions report double digit premium growth, gives Kinsale Capital Group room to offset pressure in large commercial property and support gross written premium and fee based revenue."
The real swing factor is what happens if one quiet change in how that float is invested starts to reshape the margin story.
That shift in float is the crux, and the full narrative for Kinsale Capital Group shows how Kinsale Capital Group’s underwriting engine and investment book could either accelerate together or quietly decouple.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time a breakout story hits headlines, the best entry points can be gone. Scan what others miss while it matters and get in early.
- Spot cash rich companies quietly building momentum before the crowd chases them by running the list of solid balance sheet and fundamentals (24 results).
- Target powerful income opportunities that aim to keep paying investors even when sentiment drops by reviewing the curated 5 dividend fortresses.
- Ride structural shifts in mining and electrification themes while they are still under the radar for now with the specialist 16 top copper producer stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com