


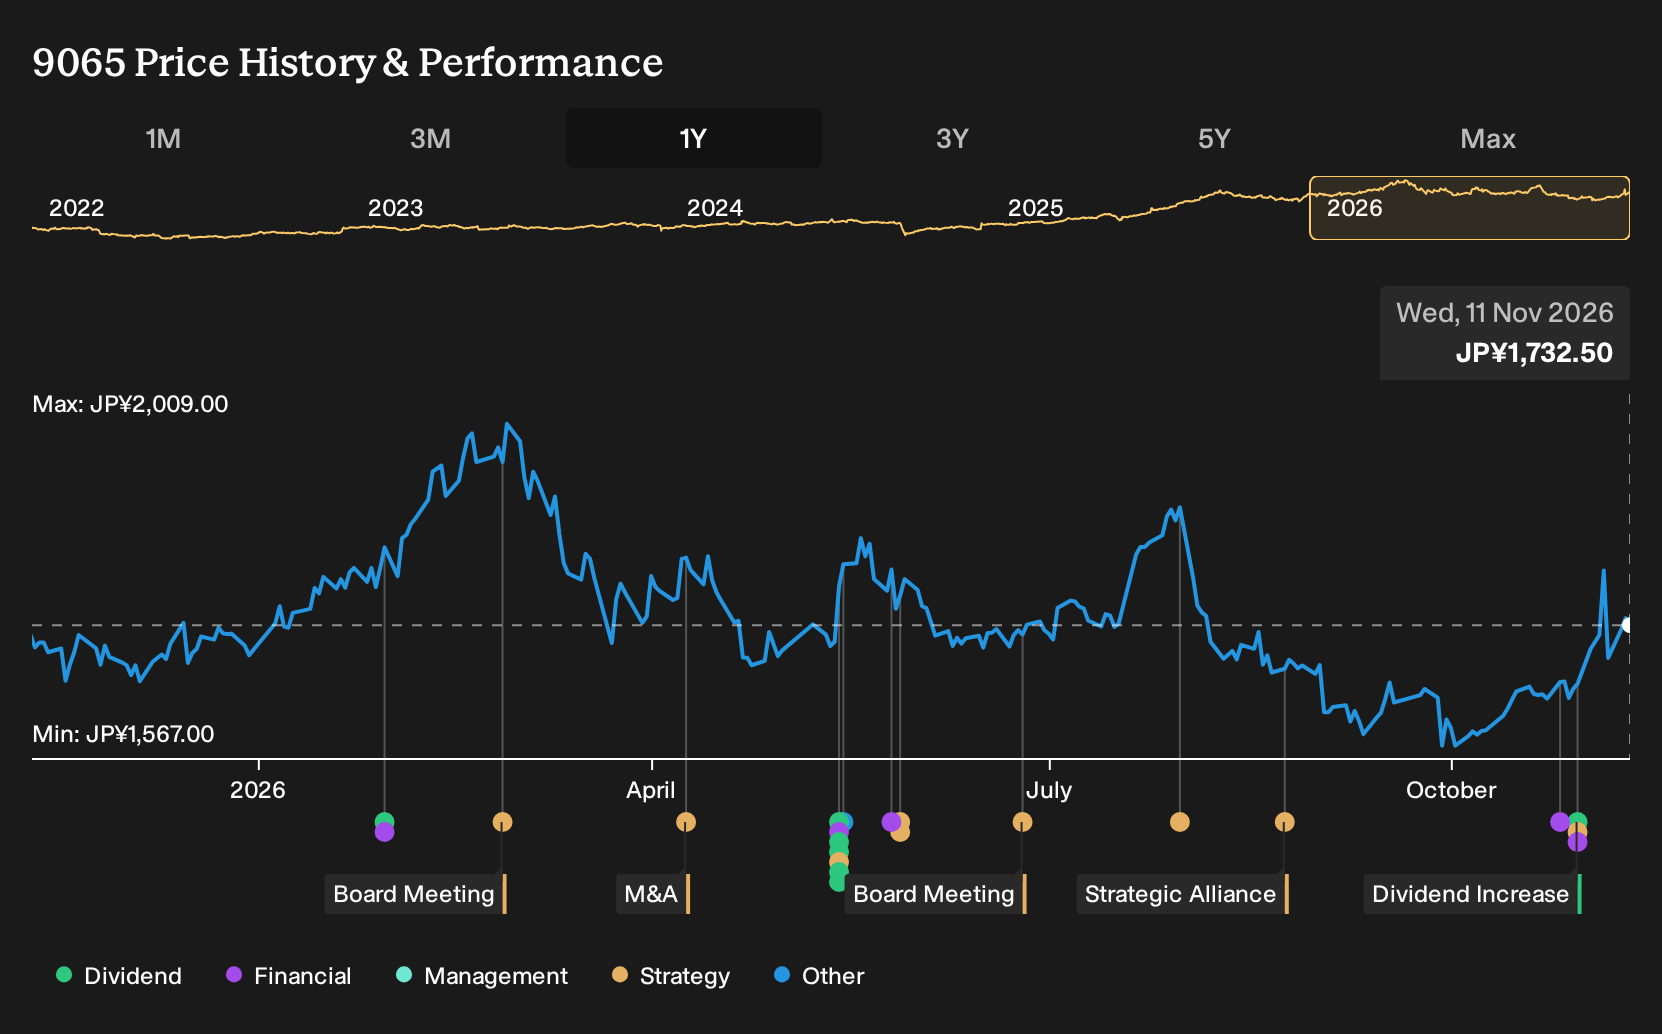
- Sankyu Inc. held a board meeting on October 30, 2026 and lowered its non-consolidated forecast for the year to March 2027, while at the same time reporting a second quarter dividend of JPY 129.00 per share, higher than the JPY 118.00 paid a year earlier.
- The revised guidance highlights softer SDM maintenance work in the Plant Engineering Business. At the same time, Sankyu is still signaling confidence in cash generation and shareholder returns through a larger interim dividend.
- Next, the focus turns to how Sankyu's investment narrative lines up with weaker non-consolidated guidance but a higher interim dividend commitment.
Compare Sankyu's mix of softer guidance and firmer dividends with other potential opportunities by scanning our hand picked 23 high quality undervalued stocks, which also balance earnings power with shareholder payouts.
What Is Sankyu's Investment Narrative?
Sankyu appeals most to investors who are comfortable with a fairly steady, capital heavy logistics and plant services story where modest growth and a regular payout matter more than large upside. The lowered non consolidated forecast points to softer SDM maintenance work in Plant Engineering, while the Logistics Business is described as running ahead of earlier expectations, helped by price changes and restructuring. That mix suggests execution risk around project timing rather than a broad demand shock for Sankyu.
In the short term, the key swing factors are straightforward. Construction volumes at domestic affiliates and continued restructuring progress at overseas logistics operations are the reasons management is keeping the consolidated outlook unchanged. The higher interim dividend and a yield around 3% come with a caution, because earnings coverage is described as thin. For an investor in Sankyu, the real question is whether that payout profile still feels comfortable if...
There's only one way to know the right time to buy, sell or hold Sankyu. Head to Simply Wall St's company report for the latest analysis of Sankyu's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sankyu research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sankyu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sankyu's overall financial health at a glance.
Looking For More Ideas Beyond Sankyu?
If Sankyu's mix of guidance and dividends has you rethinking where to put fresh capital, broaden your watchlist with a few focused stock shortlists built around different priorities.
- If income is your anchor, scan for companies that combine robust cash flows with consistent shareholder payouts via our 29 dividend fortresses.
- If balance sheet strength matters most, narrow your search to financially resilient businesses using the list of solid balance sheet and fundamentals (23 results).
- If you want mispriced quality, filter for under followed companies with strong fundamentals through the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com