


Take-Two (TTWO) reported earnings on Nov. 9, and the numbers looked weak. Net bookings fell 18% to $1.60 billion and missed guidance. Its NBA 2K demand was softer than expected, and recurrent consumer spending also dipped 9%. Management declined to raise its full-year net bookings guidance, too. Normally, after such a report, the stock is expected to get punished. But instead, it rose 7% after hours. The reason is that investors remain focused mainly on one thing: Grand Theft Auto 6, and that is the part that didn’t disappoint. CEO Strauss Zelnick said, “Pre-orders for Grand Theft Auto 6 are tracking far in excess of our initial expectations.” That is a big change in tone from when I covered the stock in September. Back then, Zelnick said he didn't want to celebrate based on pre-orders since those can be cancelled. But over time, it looks like his confidence has grown.
About Take-Two Stock
Take-Two is a video game publisher whose labels include Rockstar Games, 2K, and Zynga. Its franchises range from Grand Theft Auto, Red Dead Redemption, and NBA 2K to mobile hits like Words With Friends. Rockstar's GTA 6 is the company's biggest release in years, and Take-Two is counting on it for most of this year's growth. Founded in 1993, Take-Two is headquartered in New York City and is led by Chairman and CEO Strauss Zelnick.
TTWO stock is down 9% so far this year, underperforming the VanEck Video Gaming and eSports ETF (ESPO) that has stayed flat during this period. The largest decline came after GTA 6 was delayed a second time; its full-year guidance came in well below Wall Street's expectations, and its mobile business slowed. That said, it is up over 4% in morning trading today as hype around GTA 6's release grows.
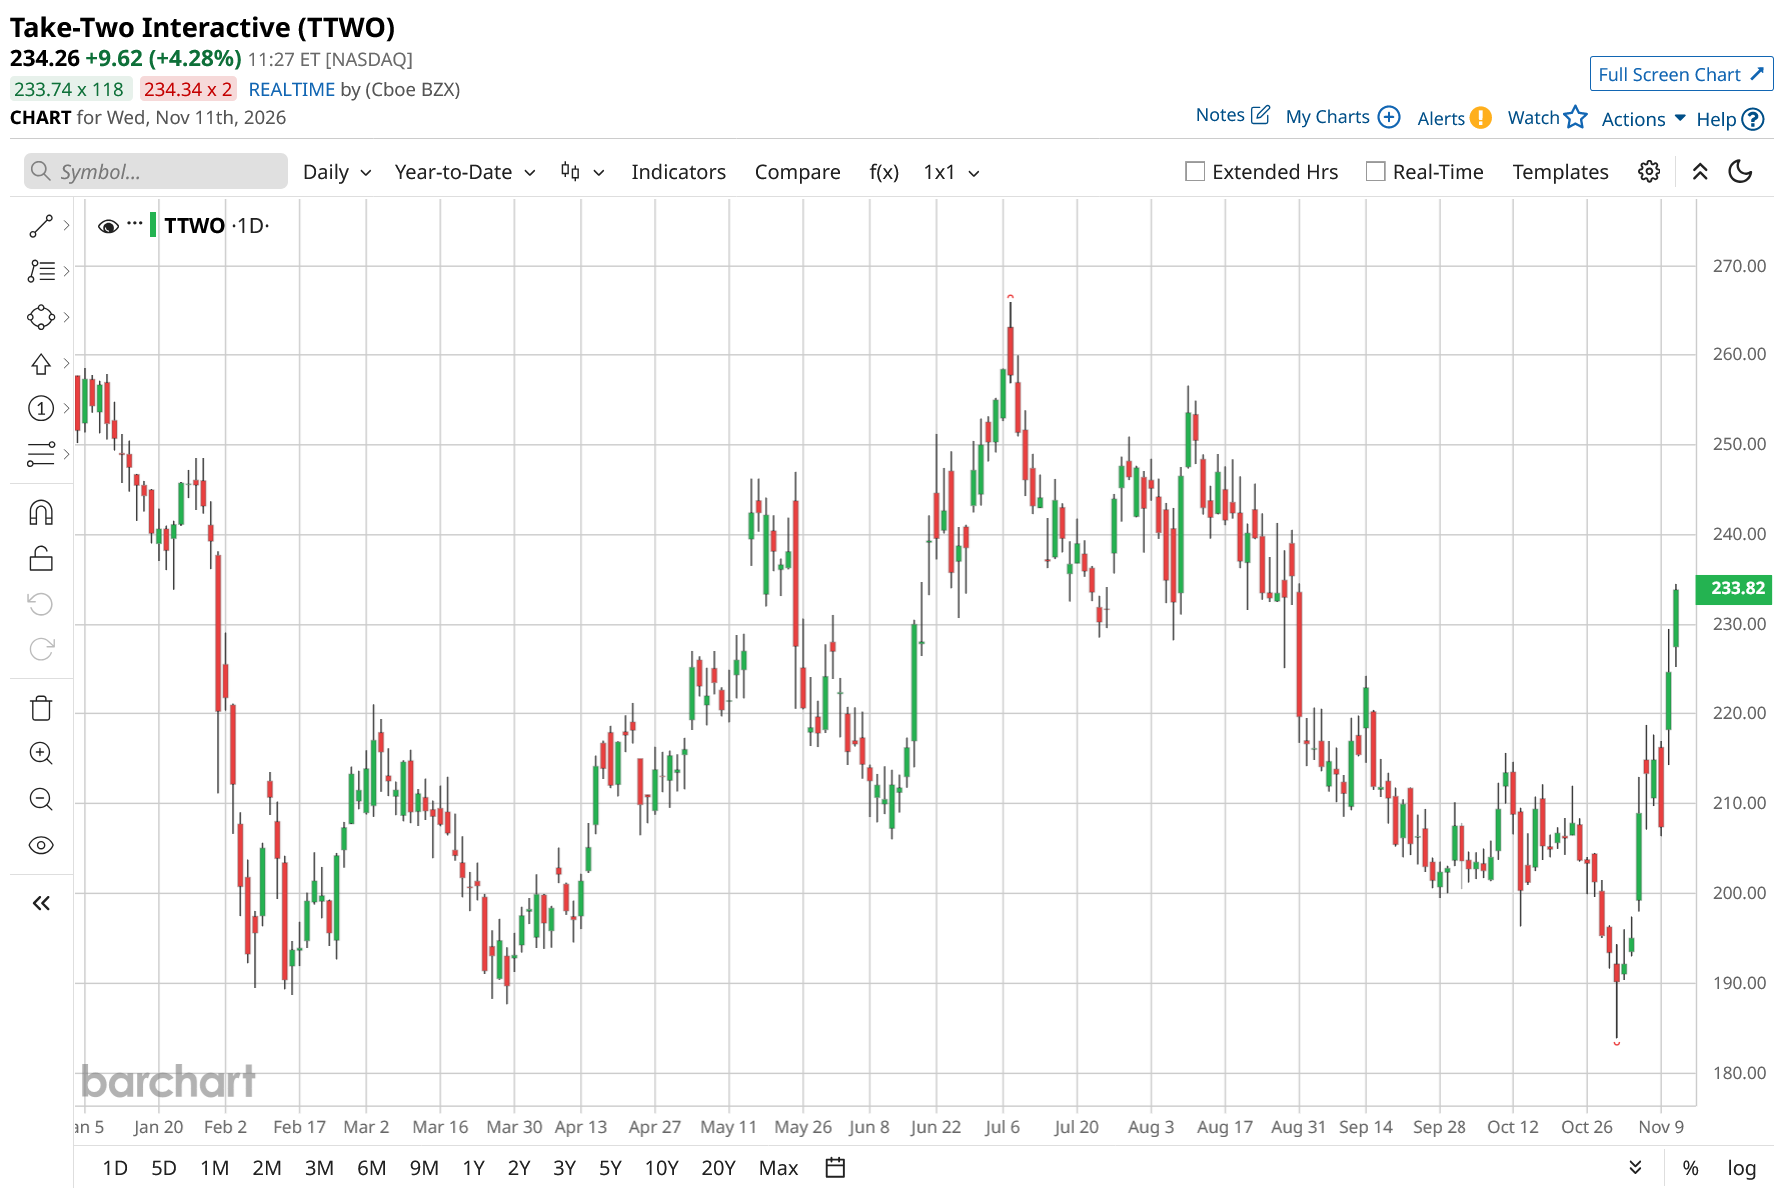
Take-Two's stock looks cheaper than usual, which is interesting to see at a time when it's about to launch arguably the most anticipated game ever. Its forward price-to-earnings (P/E) of 29.73x sits about 42% below its 5-year average of 51.08x, a steep discount. Its forward price-to-sales (P/S) ratio of 4.53x is roughly 10% below its historical average. The EPS outlook makes the discount look appealing. Analysts expect earnings to jump 70% this fiscal year and another 46% the next year as GTA 6 delivers its first full year. Growth then slows sharply in fiscal 2029, mostly due to being measured against a very high base. The balance sheet is decent, with a net debt of about $1.1 billion. I think if the GTA 6 pre-orders keep beating Take-Two's own expectations, the discount may not last long.
GTA 6 Release Date, Pre-load Time, and Price: What to Know Before Nov. 19
GTA 6 is set to be released on Nov. 19, 2026, on PS5 and Xbox Series X/S. Its pre-load started on Nov. 10, at midnight local time on PS5, and 12 a.m. GMT worldwide on Xbox. There hasn't been a PC version announced yet. Rockstar says players will need up to 212 GB of free space to download the game. It's priced at $79.99 for the Standard Edition and $99.99 for the Ultimate Edition. That's a steep price for a game, but since players have waited years for it, the company knows they'll be willing to pay for it. And this can be seen in the numbers, too. Sensor Tower counted about 10 million digital pre-orders as of Nov. 11. And as of late August, nearly 90% of pre-orders were for the Ultimate Edition. Zelnick also confirmed on the call that Rockstar has finished developing the game, which ends years of fears about delays.
The company kept its full-year guidance of $8.0 billion to $8.2 billion, expecting most of the growth to come from GTA 6. I think management refusing to raise its guidance before launch seems a bit conservative, since pre-orders are already beating Take-Two's own expectations. So the setup favors an upside surprise. The risk is that with the expectations being so high, the first sales figures need to be extraordinary. But I think that's undoubtedly what it will be, with Take-Two announcing record launch sales within days of Nov. 19.
A Weak Quarter With a Big Launch Ahead
Despite all this, Take-Two reported its second-quarter results on Nov. 9. Its loss of $0.29 per share was far smaller than the $0.86 loss analysts expected. But spending from existing players, such as in-game purchases, fell 9%, even though it still made up 81% of total net bookings.
Looking ahead, Take-Two raised the low end of its full-year profit outlook. CFO Lainie Goldstein called the level of GTA 6 pre-orders “extraordinary.” Management is also pushing its mobile games to sell directly to players and is adding brand advertising to them, both aimed at improving margins.
What Do Analysts Expect for TTWO Stock?
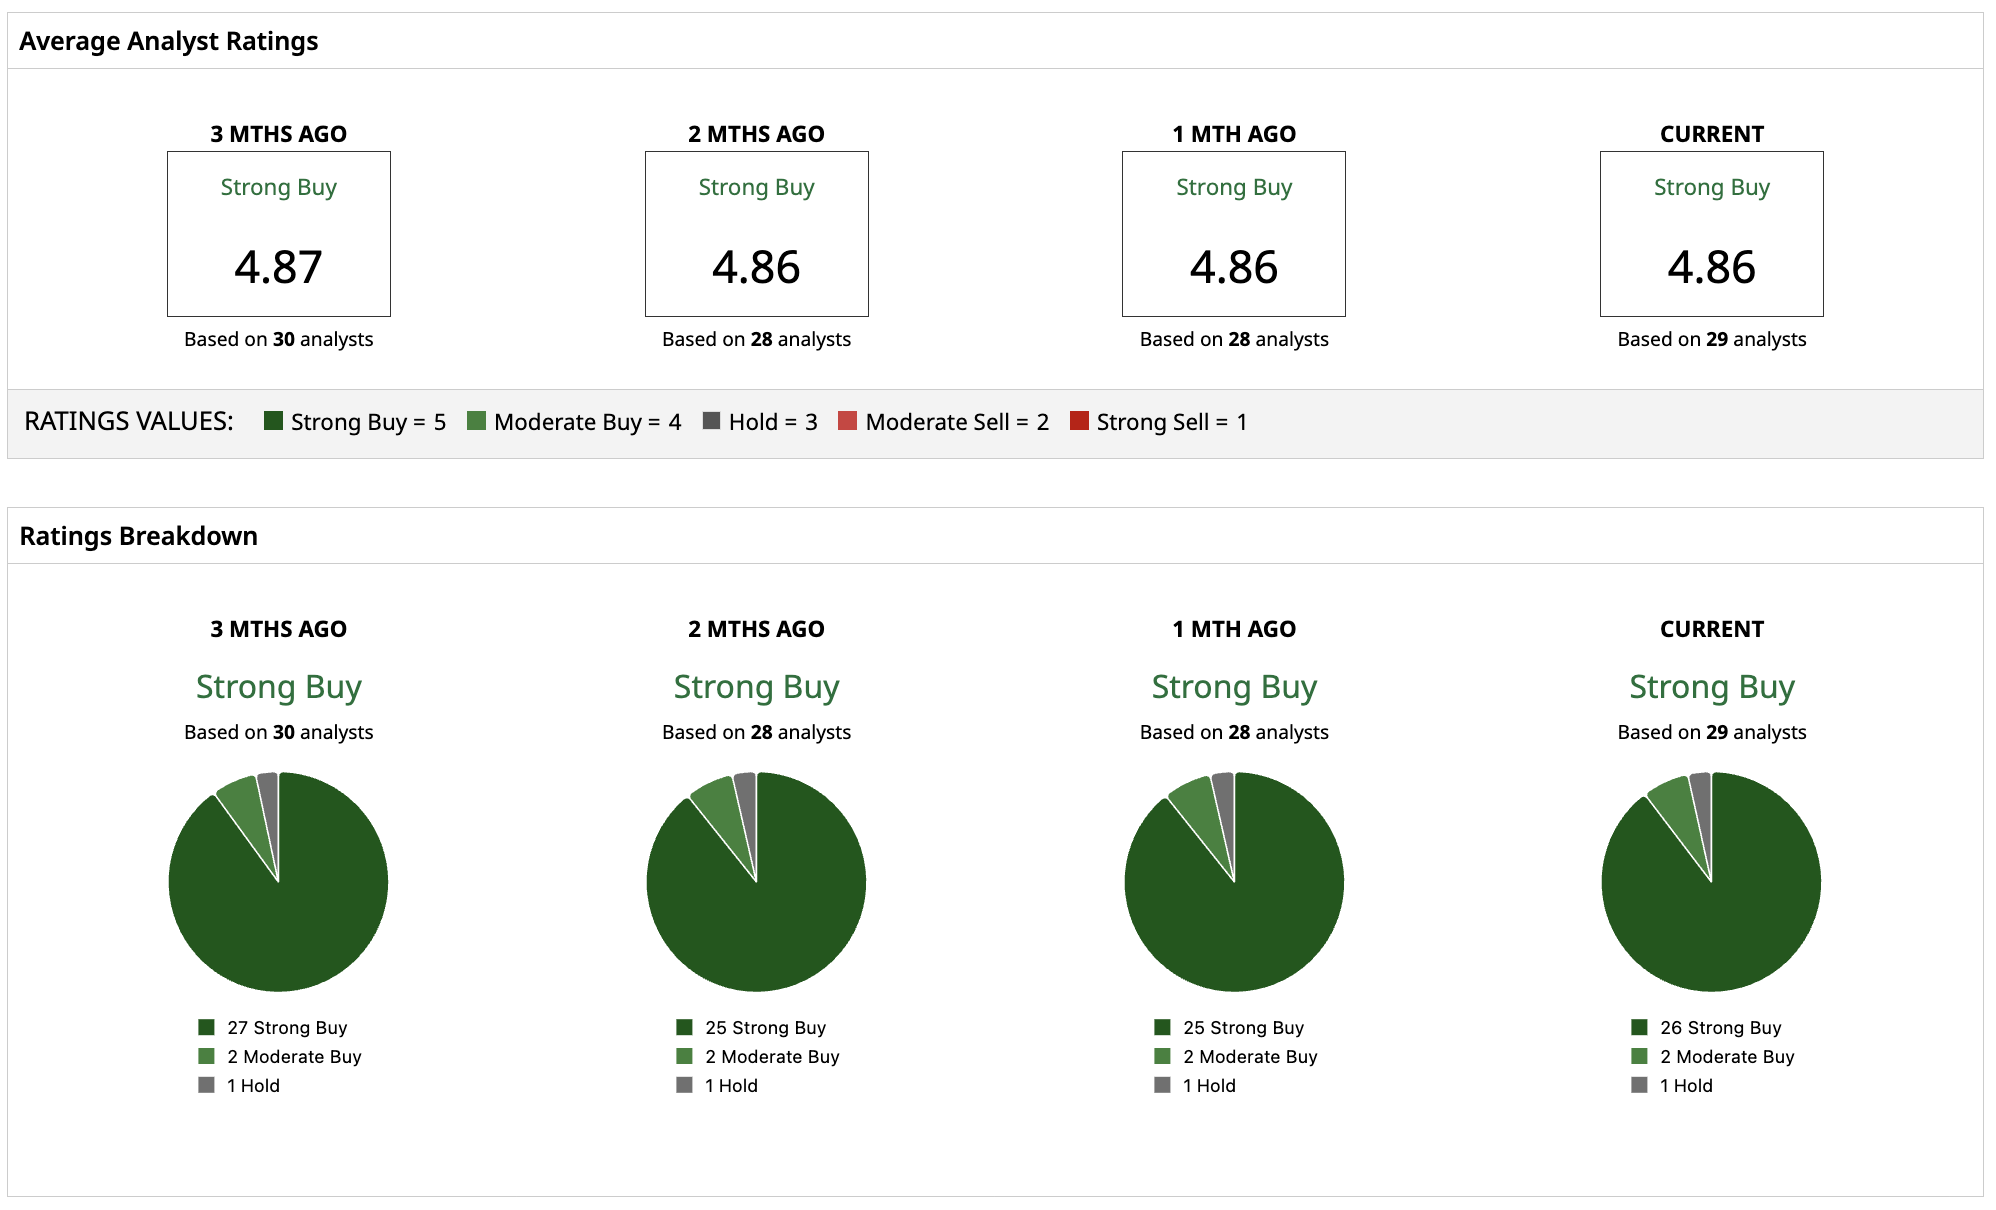
Based on 29 Wall Street analysts, TTWO stock holds a “Strong Buy” rating with a mean price target of $285.70, indicating 22% upside. The healthy upside makes sense to me for a stock that is down 9% YTD and is about to launch, perhaps, its biggest game yet.
On the date of publication, Jabran Kundi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.