


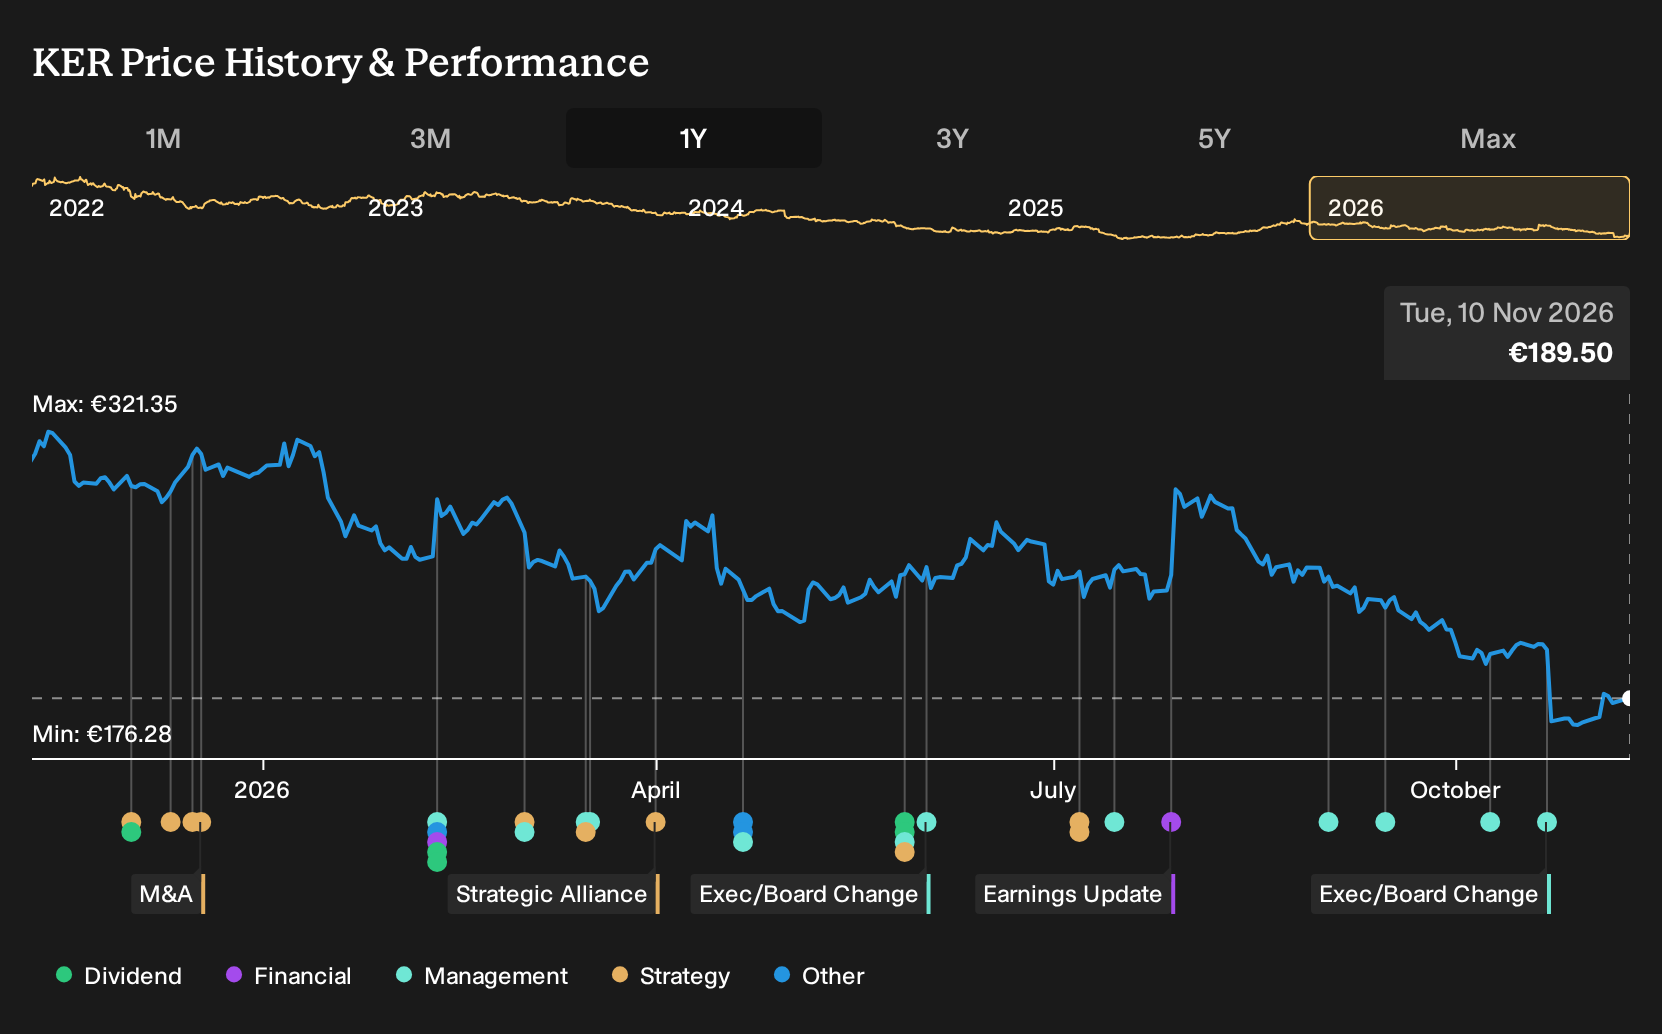
If you had decided on 10 November 2025 to back the bullish view on Kering, expecting a luxury rebound and higher margins, the financial outcome looked very different a year later. For Kering shareholders, the loss over the past year was 39.2%, including dividends. With Gucci weakness, store closures and restructuring now front of mind, which assumptions from that earlier optimism would you want to stress test before making the same call again?
The easy part of this move is behind Kering. Zero in on 200 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Kering
The shares cost €310 at the start of the period, so anyone buying Kering then was choosing between two very different stories about what came next.
On the bullish side, the June 2025 Narrative pointed to a Fair Value of €360. This was a price implied by assumptions that rising global wealth and stronger e-commerce would lift Gucci and other houses, with revenue growing 6.3% a year and margins reaching 9.6%.
The October 2025 bear case set Fair Value at €208, again an implied number. It focused on risks that store closures, weaker tourism and brand fatigue, including Gucci down 25% in H1, could keep pressure on revenue and earnings even with cost cuts.
What The Facts Did To The Kering Argument
Kering’s H1 2026 report showed revenue of €7,220m versus €7,439m in H1 2025, and net income of €136m versus €429m. Net margin fell from 5.8% to 1.9%. That challenged the bullish thesis that quicker Gucci renewal and cost savings would lift profitability. Management’s ReconKering plan and over 100 store closures supported the more cautious case focused on execution risk.
The whole decision hinged on whether margin recovery would arrive quickly. When you assess another luxury group, track net margin alongside store closures and restructuring announcements rather than relying on narrative alone.
What Kering’s Lower Price Asks You To Believe
Kering now trades at €190, with this Narrative’s Fair Value sitting above that level according to the analyst consensus Narrative on Simply Wall St. The current bullish case leans on Gucci’s Rinascimento overhaul, a tighter store network and faster growing jewelry and eyewear to reshape the profit mix.
For the drop to look like an opening rather than a warning, a buyer today would need to believe Gucci’s reset and Asia demand stabilisation can translate those changes into sustained earnings and margin recovery.
"The main requirement is effective execution of Gucci’s Rinascimento plan while keeping inventory, store closures, and group-wide platform projects aligned without eroding brand strength. The current valuation suggests investors are heavily discounting Gucci’s recovery and the earnings contribution of jewelry, eyewear, cost savings, and deleveraging, which supports a positive view on the share price."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Kering’s Boutiques
Kering’s story leads you to luxury logos and heritage houses. Just beyond those windows, another kind of brand power is working quietly.
Think about what people wear when they are not dressing up. Everyday sport, gym sessions and weekend matches build a separate kind of loyalty.
An unnamed global business leans on that habit, turning regular training, fandom and lifestyle into steady demand for footwear and clothing.
Its challenge is not recognition, but turning immense reach into stronger profitability.
If it can cut costs while deepening that daily connection, its long-haul earnings profile may shift in meaningful ways.
One Narrative has already put a figure on it. → Uncover the company trading 20% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com