


Fresh attention is landing on Croda International (LSE:CRDA) after recent commentary pointed to an improved earnings outlook and more positive analyst sentiment, as reflected in an upgraded Zacks Rank for the stock.
The upgraded earnings outlook follows a strong rebound in momentum, with Croda International’s share price delivering an 11.41% three-month return and a 32.79% year-to-date gain, even though the five-year total shareholder return is still down 58.17%.
Compare Croda International’s rebound with a hand-picked 16 high quality undervalued stocks that the market may not be fully pricing in yet.
Croda International has rallied hard, yet the shares still sit at a discount to both analyst targets and one estimate of fair value. Are investors rightly cautious, or has the recent move not fully closed the gap?
Most Popular Narrative: 5% Undervalued
Croda International closed at £36.41, while the analyst consensus Narrative on Simply Wall St places fair value at about £38.36 using a 7.84% discount rate, pointing to a modest gap that depends heavily on execution.
The main requirement for success is that premium beauty actives, ingredient branding, biotech capabilities and the pharma portfolio rebalance continue to translate into higher quality sales and margin gains, while the transformation and working capital programmes deliver planned savings.
The current valuation and external commentary, including views that the stock could be roughly 12% undervalued, suggest that the share price already reflects Croda International as fairly valued, with meaningful recovery and margin improvement still to be achieved through execution.
See why 31 investors see Croda International as 5% undervalued.
Result: Fair Value of £38.36 (UNDERVALUED)
Still, the Croda International story carries clear pressure points, including execution risk on its £100m transformation and potential margin strain if pricing pressure in key ingredients persists.
Find out about the key risks to this Croda International narrative.
Another View: What Croda International’s P/E Is Telling You
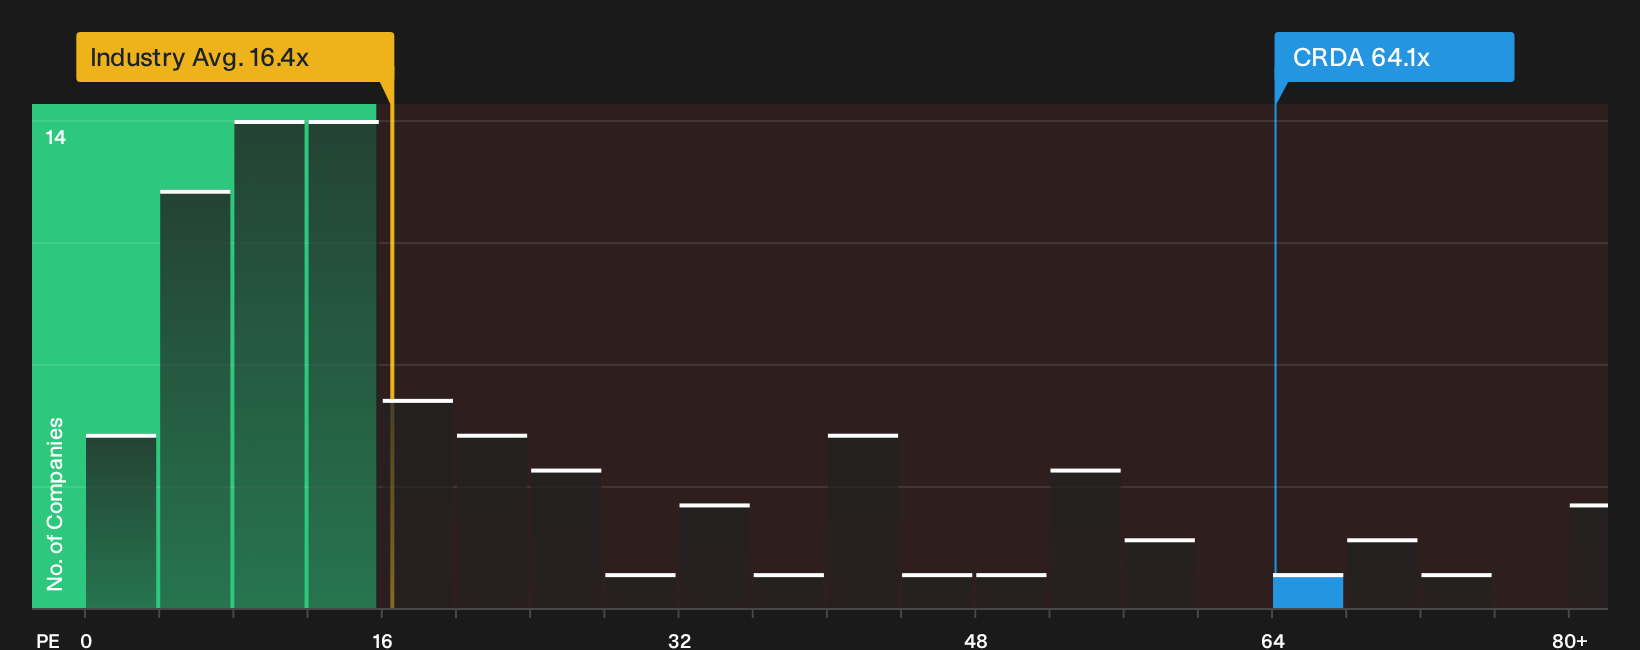
The DCF work suggests Croda International trades below an estimate of future cash flow value. Yet the market is paying 64.1x P/E today versus a fair ratio of 20.1x, the European chemicals group at 16.8x and peers at 28.9x. Is that a cushion or a valuation tightrope?
To see how that earnings multiple gap could close in practice, and what it might mean for future returns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Croda International is split, with clear risks on one side and tangible potential on the other. Move quickly and stress test the data for yourself using our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Croda International?
If you only stop with Croda International, you risk missing other opportunities that could better match your goals, risk profile and income needs.
- Target potential mispricing by scanning a curated 16 high quality undervalued stocks that might offer stronger value than what is already in your portfolio.
- Strengthen your income stream by reviewing a focused 6 dividend fortresses that highlights yields above 5% with a focus on stability.
- Upgrade portfolio quality by comparing companies in a list of solid balance sheet and fundamentals (9 results) that pairs resilient finances with sound fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com