


- Recent commentary on Origin Energy has highlighted how rising rooftop solar, home batteries and customer electrification products are reshaping demand for grid supplied power and could alter the mix of cash generation across its electricity, gas and LNG activities.
- The unique angle is how Origin Energy’s heavy spending on renewables, grid scale batteries and digital platforms now intersects with flatter grid volumes. This may test whether these projects genuinely lower cost to serve and support more predictable earnings from energy markets and APLNG over time.
- We will now look at how Origin Energy’s investment narrative is affected by weaker grid visibility from rooftop solar and battery adoption.
Scan 4 high quality undervalued stocks that, like Origin Energy, combine sizeable energy or infrastructure cash flows with balance sheets that may not be fully reflected in current market pricing.
Origin Energy Investment Narrative Recap
To own Origin Energy, you need to believe the heavy spend on renewables, grid batteries and platforms like Kraken and Octopus eventually turns into lower cost to serve and steadier cash from Energy Markets and APLNG. The analyst consensus Narrative on Simply Wall St currently bakes in flat revenue and shrinking margins, so execution really matters.
The near term catalyst is whether new behind the meter solar and batteries are managed well enough through Origin Energy's virtual power plant and digital tools to protect electricity margins. The main risk is that rooftop and battery uptake erodes grid volumes faster than cost savings and LNG contributions can offset.
Recent commentary around rooftop solar and batteries directly connects to that risk. Origin Energy already has material exposure to distributed resources through its 1.6 GW virtual power plant, 1.8 GW grid battery pipeline and Yanco Delta wind project, so any change in grid visibility feeds straight into how predictable those energy market earnings feel.
Those same developments interact with what analysts expect from APLNG and the global Kraken and Octopus roll out. If execution on these projects keeps cost to serve in check while APLNG continues to provide steady distributions, the current view of modest earnings pressure may prove conservative on operations, even if headline demand for grid power stays broadly flat.
What The Current Forecasts Assume For Origin Energy
Origin Energy's narrative projects A$15.4b revenue and A$1.2b earnings by 2029. Analysts are assuming revenue stays broadly flat over the next 3 years and that earnings fall by A$400m from A$1.6b today to reach that 2029 consensus level.
Uncover why Origin Energy's fair value is consistent with its current price.
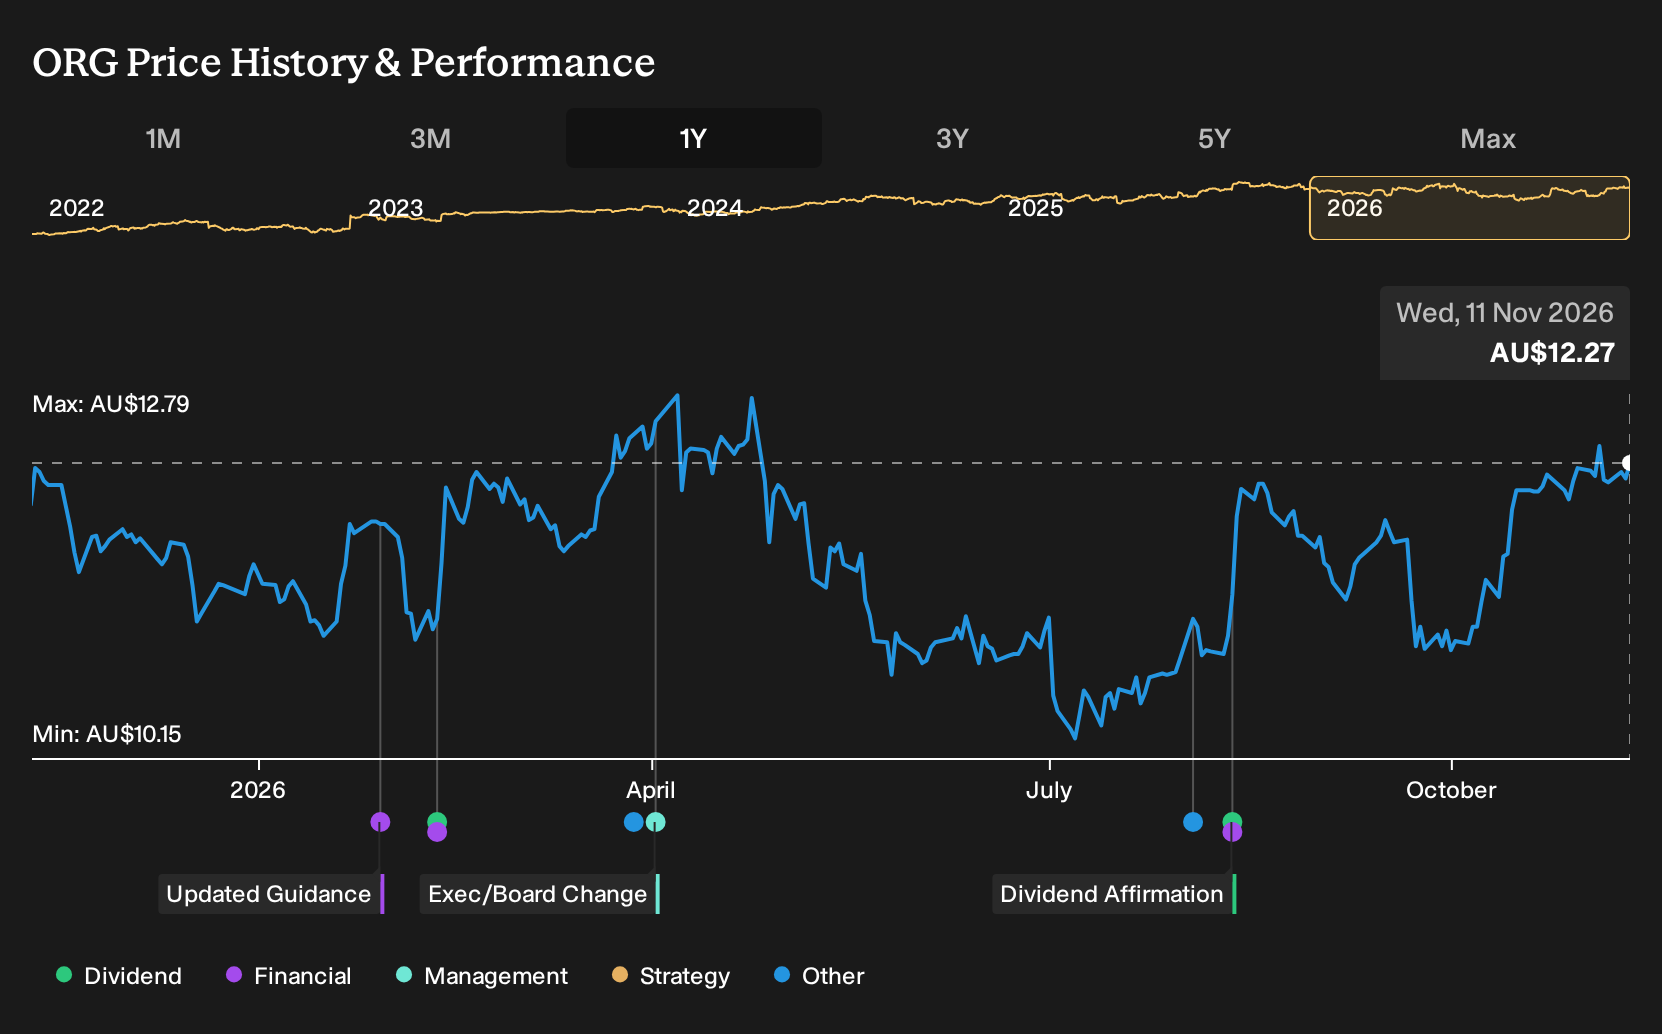
Exploring Other Perspectives
The Simply Wall St Community has only four fair value views on Origin Energy, spanning roughly A$12.17 to A$23.63, so private investors are clearly not aligned on what the shares are worth. When you set that against execution risks around Kraken, Octopus and large scale batteries, you can see why opinions differ. Explore the full range of viewpoints before deciding how Origin Energy fits your portfolio.
Explore 3 other Origin Energy fair value estimates, including one that suggests as much as 93% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Origin Energy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Origin Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Origin Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Origin Energy?
Once you have a view on Origin Energy, widen the lens and use the Simply Wall St Screener to spot other opportunities that fit your preferred mix of quality, income and risk.
- If you want potential mispricing with strong fundamentals, start with a 4 high quality undervalued stocks that may highlight businesses where cash flows and balance sheets are not fully recognised in current valuations.
- If capital preservation matters most to you, filter for companies with steadier profiles using a 6 resilient stocks with low risk scores that aims to surface resilient stocks with lower risk scores.
- If you are hunting for underfollowed potential, scan a 14 high quality undiscovered gems that focuses on fundamentally sound businesses which might not yet be widely on the market's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com