


- Liberty Global reported third quarter 2026 sales of US$1,920.6 million and net income of US$457.9 million, compared with a loss in the prior year period. Earnings per share from continuing operations turned positive on both a basic and diluted basis.
- Across the first nine months of 2026, Liberty Global recorded sales of US$4,367.2 million and moved from a multi billion dollar loss to a profit, indicating a material shift in how its operations are converting revenue into earnings.
- The focus now turns to what this sharp swing to profitability might mean for Liberty Global's complex investment narrative and asset monetization plans.
Scan how Liberty Global's earnings swing compares by lining it up against 20 high quality undiscovered gems that are quietly converting revenue into profits across the market.
Liberty Global Investment Narrative Recap
To own Liberty Global, you need to believe management can turn a complex mix of European telecom stakes and infrastructure into consistent cash generation for the parent. FRAGMENTS, a Simply Wall St Community investor who wrote the Narrative, argues that value depends on monetizing assets like Ziggo, Wyre and the private portfolio. The sharp move to profit in 2026 helps that story, but the key near term catalyst is still execution on disposals, listings and refinancing activity.
The biggest risk stays the same. Heavy debt at the underlying telecom units, competitive pressure at Virgin Media O2 and capital intensity can limit cash coming back to Liberty Global. The quarterly profit and positive earnings per share show the model can produce earnings, yet investors still need clearer evidence on sustainable free cash flow and how proceeds from any future transactions filter to shareholders.
The earnings release for the third quarter and first nine months of 2026 is the most relevant update here. Liberty Global reported US$1,920.6 million of sales and net income of US$457.9 million for the quarter, with basic earnings per share from continuing operations at US$1.35. Over nine months, the group recorded US$4,367.2 million of sales and a profit of US$430.6 million, after a very large loss in the prior year period.
Those figures directly touch the catalysts FRAGMENTS highlighted. Better reported profitability gives management more room to argue for asset values, to engage lenders and to consider further portfolio actions, even though forecasts still flag an unprofitable outlook over the next three years at the Liberty Global level. The risk side remains tied to leverage, cash upstreaming from Virgin Media O2 and the timing and pricing of any future asset sales or listings.
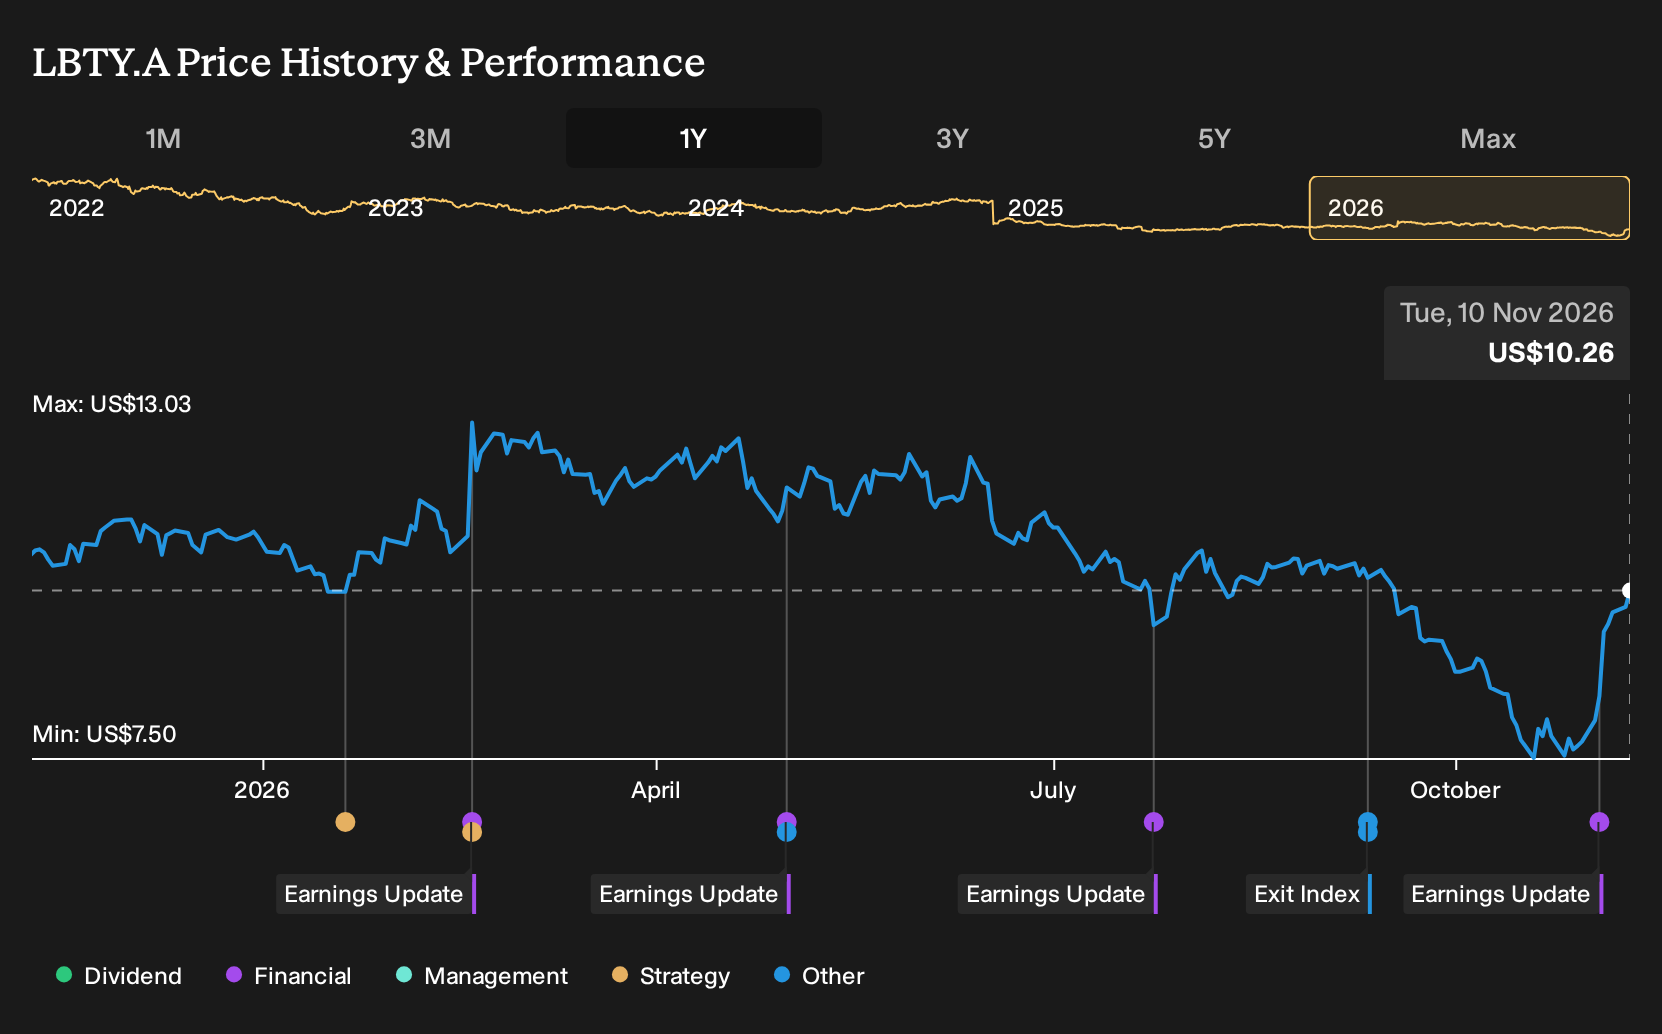
In FRAGMENTS' valuation narrative, the US$12.00 fair value for Liberty Global reflects a central case that assumes reasonable asset realizations, a gradual improvement in cash generation from the European operations, and refinancing conditions that remain manageable rather than overly stressful.
Uncover why Liberty Global's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on debt and Virgin Media O2, and more on Liberty Global’s potential earnings power. Before this profit swing, they were pencilling in revenue of about US$10.5b and earnings of US$930.0m by 2029. That is a far more upbeat story. Use this quarter as your cue to compare both narratives.
Explore 2 other Liberty Global fair value estimates, including one that suggests as much as 136% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent judgment.
- A great starting point for your Liberty Global research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Liberty Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Global's overall financial health at a glance.
Looking for more investment ideas beyond Liberty Global?
Once you have formed a view on Liberty Global, it helps to set it alongside other potential opportunities and compare the return and risk trade off across your watchlist.
- For investors hunting for underappreciated quality, review a carefully filtered group of companies with stronger fundamentals and compelling valuations through the 35 high quality undervalued stocks.
- If balance sheet strength matters most to you, start with businesses that pair lower financial risk with healthier funding structures by scanning the list of solid balance sheet and fundamentals (24 results).
- Income focused readers can screen for reliable payers with elevated yields and sturdier payout profiles by using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com