


Phillips 66 (PSX) is back in focus after a long term supply deal with Restaurant Technologies that channels used cooking oil from more than 45,000 U.S. food service outlets into California renewable fuel production.
Recent trading has cooled after a strong run, with Phillips 66’s share price at US$250.70. The 7-day and 30-day share price returns are down 7.81% and 9.88%, respectively, even as the 90-day share price return is up 11.14% and the year-to-date share price return sits at 92%.
Scan beyond Phillips 66 and compare this renewable fuels story with other energy players by reviewing our hand picked 41 power grid technology and infrastructure stocks, which is aligned with critical infrastructure demand.
After a huge year-to-date climb and a recent pullback, Phillips 66 now trades below both its analyst target and an estimated intrinsic value. Is that a genuine margin of safety, or is the market flagging real risks?
Most Popular Narrative: 14% Overvalued
On the bearish analyst Narrative on Simply Wall St, Phillips 66 screens as overvalued, with a fair value of about $220.48 against the last close at $250.70. This puts the current quote above that pessimistic fair value line while still within the broader analyst target range.
The plan to reach an adjusted controllable cost of about US$5.50 per barrel in Refining by the end of 2027 relies on hundreds of individual initiatives. Any slowdown in execution or reversal of recent cost savings could leave unit costs structurally higher, which would pressure net margins if crack spreads soften at the same time.
See why 0 investors see Phillips 66 as 14% overvalued.
Result: Fair Value of $220.48 (OVERVALUED)
Still, if Phillips 66 keeps pushing refining costs toward that US$5.50 per barrel target and Midstream earnings move toward the US$4.5b goal, this bearish narrative could unravel fast.
Find out about the key risks to this Phillips 66 narrative.
Another View: Phillips 66 Through A Cash Flow Lens
The bearish narrative leans heavily on analyst targets and earnings multiples. A different picture appears when looking at Phillips 66 through the SWS DCF model, which suggests the shares at $250.70 trade at a very steep discount to an estimated future cash flow value of $985.55. Is the market mispricing long term cash generation, or are the inputs here too generous?
Look into how the SWS DCF model arrives at its fair value.
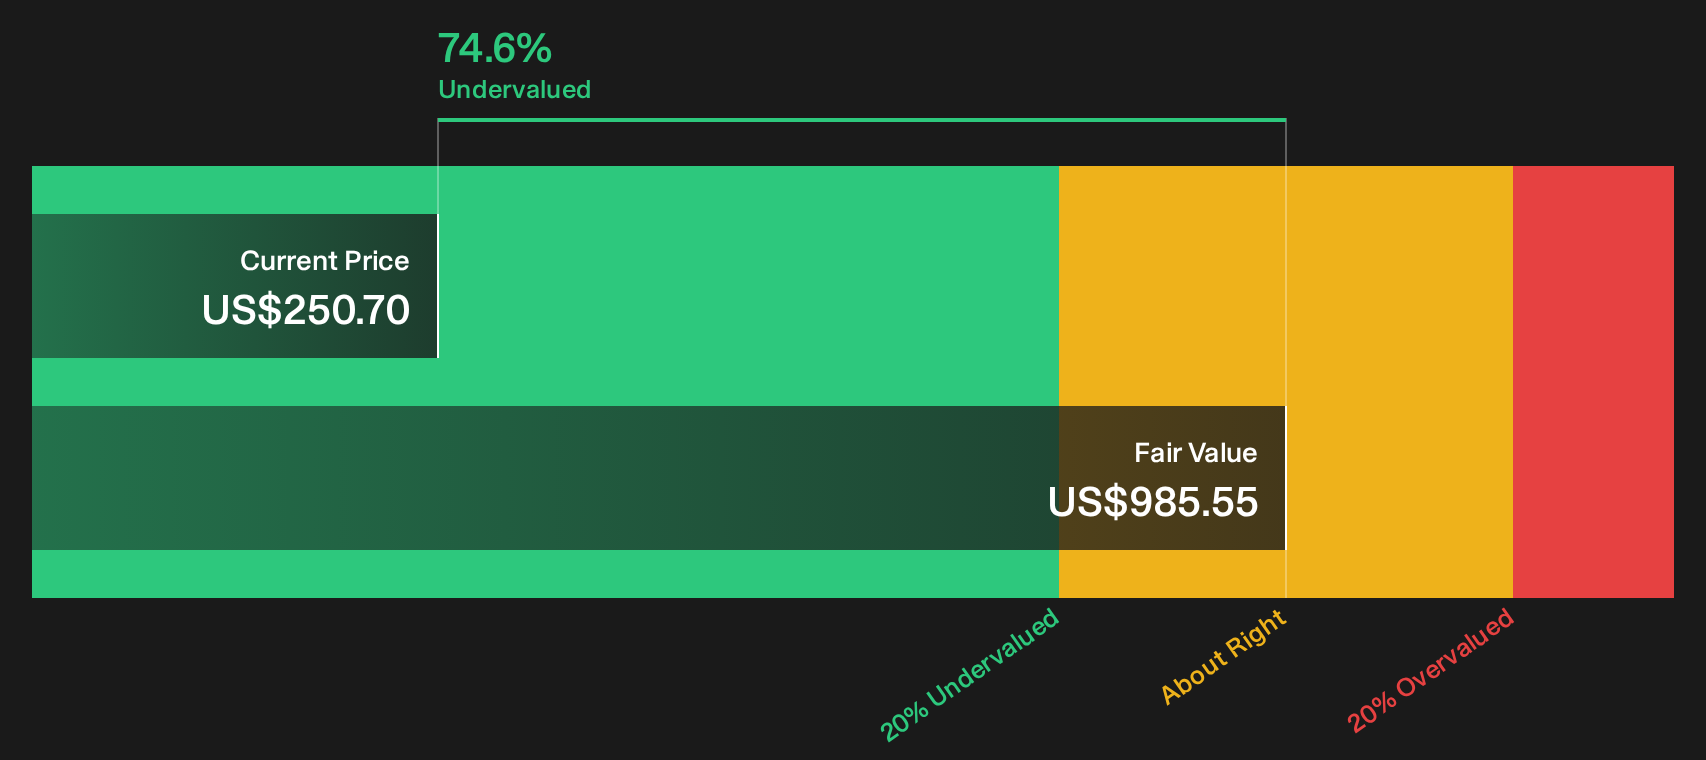
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Phillips 66 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Phillips 66 is clearly split. Move quickly, review the underlying data for yourself, and weigh both sides of the story using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Phillips 66?
If Phillips 66 has sharpened your focus on opportunity and risk, do not stop here. Broaden your watchlist and pressure test your thinking with fresh ideas.
- Target firms that combine quality and attractive pricing by reviewing our hand picked 35 high quality undervalued stocks and see which ones deserve a closer look.
- Strengthen the defensive side of your portfolio by scanning a 30 resilient stocks with low risk scores that filters for resilience when conditions get tougher.
- Spot companies with cleaner finances and sturdier foundations through a list of solid balance sheet and fundamentals (24 results) that surfaces businesses built to endure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com