


SECOM (TSE:9735) continues to draw attention after its recent share price performance, with the stock last closing at ¥6,765. Investors are weighing that move against the group’s diversified security and services footprint.
Recent trading has been mixed for SECOM, with a small 1-day share price decline of 0.59% set against a 30-day share price return of 6.23% and a year-to-date share price gain of 22.18%. That pattern points to momentum that has cooled only slightly in the very short term, while longer term investors have seen a 1-year total shareholder return of 32.21% and a 5-year total shareholder return of 88.96%, indicating that the market has been steadily reassessing both its growth potential and risk profile.
Scan how SECOM compares with other resilient service providers by reviewing a curated 19 resilient stocks with low risk scores that screens for balance sheet strength alongside more measured share price moves.
SECOM now trades only modestly below both intrinsic value estimates and analyst targets after a strong run. Is that discount a cautious market mispricing or a fair reflection of risk?
Price-to-Earnings of 24.3x: Is it justified?
On a simple P/E lens, SECOM looks expensive, with the stock trading on 24.3x earnings compared with a peer average of 16.9x and a wider JP Commercial Services mark of 12.6x. That richer tag sits alongside a last close of ¥6,765 and a share price that already reflects strong recent returns.
The P/E ratio tells you how much investors are willing to pay today for each unit of current earnings. For a diversified security and services group like SECOM, that figure often captures expectations around the resilience of its cash flows, the quality of its contracts, and the breadth of its service lines across Security Services, Medical Services, BPO / ICT, insurance and fire protection.
Against that backdrop, the numbers point to a market that is paying up. The stock trades on a P/E multiple that is meaningfully higher than both its immediate Commercial Services industry average of 12.6x and the broader peer group at 16.9x, which suggests investors are attaching a clear premium to SECOM's earnings profile. At the same time, the estimated fair P/E ratio of 25.2x sits slightly above the current 24.3x, a level the market could move towards if sentiment or earnings expectations stay aligned with that fair value framework.
Explore the SWS fair ratio for SECOM.
Result: Price-to-Earnings of 24.3x (OVERVALUED)
Still, richer expectations around SECOM could face pressure if security demand softens or if competition forces tighter pricing across key service lines.
Find out about the key risks to this SECOM narrative.
Another View on SECOM: Cash Flows Tell a Softer Story
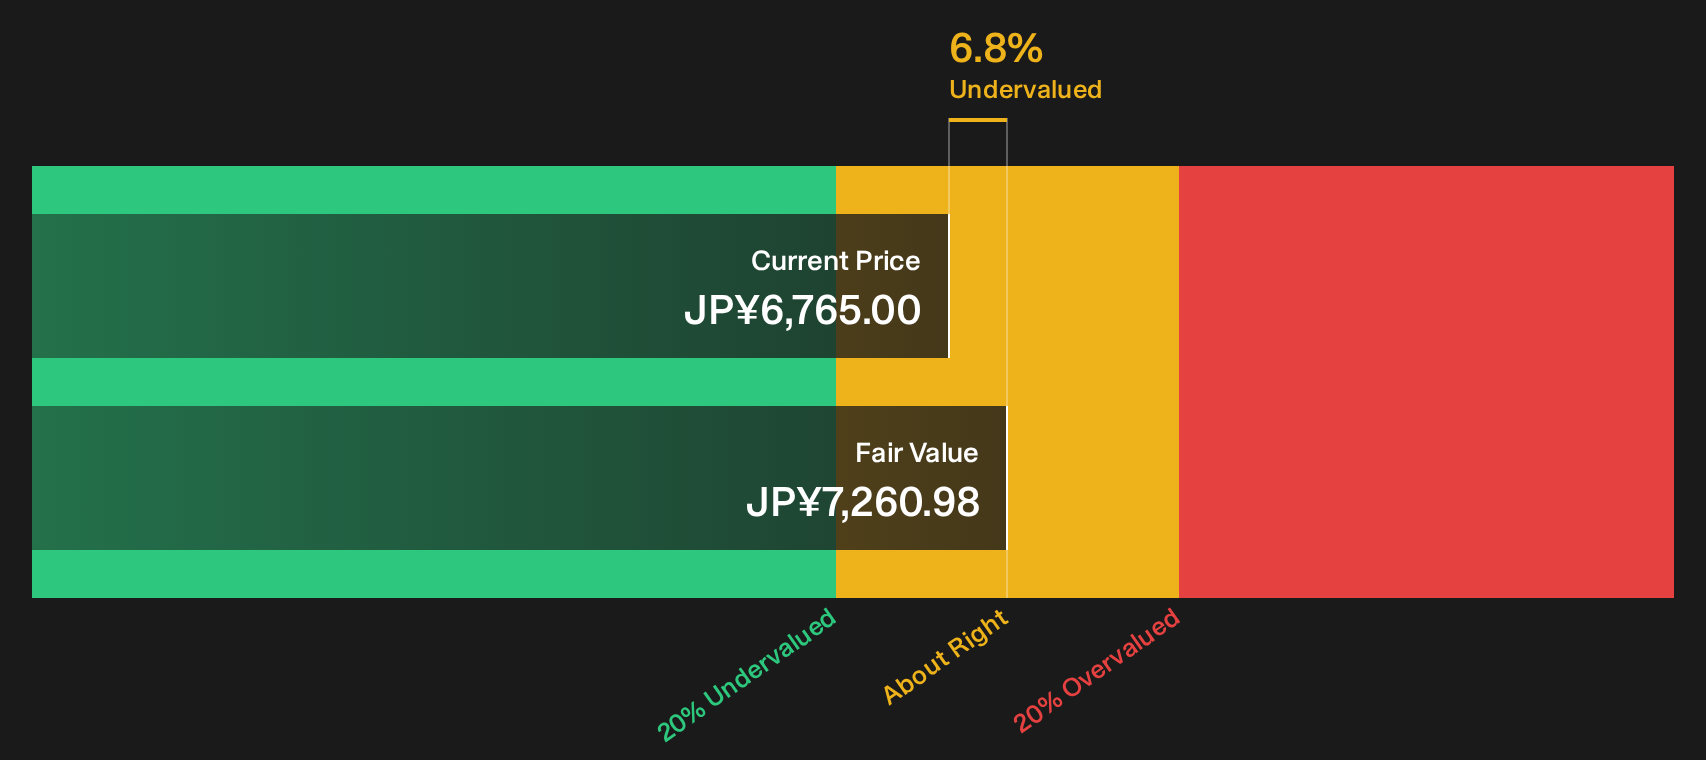
The P/E lens presents SECOM as expensive relative to peers, yet the SWS DCF model suggests something different. At a share price of ¥6,765, the stock trades about 6.8% below an estimated future cash flow value of roughly ¥7,261. That points to a modest undervaluation rather than an outright premium.
For investors comparing tools, this creates a gap to weigh. One question is whether earnings multiples are overreacting to recent share price strength, or whether the cash flow model is giving too much credit for stability and gradual profit growth.
To understand how that cash flow estimate is built and to evaluate the inputs against your own expectations, review the Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SECOM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 23 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mixed signals on SECOM tilt more positive than they first appear? Act while the data is fresh and weigh the upside and trade offs yourself, then round out your view by checking the 3 key rewards
Looking for more SECOM sized investment ideas?
Do not stop with SECOM. Put the same discipline to work across other opportunities so your watchlist keeps refreshing instead of going stale.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters for fundamentals which can support pressure without relying on hype.
- Hunt for mispriced quality using the 72 high quality undiscovered gems and see which under-followed businesses line up with your risk and return preferences.
- Explore income-focused ideas through a yield conscious 29 dividend fortresses built to highlight companies combining higher payouts with robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com