


AppLovin (APP) is back in focus after reporting third quarter results that showed sharply higher sales and net income year on year, along with fresh fourth quarter revenue guidance and an expanded share buyback program.
AppLovin’s share price reaction has been sharp, with a 7 day share price return of 61.1% and a 30 day share price return of 42.8% after the earnings beat, fourth quarter guidance and larger buyback. However, the year to date share price return is still down 36.0% and the 1 year total shareholder return is down 33.5%, while the 3 year total shareholder return is very large at more than 8x and the 5 year total shareholder return is also very strong. Together, these figures point to long term momentum that has recently cooled, then quickly reaccelerated.
Compare AppLovin’s sharp swing in sentiment with a curated set of other fast moving ad tech and AI driven platforms by scanning our 42 profitable AI stocks that aren't just burning cash that already pair growth with real earnings.
After a 61% weekly jump and new share repurchase capacity supporting it, AppLovin now faces a harder question. Does the current price still leave enough potential upside to justify the risk you are taking from here?
Most Popular Narrative: 22% Undervalued
AppLovin last closed at $395.51, while the leading narrative pegs fair value at $507. According to RedCandleRx, an investor in the Simply Wall St Community who wrote that narrative, the gap comes from how the market reads the business model and its risks.
AppLovin is one of the best operators in the market it already dominates. It just had its largest legal overhang removed, its most recent stumble was a release-schedule problem rather than a demand problem, and it is entering a market several times larger than the one it currently leads. The stock is at 25.3 times trailing earnings.
See why 38 investors see AppLovin as 22% undervalued.
Result: Fair Value of $507 (UNDERVALUED)
Still, AppLovin’s story can break if fresh regulatory scrutiny hits its data advantage, or if compute and R&D costs start to squeeze those high margins.
Find out about the key risks to this AppLovin narrative.
Another View: AppLovin Through The P/E Lens
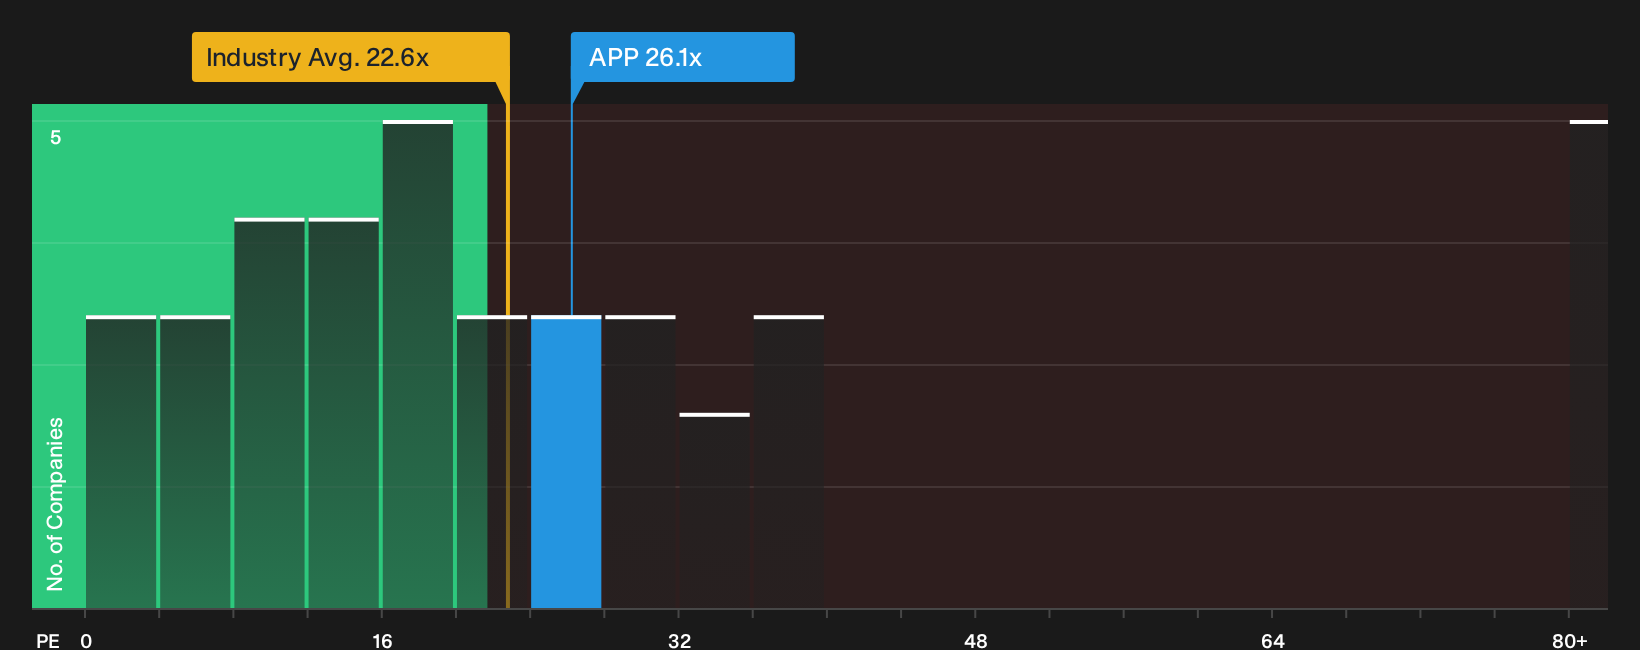
On simple P/E math, AppLovin looks less clear cut than the community fair value of $507 suggests. The stock trades on 26.1x earnings, above the US Media sector on 22.6x, yet below peers that sit around 41.4x, while the fair ratio points to 33.1x as a level the market could move toward.
If the share price tracks closer to that 33.1x fair ratio over time, investors are effectively choosing between paying up for quality today or waiting and risking that the market closes the gap on its own terms. Which side of that trade-off feels more comfortable to you from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinion on AppLovin is clearly split, and that is exactly when fresh data matters most. Move quickly, check the key risks and rewards, and then weigh the 3 key rewards and 1 important warning sign.
Looking for more AppLovin-sized investment ideas?
If you only stop at AppLovin, you may miss opportunities sitting right in front of you. Use screened shortlists to quickly focus on ideas that actually fit your plan.
- Target resilient businesses that aim to pair strong balance sheets with solid fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a measured price by scanning the 35 high quality undervalued stocks before the market re-prices them.
- Prioritise sleep-at-night holdings that aim to keep risk contained by working through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com