


Krystal Biotech (KRYS) is back in focus after third quarter earnings on November 2 showed continued profitability, along with a new US$400 million share repurchase authorization with no expiration date.
Despite the new authorization, Krystal Biotech’s 30 day share price return is down 7.6%, and the 90 day share price return is down 7.9%, even as renewed buyback plans and recent earnings keep investor attention on where the story goes next.
Capitalize on the renewed focus around Krystal Biotech by scanning a curated set of resilient healthcare names with strong balance sheets in our list of solid balance sheet and fundamentals (24 results).Krystal Biotech now trades well below both analyst targets and one intrinsic value estimate, even after the buyback news. Where does a reasonable fair value range land between those reference points?
Most Popular Narrative: 22% Undervalued
On the analyst consensus Narrative on Simply Wall St, Krystal Biotech’s fair value of $392.11 sits well above the latest $306.50 close. This frames the current pullback against an upbeat long term view built on forecasts and cash flow assumptions.
Advancement of Krystal Biotech toward a multiproduct genetic medicines company through late stage programs such as KB803, KB801, KB407, KB111, KB707 and KB408, supported by HSV 1 platform technology designations, could broaden the revenue base beyond Vyjuvek and spread fixed costs across multiple products.
See why 35 investors see Krystal Biotech as 22% undervalued.
Result: Fair Value of $392.11 (UNDERVALUED)
Still, the Krystal Biotech story can strain if European pricing pressure trims Vyjuvek profitability, or if higher HSV 1 platform spending outpaces new product contribution.
Find out about the key risks to this Krystal Biotech narrative.
Another View: Krystal Biotech Through The P/E Lens
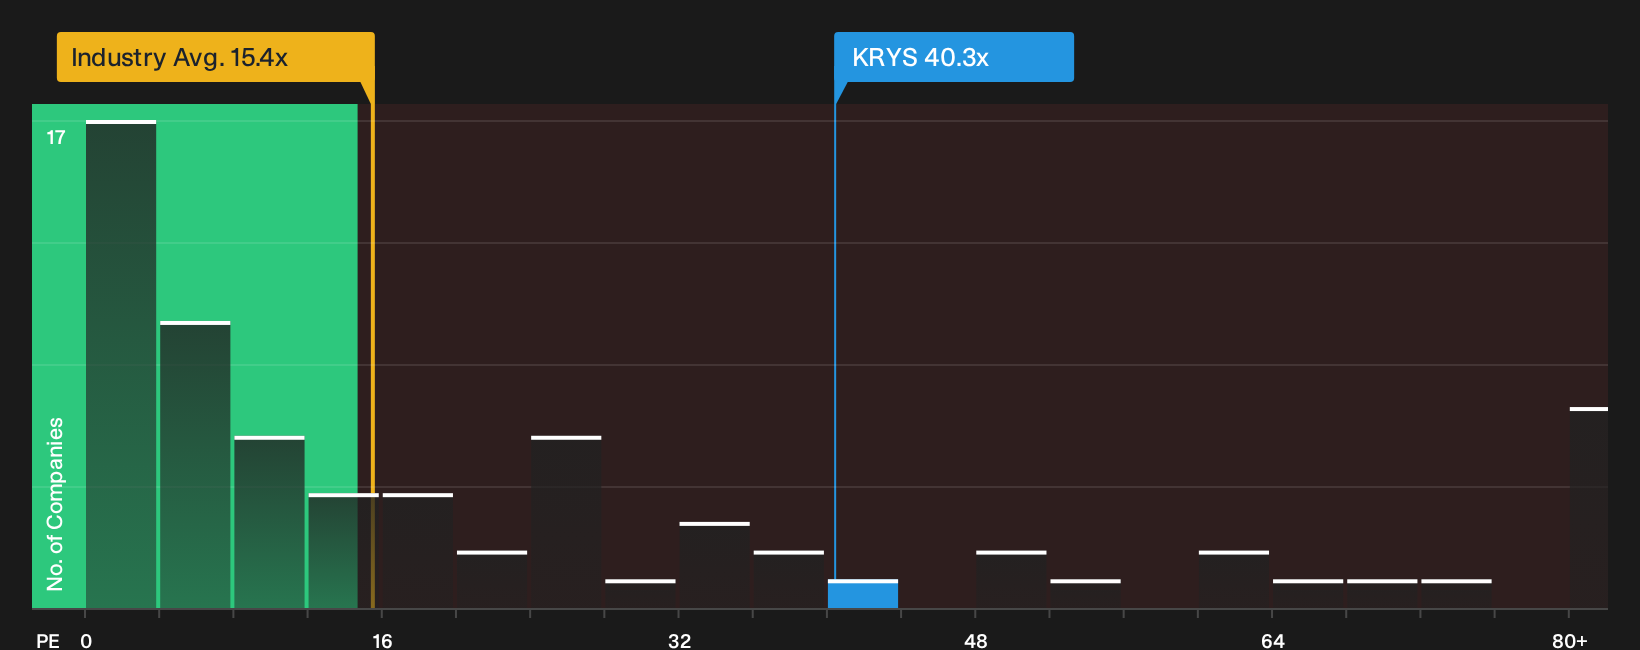
Krystal Biotech may look cheap on analyst fair value models, yet the current P/E of 40.3x tells a different story. The ratio sits well above the US Biotechs industry at 16x and also above a 32.5x fair ratio that the market could move toward. That gap points to meaningful valuation risk. How comfortable are you paying a premium multiple for a business already priced above both its sector and its own fair ratio target?
To dig into what this pricing gap might signal for Krystal Biotech, and how the fair ratio could matter if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Krystal Biotech can pull you in both directions. Move quickly, review the data, and weigh both sides for yourself with 4 key rewards and 1 important warning sign
Looking for more Krystal Biotech sized opportunities?
If Krystal Biotech has your attention, do not stop here. Broader idea hunting gives you more ways to balance risk, quality, and potential payoff.
- Target quality at a discount by scanning a curated pool of strong fundamentals with the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 5 dividend fortresses that combine yield with resilience.
- Protect your downside by filtering for durable businesses with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com