


Tate & Lyle has logged a strong year so far, and the share price gain puts fresh attention on whether the current valuation can be explained by its earnings power. With the stock now well above where it started 2026, the question is how much of that move is backed by the underlying profit profile.
- The share price is up 52.6% year to date, which raises the stakes on whether recent enthusiasm lines up with the earnings that Tate & Lyle is actually producing.
- The group relies heavily on converting its food ingredients and solutions business into steady profit, so any shift in margins or cash conversion can quickly change how supportive today's earnings base is for the current share price.
- The analysts covering Tate & Lyle have run their own numbers. See what analysts think Tate & Lyle's shares could be worth.
The issue now is whether Tate & Lyle's current market value is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings question beyond Tate & Lyle, scan the wider market using the 16 high quality undervalued stocks
Does Tate & Lyle Look Pricey on Earnings?
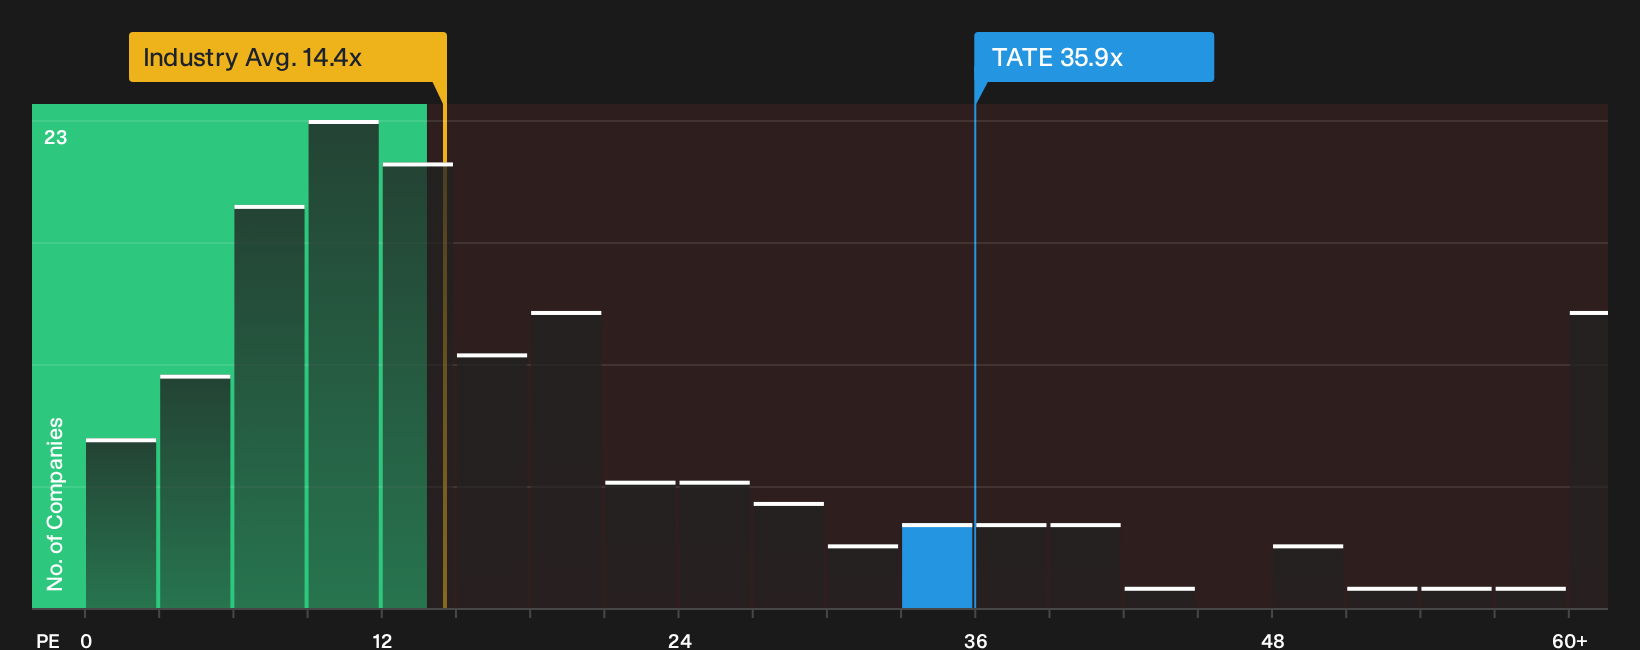
The P/E ratio suits Tate & Lyle because earnings remain the core lens most investors use for an ingredients producer with established product lines. On that yardstick, the shares trade on roughly 35.9x earnings, which is far richer than the Food industry average of about 14.6x and also well above the wider peer group on roughly 19.2x.
The Fair Ratio model, which blends the company's growth outlook, profitability profile, size and risk, points to a lower multiple than the one the market is currently paying. On this framework Tate & Lyle screens as overvalued on earnings. For anyone considering the stock, the real question is whether the quality and durability of those profits justify such a premium over both sector norms and the more tailored benchmark the model suggests. Explore the numbers behind Tate & Lyle's P/E valuation.
The Tate & Lyle Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off and explain which combinations of Tate & Lyle's future growth, margins and earnings would need to occur for the stock to deserve a meaningfully higher or lower price than today. All of this is set out on Simply Wall St's Community page. Each narrative links its number to a specific view on how Tate & Lyle's prospects and risks could change, which you can revisit as fresh information emerges.
Bulls see Tate & Lyle turning integration and efficiency into a stronger earnings engine, while bears think most of that story is already priced in.
Bull case: 9% undervalued
The bullish analyst Narrative on Simply Wall St leans on hard synergy targets and productivity gains to argue there is more upside in Tate & Lyle.
"The productivity programme has already produced $144 million of savings over 3 years and the 5 year target was raised from $150 million to $200 million by the end of the 2028 financial year…"
Discover why this Narrative puts Tate & Lyle at 9% undervalued.
Bear case: roughly fairly valued
The analyst consensus Narrative on Simply Wall St argues the current Tate & Lyle share price already bakes in successful integration and cost delivery.
"The current valuation and the recommended Ingredion all-cash offer at about 8.8x FY2026 adjusted EBITDA together imply that the share price already reflects a fair value for Tate & Lyle…"
Explore why this Narrative puts Tate & Lyle at roughly fairly valued.
Before you lean on Tate & Lyle’s valuation, there is one more piece to check
Tate & Lyle’s pricing story only goes so far without weighing the specific risk warnings our research has flagged in the background of this business. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com