


Par Pacific Holdings (PARR) just paired a strong third quarter earnings release with the completion of a share repurchase tranche, giving investors fresh numbers on both profitability and capital returns.
Despite the upbeat third quarter print and ongoing buybacks, Par Pacific Holdings' recent share price has cooled, with the stock down 18.13% on a 1 month share price return and 13.81% over 3 months. However, the year to date share price return of 87.16% and 5 year total shareholder return of 328.10% show that longer term momentum remains strong.
Scan for other value stories that may be moving under the radar by comparing Par Pacific Holdings with our hand picked 35 high quality undervalued stocks.
Par Pacific Holdings now trades well below the average analyst price target despite a strong run of reported earnings and fresh buybacks. Is that gap a genuine opportunity or a warning the market is pricing in risks?
Most Popular Narrative: 28% Undervalued
Par Pacific Holdings closed at $67.04, while the analyst consensus Narrative on Simply Wall St anchors fair value at $93.29. This implies a sizeable discount that the narrative treats as mispricing rather than just short term noise.
The numbers and recent share repurchases imply the market is valuing Par Pacific as fairly valued with a bearish tilt. Current earnings, balance sheet strength, and finite tax benefits appear to be largely reflected in the share price.
See why 21 investors see Par Pacific Holdings as 28% undervalued.
Result: Fair Value of $93.29 (UNDERVALUED)
Still, Par Pacific Holdings carries clear pressure points, including older refinery assets that can face costly outages and a shrinking US$700 million tax shield that could lift future cash taxes.
Find out about the key risks to this Par Pacific Holdings narrative.
Another View: Par Pacific Holdings Through The Cash Flow Lens
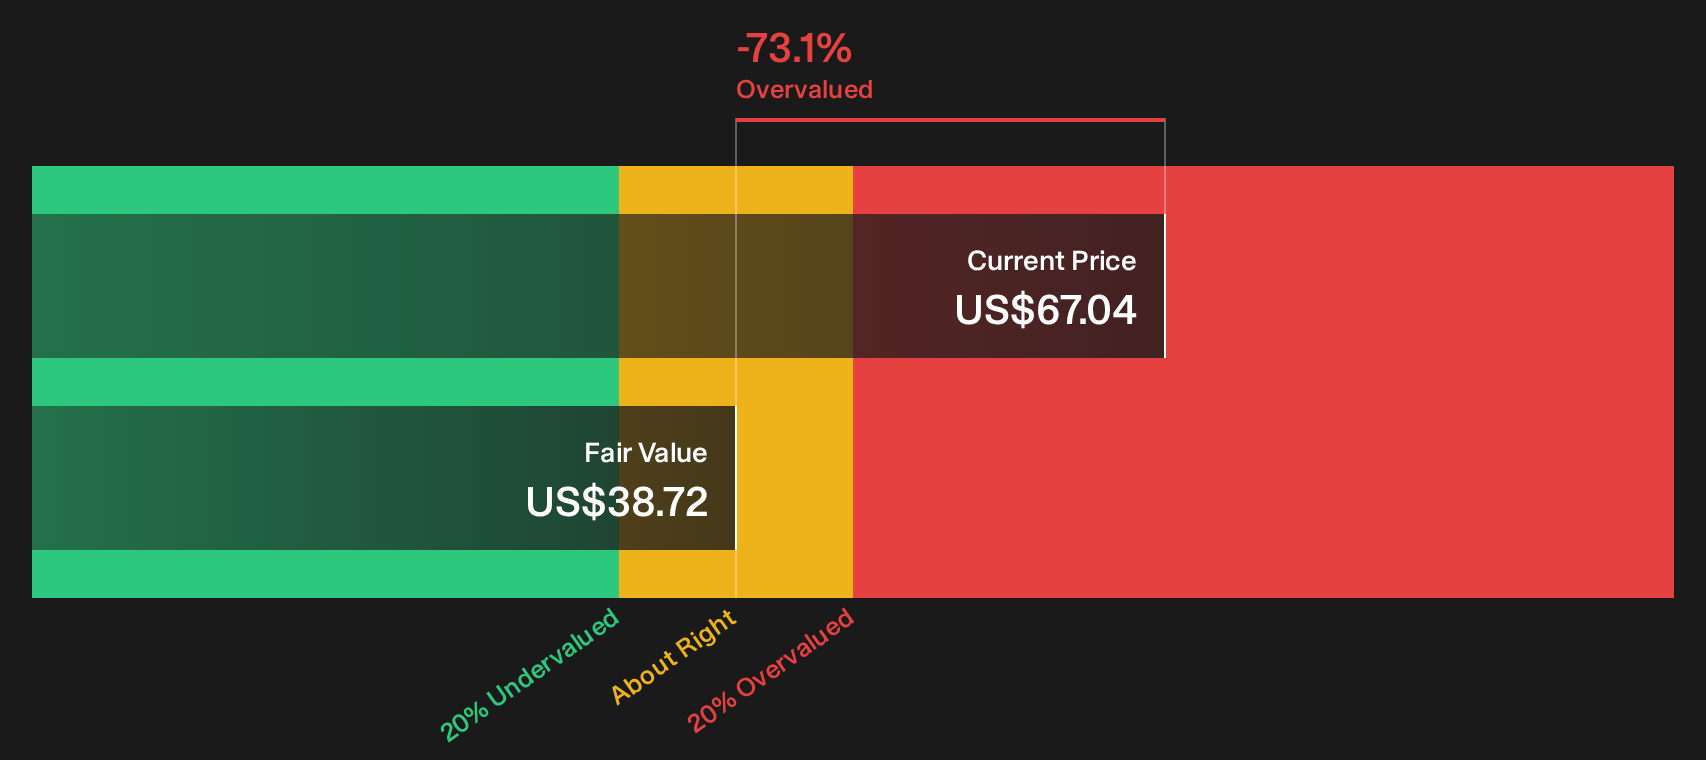
Those analyst targets paint Par Pacific Holdings as undervalued, yet the Simply Wall St DCF model points in the opposite direction. On that framework, the shares trade around $67.04 against an estimated future cash flow value of $38.72, which screens as overvalued on cash flows and raises the question of which signal investors should trust more: earnings multiples or cash generation.
To understand how such different inputs can lead to such a different conclusion, and what that gap might mean for downside or upside risk, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Par Pacific Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on value and risk make Par Pacific Holdings a stock investors will want to assess on their own terms, using the same data that is driving current debate and weighing both potential upside and downside before deciding how it fits their approach with 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Par Pacific Holdings?
If Par Pacific Holdings has sharpened your focus on value and risk, do not stop here. Broader opportunity often sits just outside the stocks already on your radar.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) to see which companies line up with a capital preservation mindset.
- Hunt for potential mispricing by reviewing the 35 high quality undervalued stocks that combine quality metrics with valuations that may not fully reflect underlying fundamentals.
- Build a stream of potential cash returns by filtering for the 5 dividend fortresses that balance income potential with business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com