


IDEX (IEX) just posted third quarter and nine month results, giving investors fresh numbers on sales, earnings and profitability to reassess what they are paying for the stock today.
The earnings release appears to have nudged sentiment rather than flipped it, with the latest move leaving IDEX at a share price of $236.90 and contributing to a 32.30% year-to-date share price return. The 1-year total shareholder return of 41.68% points to momentum that has been building over a longer stretch.
Look beyond IDEX's latest earnings move and compare other engineering-focused plays with solid financial profiles using our curated list of list of solid balance sheet and fundamentals (24 results)
IDEX now has solid recent earnings and a strong long term return profile baked into the story. The real tension is whether that quality is already fully reflected in today’s share price of $236.90.
Most Popular Narrative: 10% Undervalued
On Simply Wall St, the analyst consensus Narrative currently pegs IDEX's fair value at $262.93, which sits above the last close of $236.90. This frames today’s debate around whether the recent strength still leaves room based on those cash flow and earnings forecasts.
Record company backlog of more than US$1b with 28% organic order growth in Q2 2026 and multi quarter visibility in HST and parts of FMT, including future dated data center bookings that extend into 2027, provides a pipeline that can support revenue and cash flow growth beyond what is already recognised.
See why 9 investors see IDEX as 10% undervalued.
Result: Fair Value of $262.93 (UNDERVALUED)
Still, the IDEX narrative could be knocked off course if policy or geopolitical shocks hit orders, or if legacy segments continue to pressure organic growth and returns.
Find out about the key risks to this IDEX narrative.
Another View: IDEX Through a P/E Lens
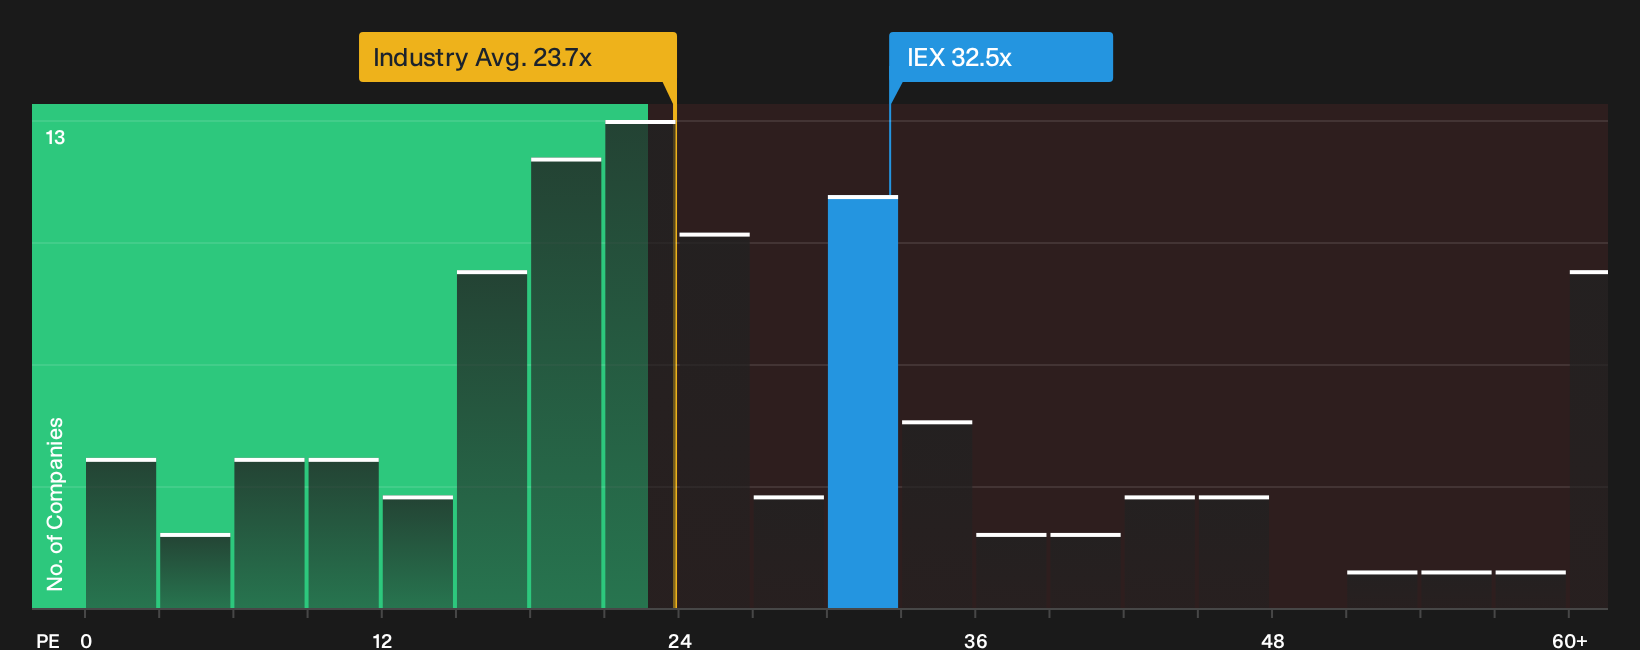
The DCF work suggests IDEX is trading about 17.1% below an estimated future cash flow value of $285.90, which points to upside based on those long range inputs. The P/E picture looks very different. At 32.5x earnings, the stock trades above the US Machinery industry on 24.1x, peers on 24.8x, and a fair ratio of 23.9x, which signals investors are already paying a premium that could compress if expectations ease. Does that premium feel like a margin of safety or a valuation risk to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Debates like this around IDEX only matter if you put numbers in context yourself and act before sentiment swings again. To see how those positives stack up in the data, review the 2 key rewards.
Looking for more investment ideas beyond IDEX?
If you stop at IDEX, you risk missing other setups that fit your style, so widen the lens and pressure test your next move with fresh ideas.
- Hunt for mispriced quality by scanning a tighter pool of strong fundamentals through the 35 high quality undervalued stocks.
- Lock in steadier income possibilities by filtering for higher yielding payers using the 5 dividend fortresses.
- Reduce portfolio stress by focusing on sturdier businesses screened via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com