


Barclays has quietly turned in a powerful share price recovery over the past few years, which puts a spotlight on whether the current valuation is properly anchored to its earnings power. With fresh headlines ranging from a new Saudi office to legal scrutiny over mortgage exposure, the stock now invites a closer look at how much earnings strength investors are effectively paying for.
- Over the past 3 years, Barclays has delivered a share price return of about 241.5%, which puts real weight on whether those gains are aligned with the underlying earnings profile.
- Recent news on a Saudi investment banking licence, AI infrastructure debt protection plans and a probe into mortgage exposure can all influence how investors think about the bank’s future fee income, funding costs and potential earnings volatility.
- Your read on Barclays is one view; the desks covering it have another. See what analysts think Barclays's shares could be worth.
The issue now is whether Barclays current share price is adequately supported by the earnings it is generating today and is expected to produce in the future.
If you want a clear comparison on this theme of earnings power and risk, compare Barclays with companies in the 5 resilient stocks with low risk scores.
Is Barclays Fairly Priced on Earnings?
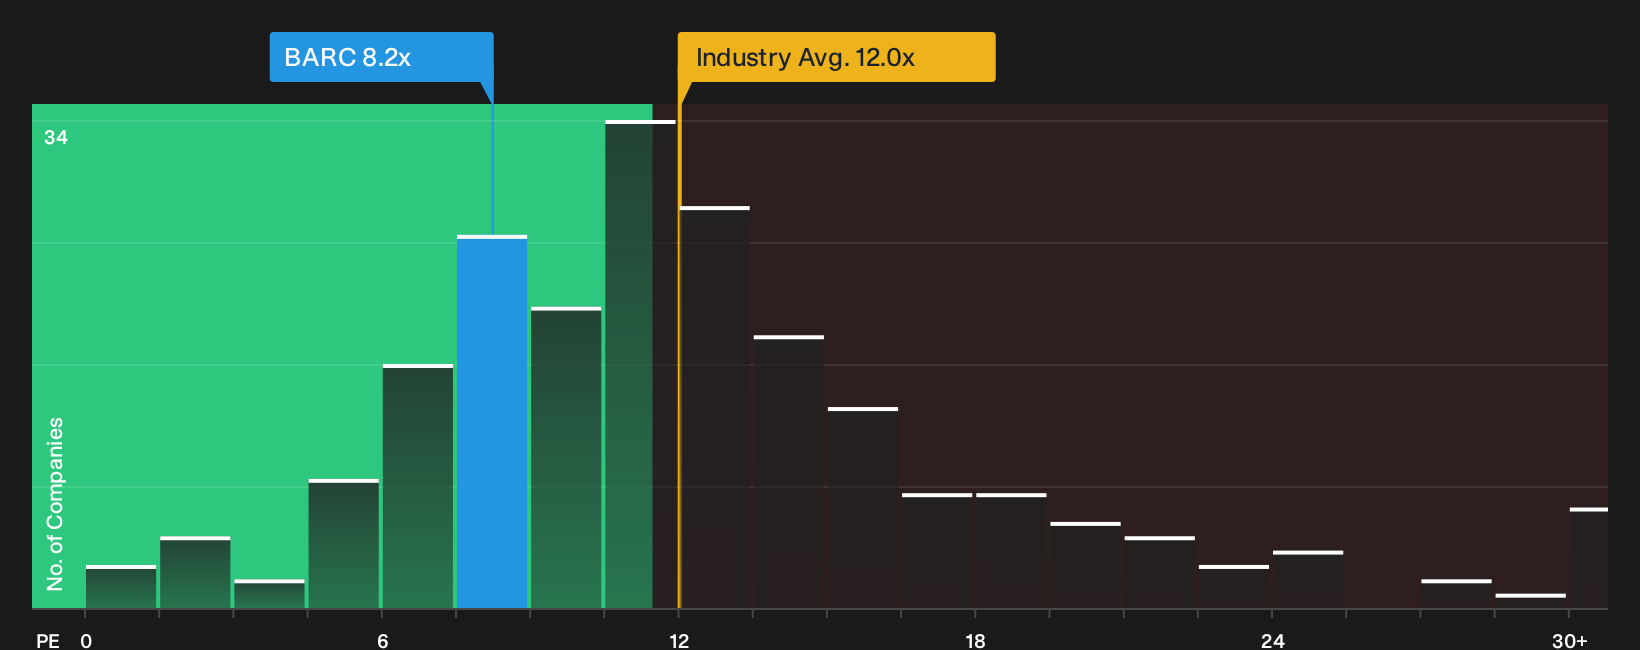
P/E is a useful yardstick for Barclays because earnings remain the primary driver of value for a large, mature bank. On this measure, the stock trades on a P/E of 8.2x, against an industry average of about 11.0x and a peer group closer to 10.3x. That puts Barclays at a discount to both its sector and similar banks, even as the shares have already re-rated in recent years.
Because the Fair Ratio indicates where the P/E might land given Barclays mix of profitability, risk and size, the current 8.2x level lines up closely with that tailored benchmark rather than flashing a clear bargain or a clear premium. Despite the fresh Saudi office licence and attention on its investment banking exposure, the multiple still prices Barclays below the wider banking sector on earnings. For investors, the key question is whether recent headlines on mortgage exposure, AI infrastructure credit protection and tax changes meaningfully alter the earnings profile that this valuation is built on. Explore the numbers behind Barclays's P/E valuation.
The Barclays Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Barclays pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the bank to look meaningfully cheap or expensive versus today’s price on the Community page. Instead of giving a single valuation number, they describe the future that number rests on so you can watch how Barclays' actual progress tracks against it.
One of the top community narratives on Barclays: 23% undervalued
This view on Barclays' valuation comes from Robbo, a Simply Wall St Community investor who wrote the Narrative.
"Combined with a price-to-earnings ratio of around 10, the price-to-book ratio suggests a puzzling lack of confidence in Barclays' future profitability and earnings durability..."
Discover why this Narrative puts Barclays at 23% undervalued.
Barclays valuation leaves one big thing unresolved
All of this still leaves one gap for you to check: how professional forecasters currently see Barclays a few years from now compared with the price you see on screen today. Explore where analysts expect Barclays to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com