


Evercore ISI’s senior analyst Peter Levine says Akamai Technologies (AKAM) investors will have to wait longer for the next meaningful catalyst.
Levine downgraded the cybersecurity and cloud infrastructure firm this morning to “In Line” and reduced his price target to $90, indicating a lack of meaningful upside in the near term.
His bearish call is particularly significant given Akamai stock is already down roughly 45% versus its year-to-date high.
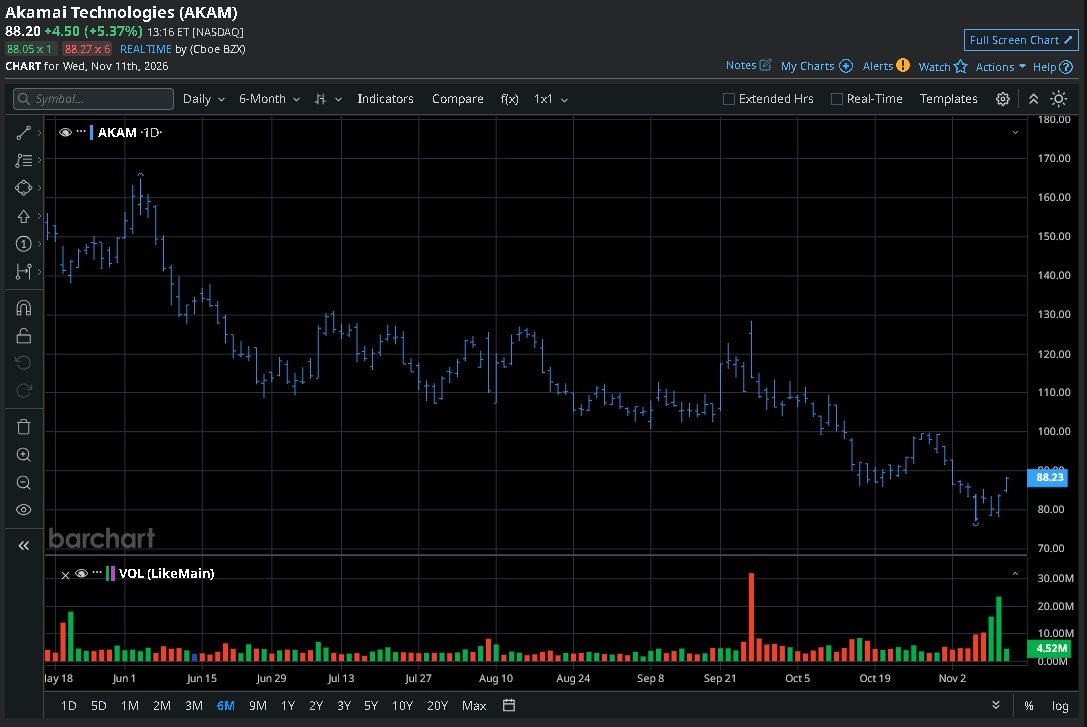
Why Did Evercore ISI Turn Bearish on Akamai Stock?
Levine’s downgrade arrives just days after Akamai unveiled a $2.2 billion convertible debt offering intended to support its Cloud Infrastructure Services (CIS) expansion.
According to him, the structure of that financing deal creates fresh questions for investors.
In particular, the analyst highlighted concerns surrounding shareholder dilution, future refinancing requirements, and the company’s broader funding strategy.
In his report, the Evercore analyst dubbed it a “defensive financing solution” because of its short-duration component.
Simply put, the debt offering could make shareholders question whether Akamai Technologies has sufficient access to attractive long-term financing alternatives at a time when it’s investing heavily in cloud infrastructure.
What Else Makes AKAM Shares Unattractive?
The timing of Akamai’s cloud infrastructure buildout and the impact it will have on “profitability” make up the second pillar of Levine’s bearish stance.
AKAM shares, he’s convinced, will remain largely range-bound until operating margins begin to stabilize and investors gain greater visibility into free cash flow generation.
And the analyst warned that meaningful improvement on those fronts may not arrive until the back half of 2027, when cloud-related investments will begin to mature and revenue contributions from high-growth opportunities – including the firm’s partnership-driven AI initiatives – become more apparent.
Note that Akamai Technologies has a history of gaining just 0.51% on average in December, a seasonal pattern that further dulls its appeal for the near term.
Wall Street Remains Bullish on Akamai Technologies
Other Wall Street analysts haven’t thrown in the towel on AKAM stock, though.
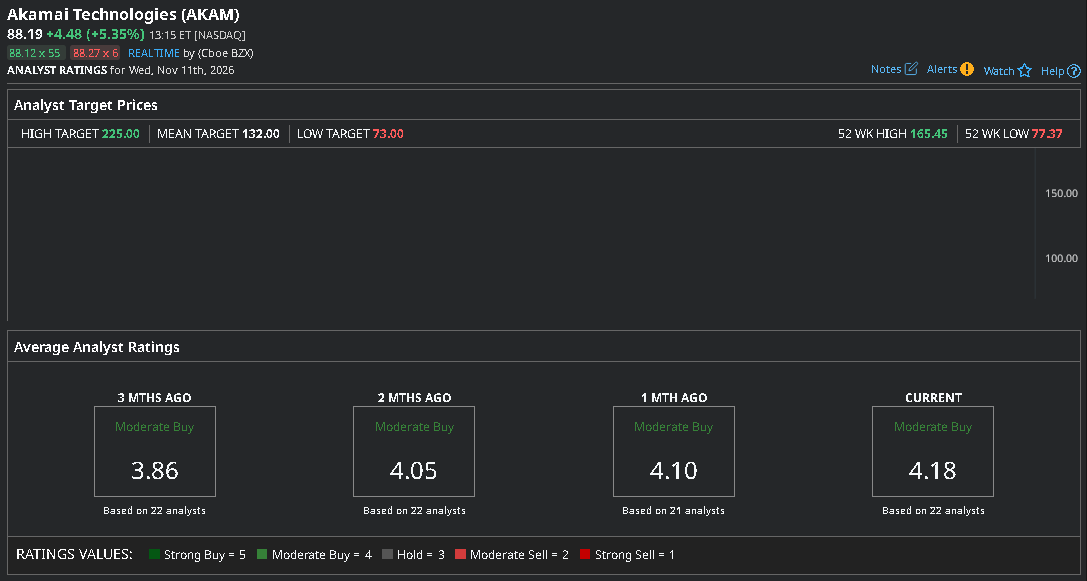
According to Barchart, the consensus rating on Akamai Technologies remains at “Moderate Buy” – with the mean price target of about $132 indicating potential upside of a whopping 45% from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.