


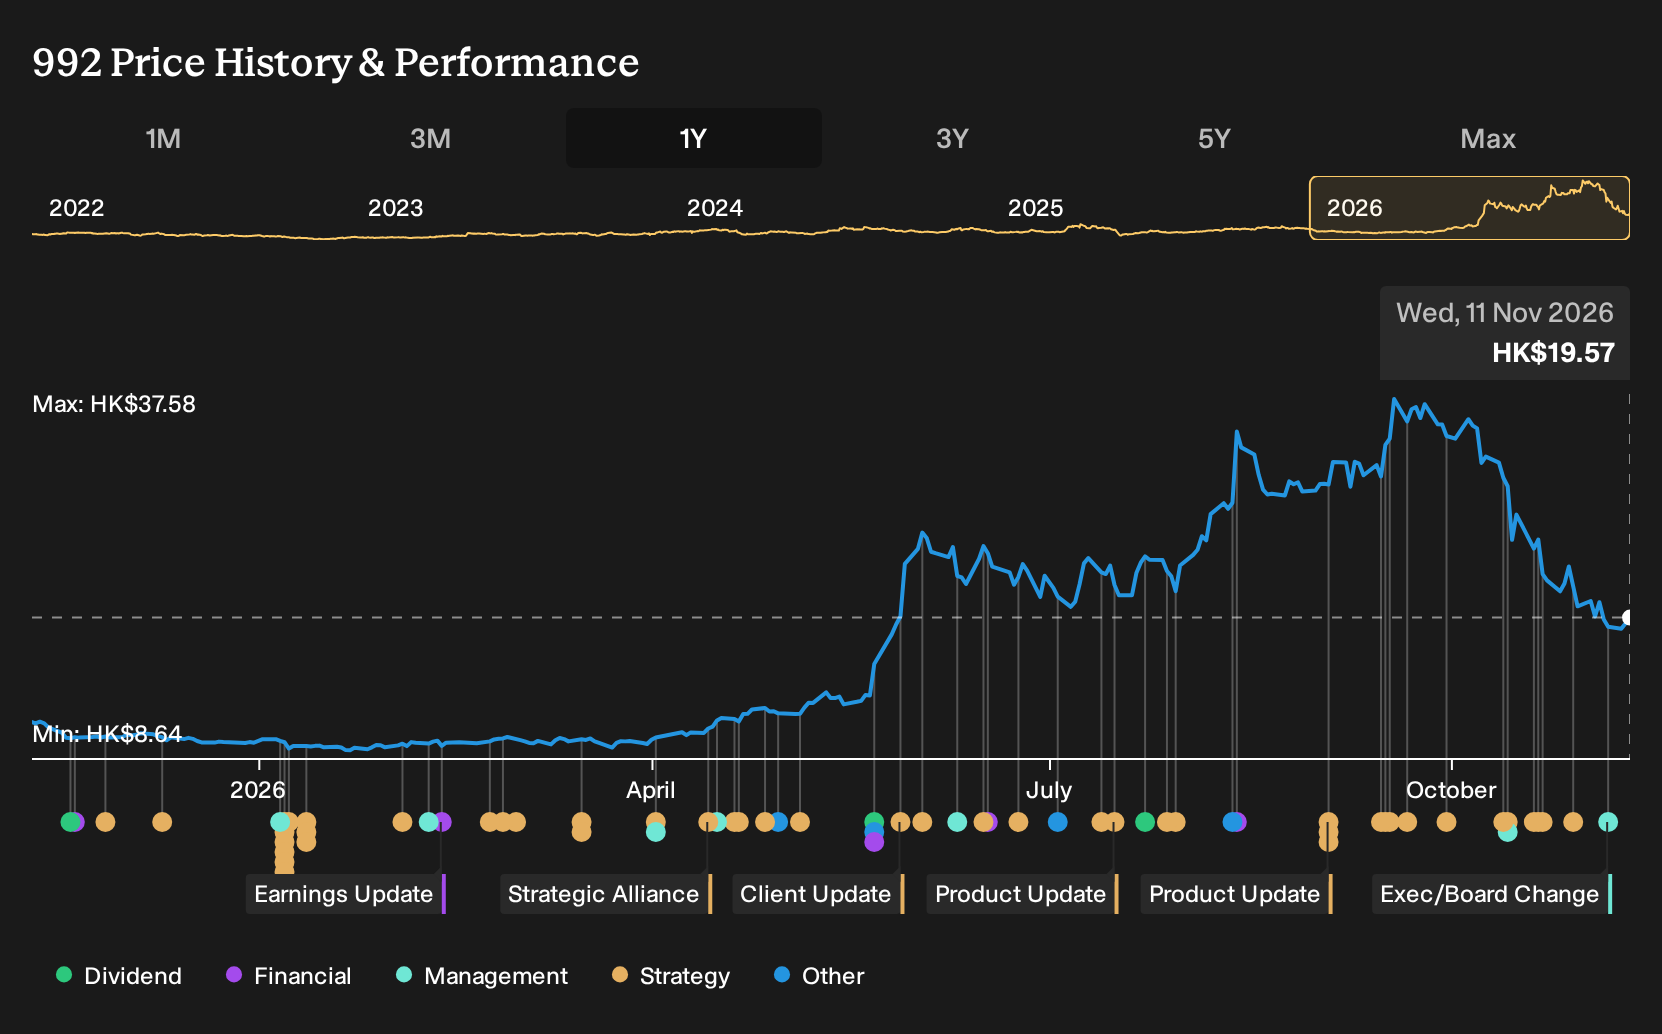
For Lenovo Group shareholders, the return over the past year was 82.1%, including dividends. That kind of move forces a simple question. If you had been weighing Lenovo on 11 November 2025, with bulls pointing to next gen AI servers and services and bears stressing cloud migration and US China frictions, what would you have done if you had to choose between a maturing PC champion and a higher risk AI infrastructure story?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Lenovo Group. See which of 53 AI infrastructure stocks may still merit a closer look.
The Two Lenovo Narratives Investors Faced
The shares cost HK$10.85 at the start of the period, and Lenovo Group sat between two clear storylines about what might come next.
On the optimistic side, one narrative saw fair value at HK$13.42, or 24% above the start price. This view was built on revenue growing 6.9% a year and profit margins edging to 2.4% over three years, with a future P/E assumption of 12.5x.
The cautious view put fair value at HK$10.03, or 8% below the start price. It relied on a 4.9% revenue growth assumption, flat 2.0% margins, and a higher future P/E of 13.2x as a key risk.
What The Lenovo Group Results Put To The Test
Lenovo’s Q1 2027 update showed revenue of US$26,942.8m versus US$18,829.9m a year earlier, which leaned toward the optimistic growth story. The setback came in profitability. Net income moved from a US$505.3m profit to a US$608.6m loss and net margin shifted from 2.7% to -2.3%. The evidence cut both ways.
The original Lenovo Group call really hinged on margins, not just sales. For a different stock, you would check whether any growth pitch also comes with clear progress in net margin and absolute profit, not just higher revenue or a headline about AI.
What Lenovo's 82% Run Now Asks You To Believe
Lenovo Group trades at HK$19.57 after rising 82.1% over the past year, and the current Narrative’s Fair Value still sits above that level rather than below it.
According to kapirey, a Simply Wall St Community investor who wrote the Narrative, the market price does not yet fully credit Lenovo’s attempt to become an AI infrastructure “orchestrator” backed by large chip and model partners.
"Lenovo is evolving into a full-stack AI infrastructure and devices player, supported not only by internal execution but by deep strategic alliances with global AI leaders (notably NVIDIA and AMD, and a multi-model ecosystem approach). These partnerships materially de-risk Lenovo’s AI transition by: Providing best-in-class chips, software, and AI ecosystems; accelerating time-to-market in infrastructure and enterprise AI; and positioning Lenovo as an “orchestrator” rather than a model developer. 👉 Net impact: Lenovo’s AI exposure is not speculative, it is embedded in global AI value chains, strengthening the long-term investment case."
One Narrative disagrees with today's price. → See where this Narrative says Lenovo Group should trade
Where Lenovo’s AI Needs Point Next
Lenovo is chasing bigger AI workloads. Those workloads create a different kind of bottleneck for someone else to solve.
Every extra model your servers run has to store, move, and recall much more data. That pushes demand toward storage built specifically for heavy cloud and AI tasks.
One specialist is focused on flash drives tuned for data centers and edge devices. Its products aim to handle dense data, tighter energy use, and tougher reliability requirements.
If that effort works, what used to look like generic memory could behave more like core AI infrastructure in its own right.
That argument has a Narrative and a number behind it. → See the company one Narrative values 145% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com