


Minerals 260 (ASX:MI6) has just wrapped up a sizeable A$250.0m follow on equity offering at A$0.88 per share, a move that reshapes its capital base and sharpens investor focus.
That capital raise lands on a stock that has already been moving sharply, with a 7 day share price return of 21.38% and a year to date share price gain of 104.65% at A$0.88. The 1 year total shareholder return of 198.31% signals strong momentum, and recent trading now links more directly to Minerals 260’s higher P/E premium and investor expectations around future earnings power.
Scan how Minerals 260 compares to other fast moving resource plays by reviewing the hand picked 33 best rare earth metal stocks now catching investors' attention after fresh capital raises and sharp price moves.
Minerals 260 now trades roughly 41% below the average analyst price target yet screens at a low value score of 1. Is that a cautious market misread after the raise, or a fair warning signal on valuation risk?
Price-to-Earnings of 27x: Is it justified?
Minerals 260 now trades on a P/E of 27x at A$0.88, a level that sits well above several reference points and leaves little ambiguity that the equity is priced at a premium.
The P/E ratio compares what investors pay today for each dollar of current earnings. For a resource explorer that has only recently become profitable, a higher P/E often reflects investors placing weight on future profit potential rather than current income.
Against that backdrop, Minerals 260 carries a 27x P/E while the Australian Metals and Mining industry sits at 11.3x and the peer group average sits at 23.6x. The stock also trades above an estimated fair P/E of 18.3x. This points to a valuation level the market could move towards if expectations around future earnings ease.
Explore the SWS fair ratio for Minerals 260.
Result: Price-to-Earnings of 27x (OVERVALUED)
Still, the zero revenue base and Minerals 260’s high P/E ratio leave little margin for disappointment if exploration results or future earnings trajectories fall short of expectations.
Find out about the key risks to this Minerals 260 narrative.
Another view using our DCF model
While the 27x P/E suggests Minerals 260 is richly priced, the SWS DCF model presents a different perspective. At A$0.88, the share price sits well above an estimated future cash flow value of A$0.09, which implies a very full valuation. How comfortable are you leaning on forecasts to bridge that gap?
Look into how the SWS DCF model arrives at its fair value.
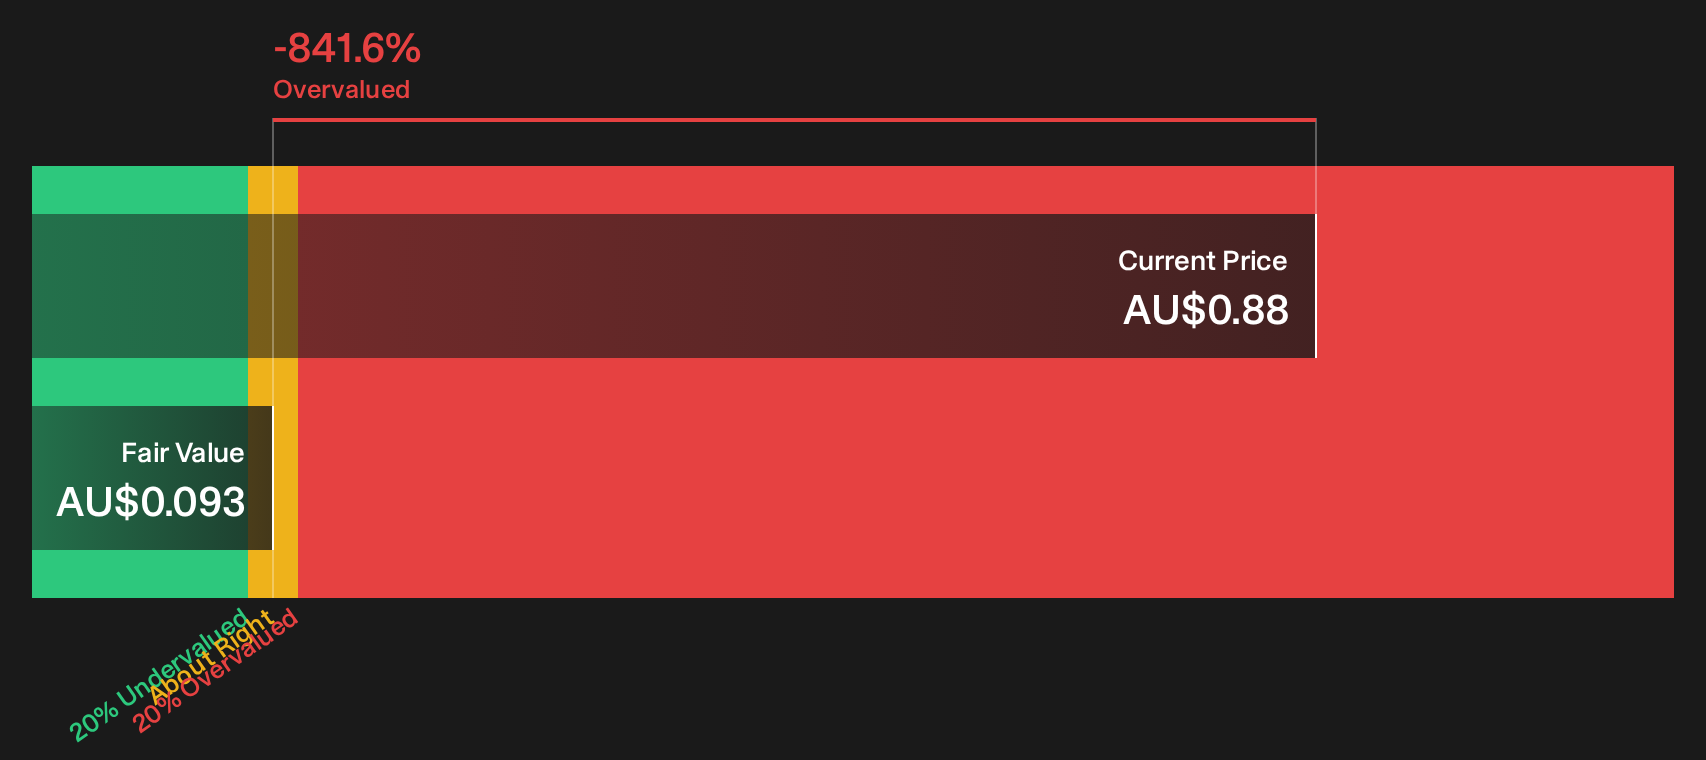
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Minerals 260 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the upbeat share price action and the richer valuation signals around Minerals 260 after this raise is reasonable. Act quickly, examine the same data points in detail, and weigh both the upside narrative and the caution flags using our breakdown of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Minerals 260?
If Minerals 260 has sharpened your interest, do not stop there. Use targeted screeners to quickly spot fresh opportunities that fit your risk and return preferences.
- Target potential mispricing by scanning a focused 3 high quality undervalued stocks that highlights companies combining quality metrics with compressed valuation multiples.
- Build more resilient income by reviewing a curated 4 dividend fortresses that concentrates on higher yield opportunities with supporting fundamentals.
- Dial down portfolio stress by filtering a 6 resilient stocks with low risk scores that homes in on businesses with stronger balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com