


UiPath has built its story around automation and AI partnerships, yet the bigger question for you as a shareholder is whether the current price lines up with the cash it can realistically generate. With the share price near US$12.83 after a difficult few years, the focus now shifts to what those cash flows are actually worth on a Discounted Cash Flow (DCF) basis.
- Over the past 5 years the stock has fallen 77.1%, which puts the spotlight squarely on whether the market has reset expectations to something closer to what UiPath's cash flows can support.
- Recent partnerships such as the launch collaboration with Google Cloud's Gemini for healthcare and recognition in automation platform assessments can influence expectations for future revenue, profitability and the timing of cash generation that matter directly for any intrinsic value estimate.
- Prefer to judge UiPath on earnings? See what UiPath's 18.5x P/E says about the price.
The issue now is whether UiPath's current market value is properly supported by the cash flows suggested by a Discounted Cash Flow (DCF) model.
If you want to stress test UiPath's cash flow story against other automation and AI players, compare it with 89 robotics and automation stocks.
Is UiPath Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here is built on UiPath turning steady free cash generation today into larger cash streams over time. Latest twelve month free cash flow sits at about $357.3 million, which gives the model a real cash base rather than a purely story driven forecast. Projections out to 2029 point to growing annual free cash flow, with the 2 Stage Free Cash Flow to Equity setup assuming that this expansion gradually slows rather than staying in rapid acceleration mode forever.
Against a share price of $12.83, the DCF output suggests those projected cash flows add up to an intrinsic value that is substantially above where the stock trades today. The launch partnership with Google Cloud's Gemini for healthcare gives some real world context for those growth assumptions, because it links UiPath's automation platform directly into a large and tightly regulated sector where governed AI workflows matter. That kind of integration helps explain why the market might still be pricing the shares below what the model implies, even after a tough few years. Find out what UiPath could be worth using our Discounted Cash Flow (DCF) estimate.
The UiPath Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle leaves off and explain which paths for UiPath's growth, margins and earnings would need to hold for the shares to be worth materially more or less than they are today. Each scenario ties a fair value to a distinct mix of potential catalysts and risks, so you can track over time which version of the story appears to be unfolding on Simply Wall St's Community page.
UiPath splits opinion between a cash rich automation platform that can compound ARR and margins, and a show me story facing pricing friction and growth doubts.
Bull case: 16% undervalued
This is how the analyst consensus Narrative on Simply Wall St frames the upside in UiPath.
"UiPath’s emphasis on structurally improving profitability, including non GAAP operating margin expansion of more than 1,500 basis points, lower stock based compensation, four consecutive GAAP profitable quarters, and an ongoing share repurchase program funded by US$1.4b of cash and no debt, provides a framework that could support net margins, earnings and per share metrics…"
Discover why this Narrative puts UiPath at 16% undervalued.
Bear case: 28% overvalued
The bearish analyst Narrative on Simply Wall St leans into slower growth and stickier execution risk around UiPath.
"Several firms cut price targets into a US$10 to US$18 range and in some cases also downgraded their ratings, citing uncertainty around sustainable growth and the impact of pricing pressure on AI offerings…"
Explore why this Narrative puts UiPath at 28% overvalued.
One more UiPath signal that could change how you read the story
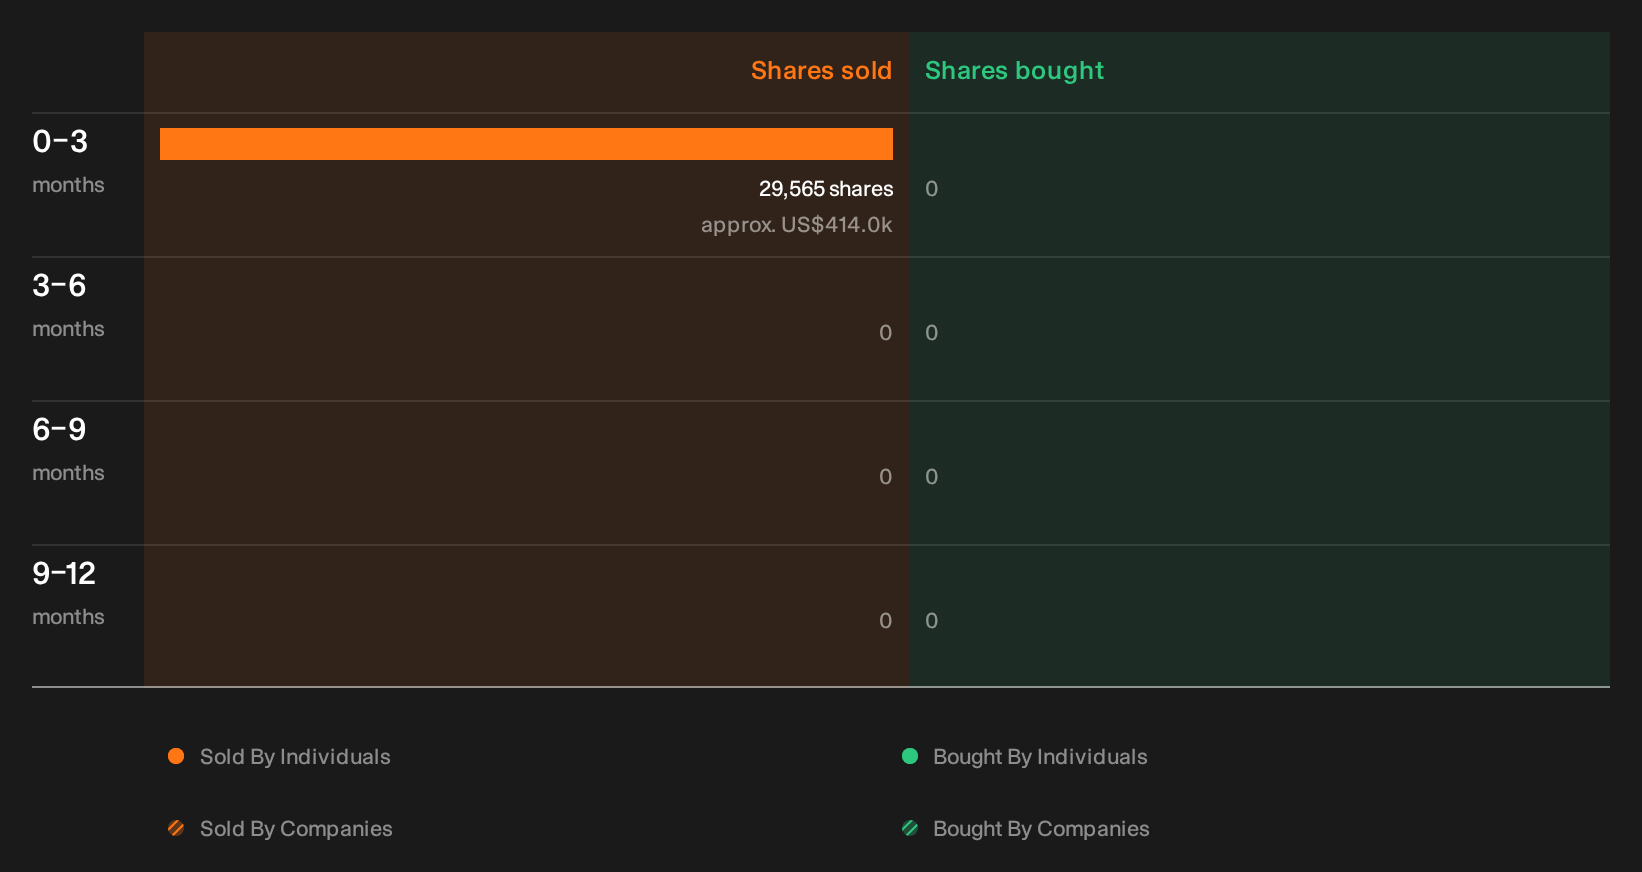
DCF work frames what UiPath might be worth, but recent trades by people inside the business add a different layer, since the individuals, volumes and possible interpretations are all sitting there for you to review. See the recent insider selling flagged for UiPath.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com