


Nebius Group (NBIS) is heading into a closely watched earnings event on Nov. 12, when the artificial intelligence (AI) cloud company is scheduled to report its third-quarter 2026 results before the market opens. Investors will be looking beyond the headline numbers for evidence that surging demand for AI infrastructure is translating into sustained revenue growth, stronger utilization, and improving profitability.
Wall Street expects Nebius to report Q3 revenue of roughly $907.2 million, while the consensus calls for a loss of about $0.61 per share. The company enters the report with ambitious targets, including $3 billion to $3.4 billion in 2026 revenue, a $7 billion to $9 billion annualized revenue run rate (ARR), and 800 megawatts to 1 gigawatt of connected power by year-end.
With Nebius aggressively expanding its GPU capacity and data-center footprint while navigating substantial capital expenditures, investors will also be watching management’s commentary on AI cloud demand, pricing, deployment timelines, and Nebius' ability to execute on its large contracted-power pipeline.
About Nebius Stock
Headquartered in Amsterdam, The Netherlands, Nebius Group is a technology company focused on building full-stack cloud infrastructure for the global AI industry. Its core business, Nebius AI Cloud, provides AI developers and enterprises with GPU computing, storage, managed services, and software tools for training, fine-tuning, and deploying AI models at scale. The company also operates businesses including autonomous-vehicle developer Avride and technology-focused education platform TripleTen, while maintaining equity stakes in companies like ClickHouse and Toloka. Nebius Group has a market capitalization of $33.9 billion.
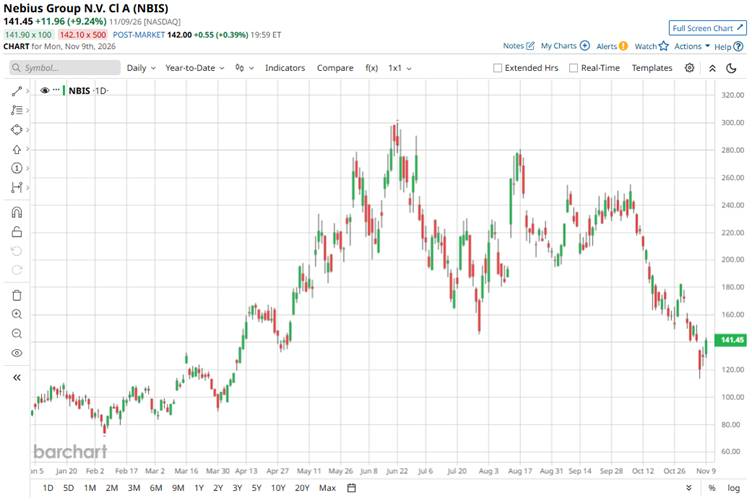
NBIS stock has delivered strong gains over the longer term, but the shares have come under significant pressure in recent weeks as investors reassess the valuation and risk profile of AI infrastructure firms. NBIS stock is up 56% over the past 52 weeks and 91% year-to-date (YTD) but has fallen 28% over the past month. The sharp pullback reflects a broader de-risking across AI and data-center stocks, with investors increasingly focused on the enormous capital requirements needed to build AI infrastructure, questions about the returns on that spending, and concerns over financing and data-center development.
The recent trading pattern also highlights just how volatile NBIS stock has become ahead of its Q3 earnings report. Shares plunged 15% on Nov. 5, closing at $120.37, before rebounding almost 8% on Nov. 6 to $129.49 and another 9% on Nov. 9 to $141.45.
The sharp rebounds suggest that some investors are viewing the selloff as an opportunity to accumulate shares ahead of earnings, particularly given Nebius’ exposure to rapidly growing AI computing demand.
NBIS stock currently trades at 67.5 times sales, which is a premium compared to industry peers.
Nebius Delivers Explosive Q2 Growth
Nebius Group released its Q2 2026 results on Aug. 12, before the market opened. The AI cloud provider delivered another quarter of exceptionally strong growth, with revenue jumping 454% year-over-year (YOY) to $582.3 million, exceeding Wall Street estimates. The core Nebius AI cloud business generated $575 million, up approximately 514% YOY, and accounted for nearly all of the group’s revenue.
Profitability improved dramatically as the business scaled. Adjusted EBITDA rose to $236.2 million, compared with an adjusted EBITDA loss of $21 million a year earlier. Adjusted EBITDA margin was approximately 41%, while the AI cloud business achieved a roughly 50% adjusted EBITDA margin.
On the bottom line, adjusted net loss narrowed to $33.2 million from $91.5 million, a 64% improvement. Adjusted loss per share was around $0.12, substantially better than the $0.38 loss per share reported a year earlier.
Commercial momentum was arguably the most important takeaway. Nebius signed four landmark AI cloud contracts averaging more than $1 billion each, while total contract value nearly quadrupled and new-customer contract values increased more than ninefold. Management said demand for AI computing capacity remained well ahead of supply and indicated that it could theoretically sell its entire planned 2027 capacity under existing terms. Nebius also reported more than $40 billion of customer commitments and expects more than $9 billion of customer prepayments during 2026, providing an important source of funding for expansion.
Meanwhile, Nebius reaffirmed its full-year 2026 financial guidance, calling for $3 billion to $3.4 billion of group revenue, ARR of $7 billion to $9 billion, and a group adjusted EBITDA margin of approximately 40%. The firm also maintained its $20 billion to $25 billion capex outlook as it accelerates GPU and data-center deployment.
Additionally, Nebius raised its 2026 contracted-power target to 5 GW, while maintaining its target of 800 MW to 1 GW of connected power by year-end. The company expects to deploy more than 1 GW of capacity annually beginning in 2027. Although enormous capex requirements remain a key risk, the combination of long-term contracts, customer prepayments, and strong demand provides greater visibility into future revenue.
Analysts forecast a loss per share of around $3.19 for fiscal 2026, an 80% YOY deterioration, before a 26% YOY improvement to a loss of $2.37 in fiscal 2027. The consensus loss per share estimate of $0.61 for Q3 2026 indicates a 56% YOY deterioration.
What Do Analysts Expect for Nebius Stock?
On Nov. 4, Citigroup analyst Tyler Radke lowered his NBIS stock price target to $265 from $324 while maintaining a “Buy” rating. The revised target was issued ahead of the Q3 report and reflects Citi's view that the neocloud sector continues to benefit from AI infrastructure demand, while investor attention is increasingly shifting toward how companies like Nebius will finance their aggressive expansions.
Last month, Piper Sandler analyst James Fish also maintained a “Neutral” rating on the stock while cutting the price target to $185 from $237. The move came amid growing investor concerns over AI demand, return on invested capital, and the financing requirements of capital-intensive infrastructure buildouts.
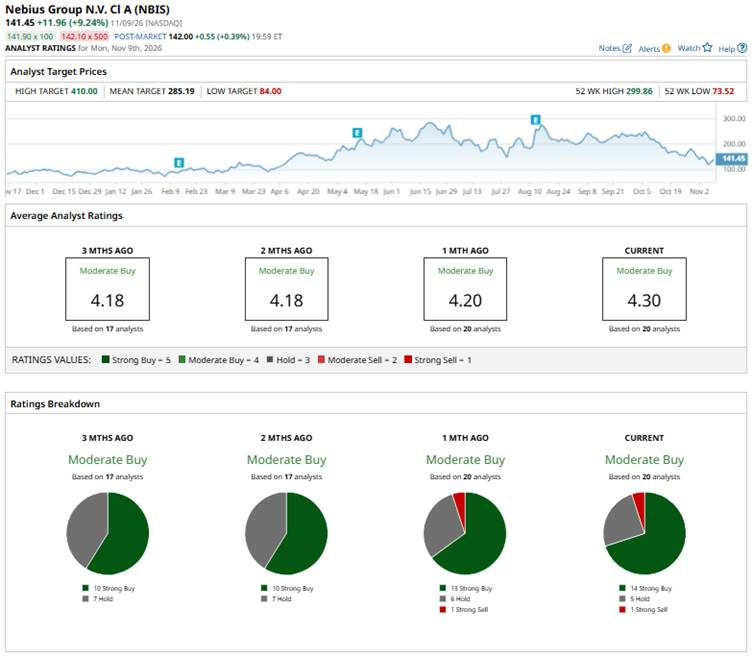
Overall, NBIS stock has a consensus “Moderate Buy” rating on Wall Street. Of the 20 analysts covering the stock, 14 advise a “Strong Buy,” five suggest a “Hold” rating, and one analyst advises a “Strong Sell" rating. The average price target of $285.19 indicates potential upside of 82%, while the Street-high target of $410 suggests the stock could rally as much as 161% from here.
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.