


NextVision Stabilized Systems (TASE:NXSN) reported record Q3 2026 results, with sales of US$106.39 million and net income of US$60.06 million. The company also raised its full-year revenue target to US$355 million.
Despite the strong Q3 print, NextVision Stabilized Systems' share price has declined about 19% year to date, even though the 1 year total shareholder return is roughly 21% and the 5 year total shareholder return is above 20x. This points to long term momentum but some cooling sentiment in recent months following governance changes and expansion updates.
Scan beyond NextVision Stabilized Systems and explore other fast moving defense and robotics plays with the hand picked 89 robotics and automation stocks that could sit on your watchlist next.
NextVision Stabilized Systems has a share price that has cooled while analyst targets and implied fair value estimates still sit much higher. Where does the realistic valuation anchor for this stock actually land now?
Most Popular Narrative: 56% Undervalued
At a last close of ₪186.4 against a narrative fair value of ₪426.41, the bullish analyst Narrative on Simply Wall St describes a wide valuation gap that is based on very strong growth and margin assumptions, supported by sector demand and capacity expansion.
Rapid growth in global aerospace and defense budgets, including higher allocations to autonomous systems in the US and multi year budget increases in Europe, Japan and India, is associated with stronger demand for NextVision Stabilized Systems cameras and may support revenue growth and order visibility.
Expansion of production capacity from 1,500 to more than 3,000 units per month, with a target above 5,000 units per month and added manufacturing in Europe, provides room for larger order volumes and may support higher revenue. This expansion can also spread fixed costs over more units to help protect margins.
See why 4 investors see NextVision Stabilized Systems as 56% undervalued.
Result: Fair Value of ₪426.41 (UNDERVALUED)
Still, the bullish case for NextVision Stabilized Systems depends on defense demand and capacity use staying supportive, while slower orders or tougher rivals could quickly test that thesis.
Find out about the key risks to this NextVision Stabilized Systems narrative.
Another View: What Multiples Say About NextVision Stabilized Systems
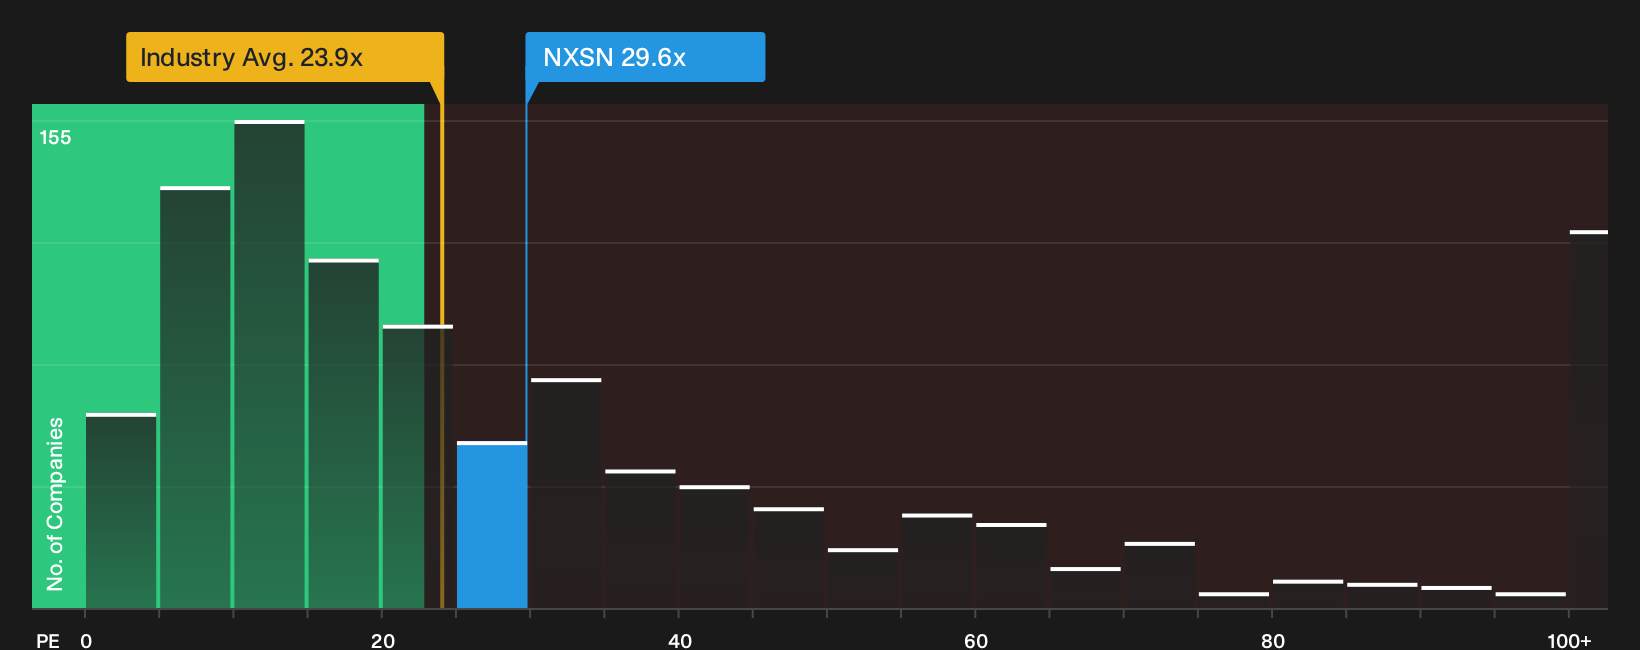
The bullish fair value for NextVision Stabilized Systems leans heavily on aggressive growth forecasts and a rich future P/E of 56.1x. Right now the shares trade on 29.6x earnings, which is higher than both the Asian Electronic industry at 23.9x and a peer average of 22.5x. That richer multiple points to less margin for error and leaves you asking whether the optimism in those earnings forecasts already sits in the price.
See what the numbers say about this price with a closer look at the detailed valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and concern around NextVision Stabilized Systems feels familiar, that is the signal to review the data yourself and decide quickly where you stand. To help frame that view, take a closer look at the balance of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond NextVision Stabilized Systems?
Do not stop with a single stock story when there are tools built to surface fresh ideas quickly for your watchlist and deeper research.
- Target potential mispricing by scanning a curated set of 201 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect their underlying strength.
- Build a steadier income stream by checking out 216 dividend fortresses that focus on higher yields with an emphasis on resilience and consistency.
- Strengthen capital protection by reviewing a 209 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com