


Oracle (ORCL) received a fresh vote of confidence from Bernstein this morning as the investment firm reaffirmed its “Outperform” rating and $325 price target on the AI infrastructure giant.
In his research note, analyst Mark Moerdler said ORCL’s recent selloff overshadows its improving long-term fundamentals, particularly as its AI business continues to gain traction.
His bullish call arrives at a time when Oracle stock has fallen out of favor with investors, currently trading at nearly half its year-to-date high set in early June.
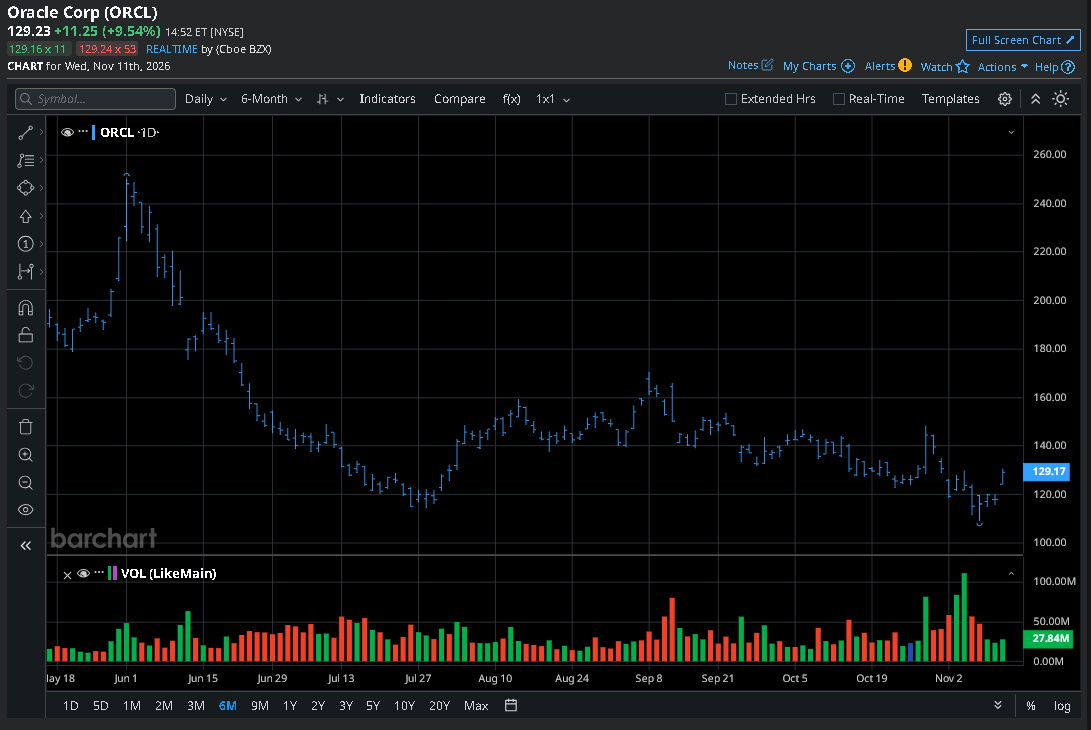
Why Bernstein Recommends Owning Oracle Stock
Bernstein’s latest analysis suggests Oracle’s AI-related investments could generate stronger long-term returns than previously anticipated.
Analyst Mark Moerdler remains convinced that concerns surrounding the company’s heavy capital expenditures are obscuring the larger opportunity.
According to him, ORCL is building a leading position in AI computing infrastructure while also benefiting from demand for its cloud and database offerings.
Moerdler doesn’t expect the NYSE-listed giant to require additional external funding and estimates that it is roughly 18 months away from reaching positive free cash flow.
Note that ORCL shares also currently pay a healthy dividend yield of 1.55%.
What Could Drive ORCL Shares Higher?
Bernstein identified two developments that could reshape investor sentiment toward Oracle shares.
First is a potential OpenAI initial public offering (IPO), which Moerdler believes will offer greater transparency into whether OpenAI and the broader AI ecosystem can support the huge computing commitments already made.
Second is ORCL’s anticipated return to positive free cash flow in the back half of fiscal 2028 – a milestone he said will serve as critical validation of the firm’s long-term AI investment strategy.
Oracle is currently trading at a price-to-sales (P/S) multiple of about 5x, which the analyst dubbed a discount to its historical averages in his report.
How Wall Street Recommends Playing Oracle
Crucially, Wall Street analysts haven’t thrown in the towel on ORCL stock either.
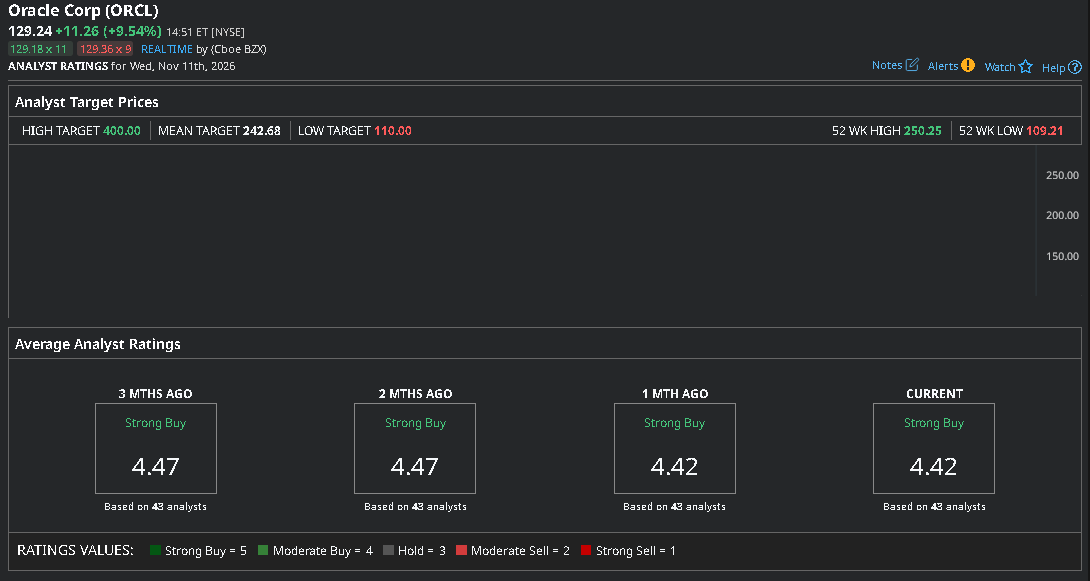
According to Barchart, the consensus rating on the AI infrastructure firm remains at “Strong Buy” – with the mean price target of about $243 indicating potential upside of more than 85% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.