


Marvell Technology has swung sharply in recent months, with a long run of gains colliding with fresh concern about AI spending and a large proposed merger. This now puts a simple question in front of you as a shareholder or potential buyer: Is the latest share price still supported by what the business actually earns?
- Over the past 3 years the stock has returned about 172.3%, which raises the question of whether that kind of share price climb is still in line with its earnings power.
- The planned all stock acquisition of Lumentum, valued at roughly US$115b for the combined entity, can reshape Marvell’s earnings profile by tying future profit growth and dilution risk directly to how well the enlarged group turns AI connectivity demand into sustainable income.
- There is a second opinion on Marvell Technology worth weighing. See what analysts think Marvell Technology's shares could be worth.
The issue now is whether today’s valuation for Marvell Technology is adequately backed by its current and expected earnings stream.
If you are weighing Marvell Technology against other ways to get exposure to this AI build out theme, a simple comparison is to line it up next to 53 AI infrastructure stocks.
Is Marvell Technology Fairly Priced on Earnings?
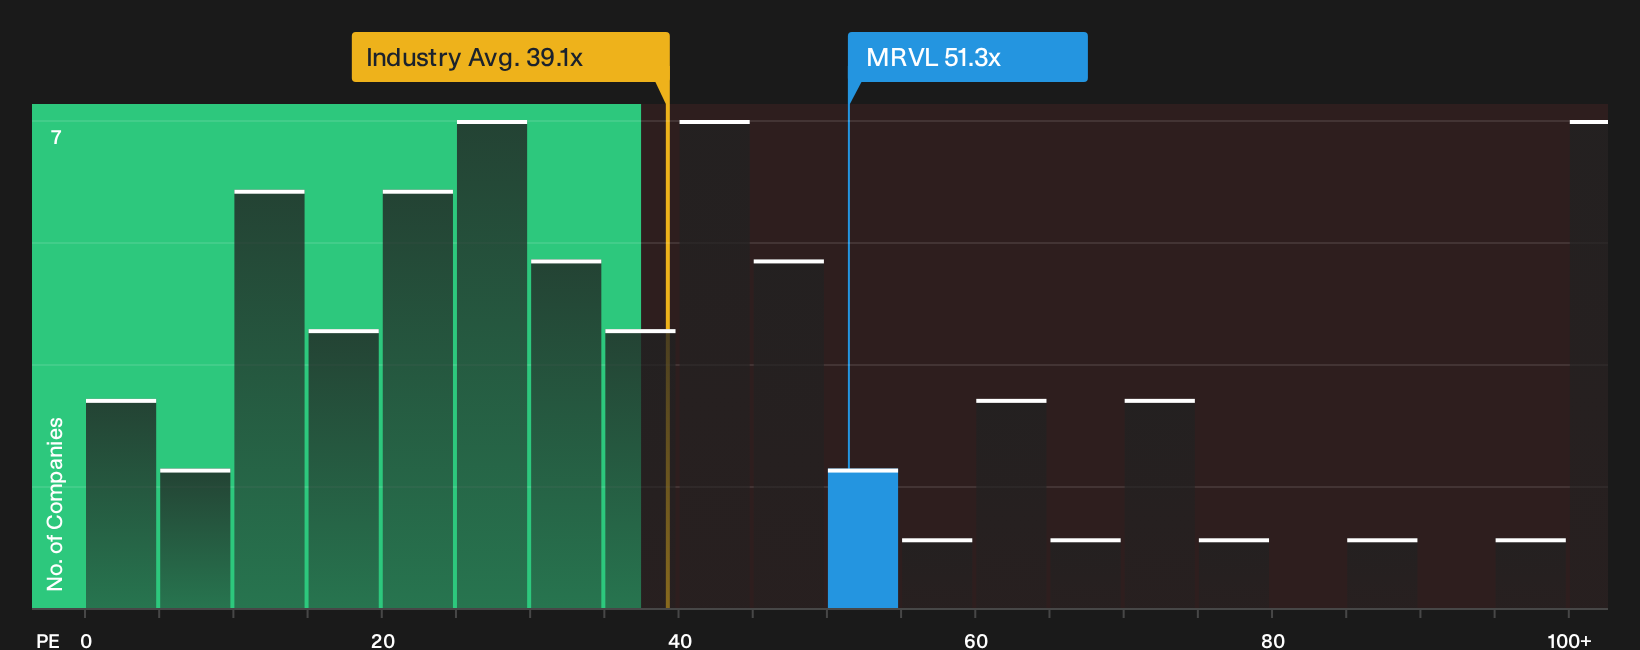
P/E fits Marvell Technology because earnings are the key yardstick most investors watch for established semiconductor stocks. The current P/E of 51.3x sits above the broader semiconductor sector, where the average is 39.1x, yet below the peer group average of 85.3x. That puts the share price in a zone where the market is clearly paying up for the AI and data center story, but not at the very top of the range for comparable chip makers.
The fair P/E that the model suggests, given Marvell Technology’s growth profile, margins, size and risk, sits close to the present level, so the stock looks broadly aligned with what this tailored benchmark implies. Despite the sharp reaction to the proposed US$115b all stock Lumentum deal, the current earnings multiple still prices Marvell as a quality AI infrastructure play rather than a clear bargain or an obvious outlier. Explore the numbers behind Marvell Technology's P/E valuation.
The Marvell Technology Narrative: What Would Justify Today's Price?
Narratives for Marvell Technology pick up where the P/E puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to occur for the stock to trade meaningfully higher or lower than today’s level. These narratives are available on Simply Wall St's Community page. Instead of one static output from a ratio or model, Narratives explain the future assumptions behind that figure so you can see whether reality continues to match the script.
Views on Marvell Technology split between those who see the AI build out supporting much more earnings power and those who think expectations already run hot.
Bull case: 51% undervalued
According to the analyst consensus Narrative on Simply Wall St, the bullish view leans heavily on Marvell Technology’s AI connectivity roadmap and margin targets.
"The main thing that has to go right is that Marvell converts its expanding AI networking, optics and custom XPU pipeline into the guided data center and custom revenue growth while sustaining its target non GAAP operating margin range..."
Discover why this Narrative puts Marvell Technology at 51% undervalued.
Bear case: 10% overvalued
In contrast, sorkdhkddlek, an investor in the Simply Wall St Community, argues that the current price already bakes in demanding execution on multiple fronts.
"At approximately $134, the stock is priced for FY2028 execution. The investment thesis requires believing Marvell can deliver around $15B in FY2028 revenue, but there is no margin for error..."
Explore why this Narrative puts Marvell Technology at 10% overvalued.
One more piece of the Marvell Technology puzzle
Before you stop at the P/E and the AI story, it is worth checking who is steering Marvell Technology and how their rewards line up with your interests. See who runs Marvell Technology and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com