


Novo Nordisk has seen a sharp reset in its share price over the past few years, even as it remains in the spotlight for obesity and diabetes treatments. With the stock now around US$40.70 after a prolonged slide, the key issue for you as an investor is whether that price still lines up with what the business is earning.
- Over the past 3 years the share price has fallen 56.4%, which puts the focus squarely on whether earnings now give enough support to the current valuation.
- Recent updates around obesity drugs like Wegovy and the pipeline candidate CagriSema point to management expectations for continued demand, which can affect how much profit growth the market is building into Novo Nordisk’s earnings multiple today.
- Your read on Novo Nordisk is one view; the desks covering it have another. See what analysts think Novo Nordisk's shares could be worth.
The issue now is whether Novo Nordisk’s current earnings justify the price investors are paying for the stock today.
If you are weighing Novo Nordisk after a 56.4% share price decline over 3 years, it can help to compare it with a wider set of 35 high quality undervalued stocks
Does Novo Nordisk Look Undervalued on Earnings?
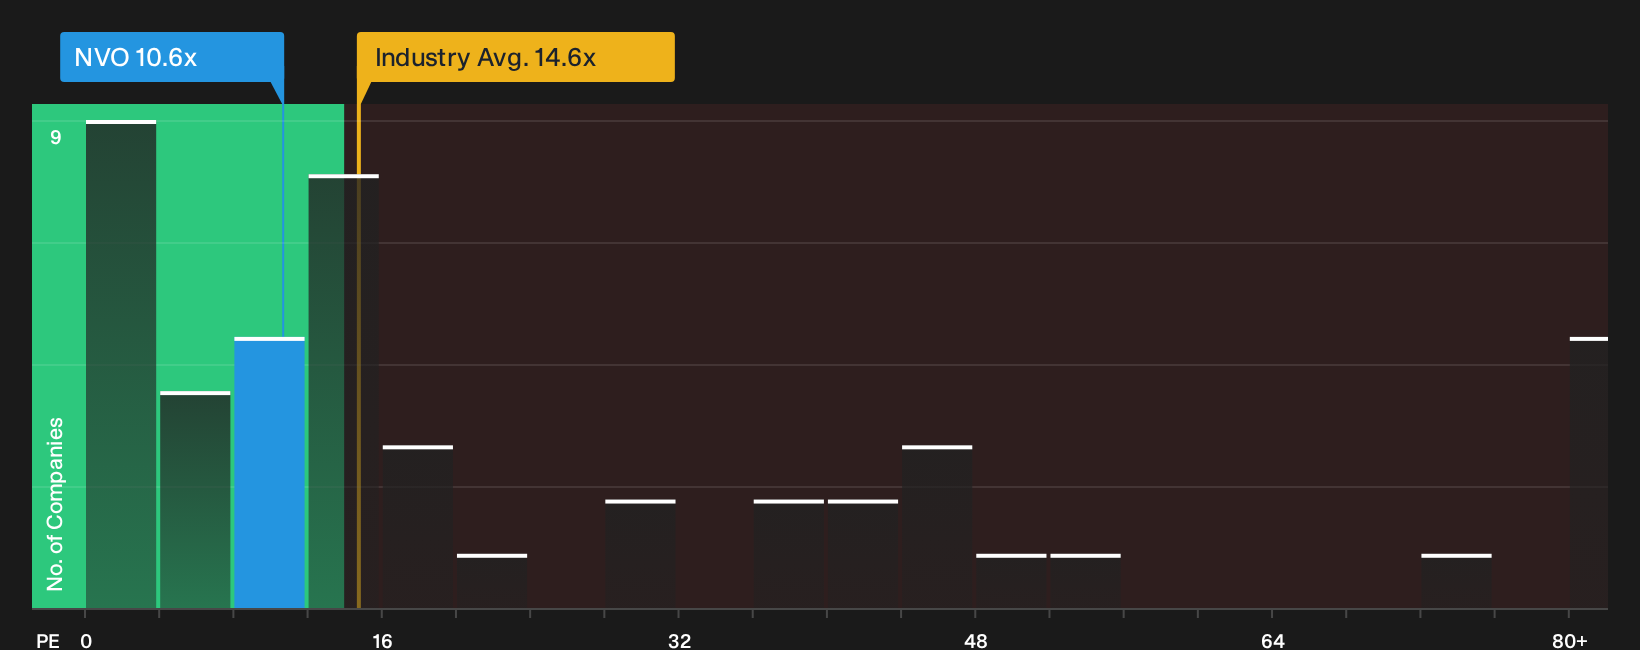
P/E is usually a useful way to look at Novo Nordisk because earnings are a key focus for investors in large, profitable pharmaceuticals. On this metric, the stock trades on about 10.6x earnings, compared with roughly 14.6x for the wider Pharmaceuticals industry and 61.5x across close peers in the obesity and diabetes space. That puts Novo Nordisk on a noticeably lower earnings multiple than both its sector and many direct competitors.
Because the fair P/E that factors in Novo Nordisk’s growth profile, margins, scale and risk sits above the current 10.6x, the valuation screens as undervalued on this framework. Despite management raising its 2026 outlook again on the back of Wegovy and pipeline news, the P/E still reflects a discount to what the model suggests investors might typically pay for these economics. For you as a shareholder or prospective buyer, the key question is whether the earnings power behind that ratio feels durable enough to justify closing some of that gap over time. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Novo Nordisk valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today's price, and they sit on the platform's Community page. Each scenario anchors a fair value to a clear mix of potential catalysts and risks, so you can track over time which storyline seems closest to how Novo Nordisk's reality unfolds.
One of the top community narratives on Novo Nordisk: 57% undervalued
According to bactrian, an investor in the Simply Wall St Community, Novo Nordisk’s recent reset is less about broken fundamentals and more about sentiment.
"Despite near-term pressures, Novo Nordisk remains a highly profitable, capital-efficient leader in a massive and still-growing market, with the company investing aggressively in capacity and R&D..."
Discover why this Narrative puts Novo Nordisk at 57% undervalued.
One more Novo Nordisk check that sits alongside the share price
Balance sheets and P/E ratios only tell part of the story, because the people steering Novo Nordisk and the way their rewards are structured can shape how your interests are treated over time. See who runs Novo Nordisk and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com