


EPR Properties has ridden a strong multi year rebound in its share price, and the latest financing moves put fresh attention on whether that climb is fully backed by the earnings the real estate investment trust is producing today. With the stock closing at US$61.18, the key issue now is how that market value lines up against what its profits can support.
- Over the past 5 years the stock has returned 72.6%, which puts a lot of accumulated optimism on the line if earnings do not keep pace with expectations.
- The proposed US$500.0 million convertible senior notes and planned share repurchases can reshape both the share count and interest costs, which may influence how much of EPR Properties' cash flow ultimately supports each share's earnings power.
- The analysts covering EPR Properties have run their own numbers. See what analysts think EPR Properties's shares could be worth.
The stock's next move may depend on whether the current price is reasonable when set against the earnings that EPR Properties is generating and expected to sustain.
If you are weighing EPR Properties' earnings against its recent share price run, it can help to compare that story with 35 high quality undervalued stocks.
Is EPR Properties a Bargain on Earnings?
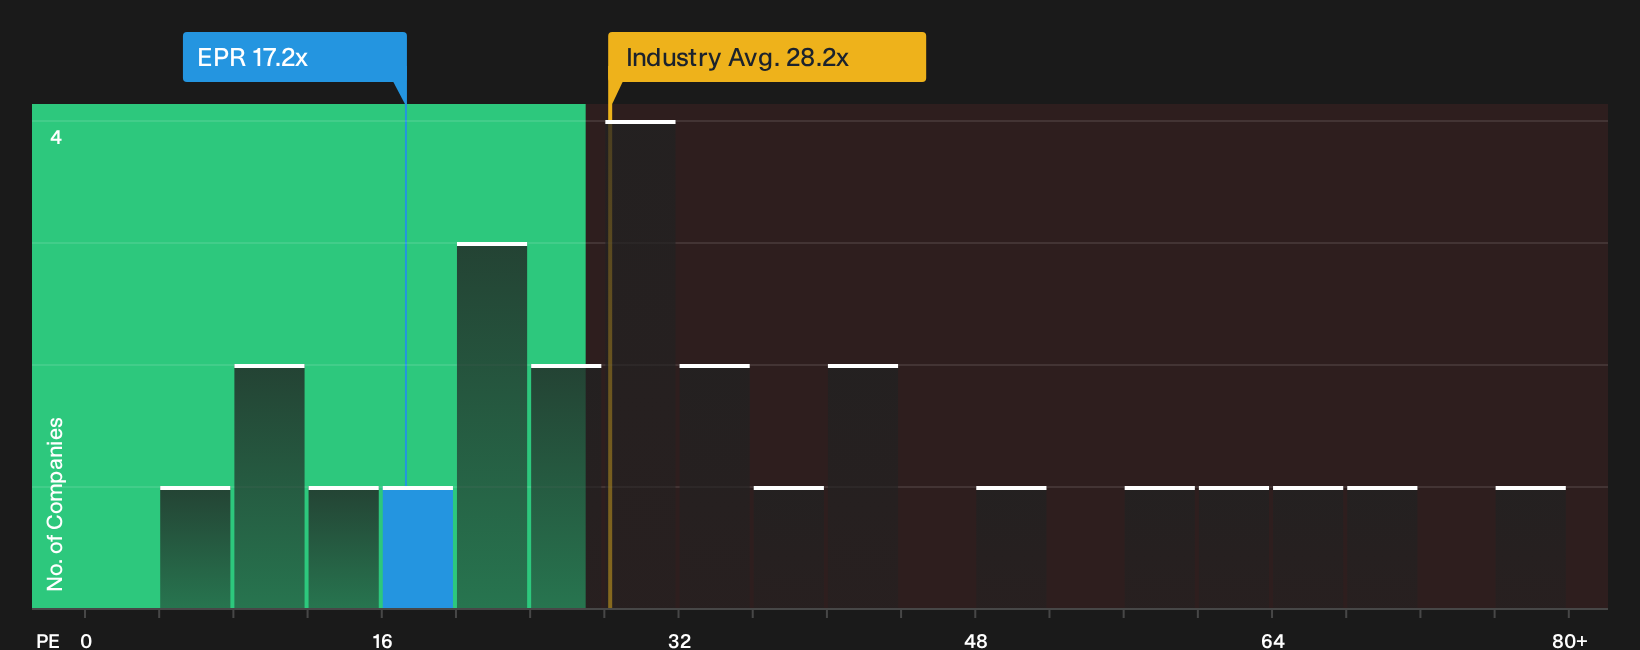
The P/E ratio works well for EPR Properties because earnings per share sit at the center of how REIT investors judge payout capacity. On this measure, the stock trades at about 17.2x earnings, which is slightly above the specialized REIT average near 15.1x but below the broader peer group around 21.3x. That places EPR in a kind of middle ground where the market is neither attaching a steep premium nor marking it down aggressively relative to similar businesses.
Because the fair P/E suggested by a model that weighs EPR Properties' growth profile, margins, size and risk sits above the current 17.2x, the shares screen as undervalued on this framework. The recent Q3 2026 earnings beat and raised FFO guidance help explain why investors are willing to pay more than the sector average. At the same time, the multiple still does not fully reflect what this model implies the earnings stream could justify. Explore the numbers behind EPR Properties's P/E valuation.
The EPR Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for EPR Properties pick up where the P/E discussion stops by spelling out what kind of future growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than today. They also lay out the underlying assumptions so you can see the future that any single valuation figure relies on and track whether those conditions actually show up over time on the Community page.
One of the top narratives on EPR Properties: 5% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current numbers on earnings guidance, investment yields, balance sheet metrics and dividend coverage imply that EPR Properties’ share price does not fully reflect the company’s progress..."
Discover why this Narrative puts EPR Properties at 5% undervalued.
Before you focus on price, EPR Properties has other signals to check
Valuation only tells part of the story for EPR Properties, since recent research has also flagged specific risk checks that could change how you view the whole profile if you review them next. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com