


- Golar LNG has been highlighted as a pure play on floating liquefaction and regasification, with 20 year charters that support a contracted EBITDA backlog of about $17b and provide long term visibility on cash generation.
- The focus on floating LNG infrastructure during a period of tight supply and global shipping disruptions underscores how Golar LNG’s contracted assets tie directly to physical energy flows rather than short term trading swings.
- We will now look at how Golar LNG’s long dated FLNG charters and $17b EBITDA backlog could reshape its investment narrative.
Scan opportunities beyond Golar LNG by comparing it with a curated 42 power grid technology and infrastructure stocks that sits at the intersection of energy security and essential infrastructure demand.
Golar LNG Investment Narrative Recap
To own Golar LNG, you need to believe in a long life, contracted FLNG infrastructure story where $17b of EBITDA backlog and 20 year charters translate into sustained cash generation. The analyst consensus narrative on Simply Wall St leans on this backlog and on forecasts of faster than 20% annual revenue growth. The recent focus on tight LNG supply does not materially change that core thesis. In the near term, the key operational swing factor remains reliable uptime and cost control on existing FLNG units.
On the risk side, the immediate concern is funding growth with higher cost debt and the pressure that interest expense and weaker free cash flow coverage could put on margins. Debt is flagged as not well covered by operating cash flow, and the dividend is described as not well covered by free cash. If cash generation disappoints against expectations, the biggest near term risk is a need for more expensive capital that dilutes the benefit of contracted EBITDA.
The most relevant ongoing development is Golar LNG’s plan for a fourth Mark II FLNG unit with an all in CapEx budget of about US$2.45b and targeted delivery in 2029. That project sits on top of the existing 20 year charter portfolio and is central to analyst expectations for a larger LNG linked earnings base over time. It is also closely tied to the current news focus on floating infrastructure during supply disruptions.
Execution on this fourth FLNG is a practical test of the whole growth story. Financing terms, contract quality and build schedule will influence whether the projected increase in liquefaction capacity to more than 12 million tonnes per year translates into the earnings and free cash flow that analysts are modeling. For readers watching near term catalysts, progress updates on funding, chartering and construction milestones around this unit matter at least as much as short term price moves in the stock.
Golar LNG’s current analyst narrative points to US$802.8 million in revenue and US$501.2 million in earnings by 2029, anchored on 15.3% yearly revenue growth and an earnings increase of about US$337.5 million from US$163.7 million today.
Uncover why Golar LNG's fair value indicates a 52% potential upside to its current price, which could narrow quickly.
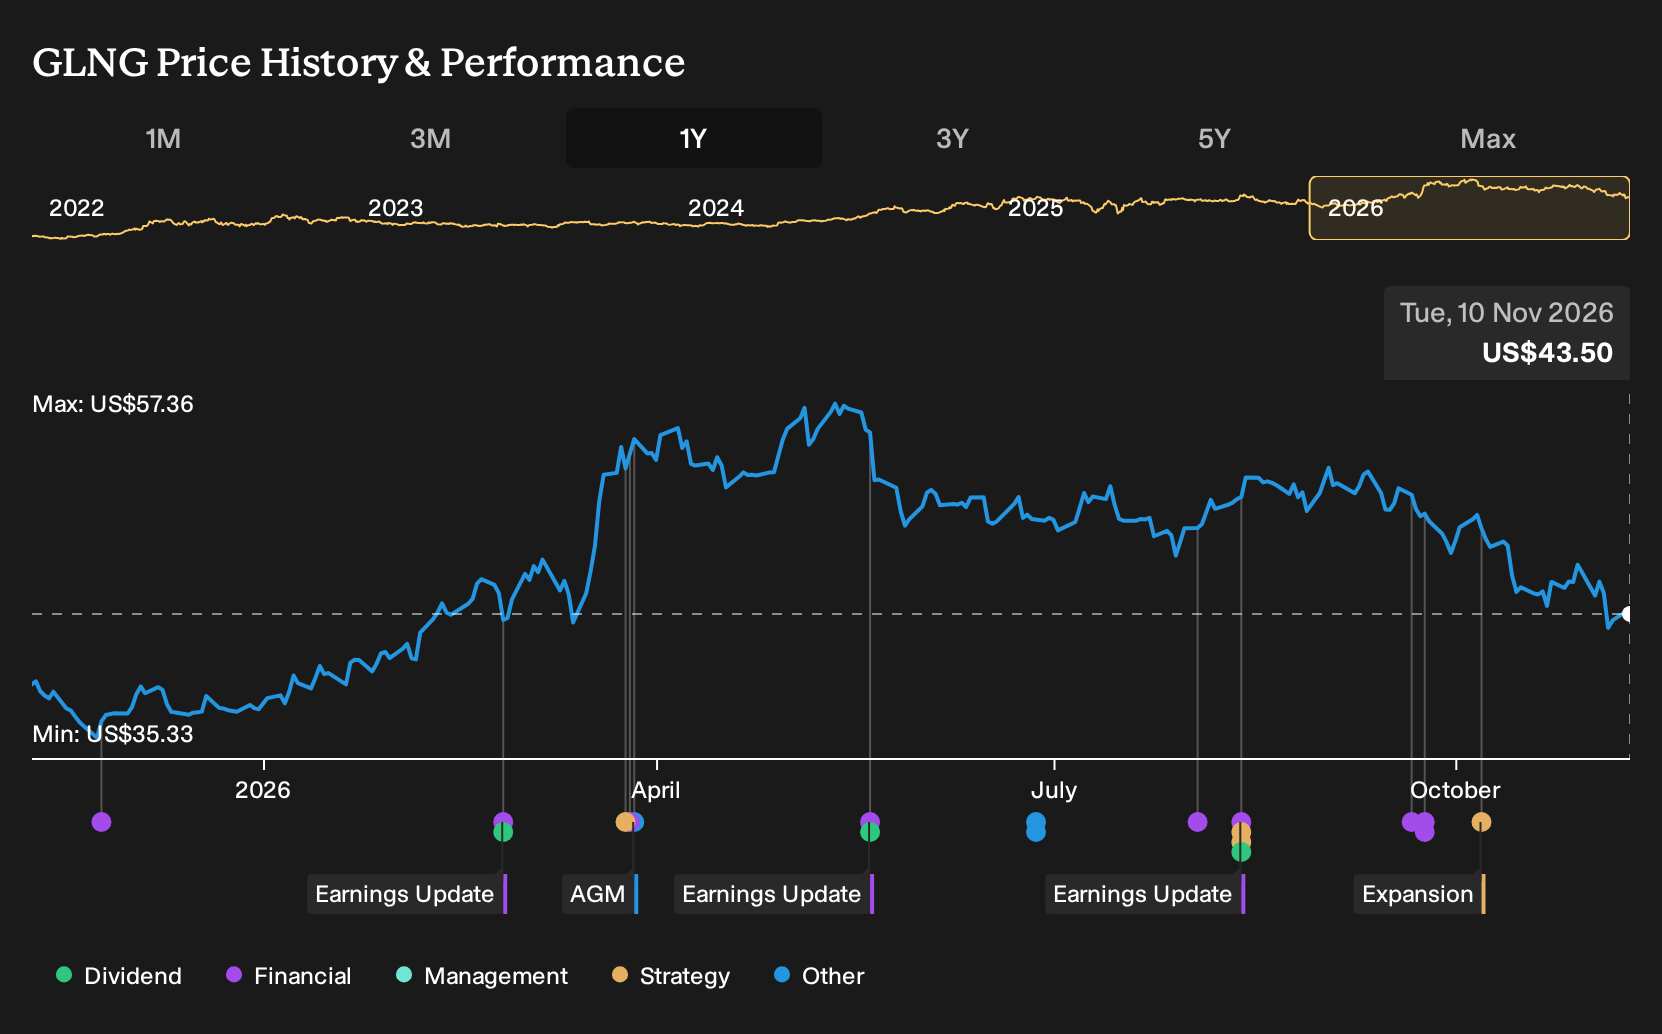
Exploring Other Perspectives
For Golar LNG, the biggest swing factor in the more optimistic narrative is not debt risk but the potential earnings lift from Argentina linked contracts. Before this news, the most bullish analysts were already modeling revenue of about US$1.1b and earnings of roughly US$635.3 million by 2029. You can now ask how fresh disruptions might push those projections, and the more cautious US$321.5 million earnings view, to converge or spread further as opinions adjust.
Explore 2 other Golar LNG fair value estimates, including one that suggests as much as 589% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Golar LNG research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Golar LNG. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Golar LNG's overall financial health at a glance.
Looking for more investment ideas beyond Golar LNG?
Once you have formed a view on Golar LNG, it helps to cross check that thinking against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If capital preservation sits high on your list, consider starting with a group of companies that screen well on resilience through a 30 resilient stocks with low risk scores.
- For readers hunting for potential mispricing, compare Golar LNG with a broader set of quality businesses trading below their estimated worth using a focused 35 high quality undervalued stocks.
- If reliable income is a priority, line up Golar LNG against a basket of high yielding payers by running a targeted 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com