


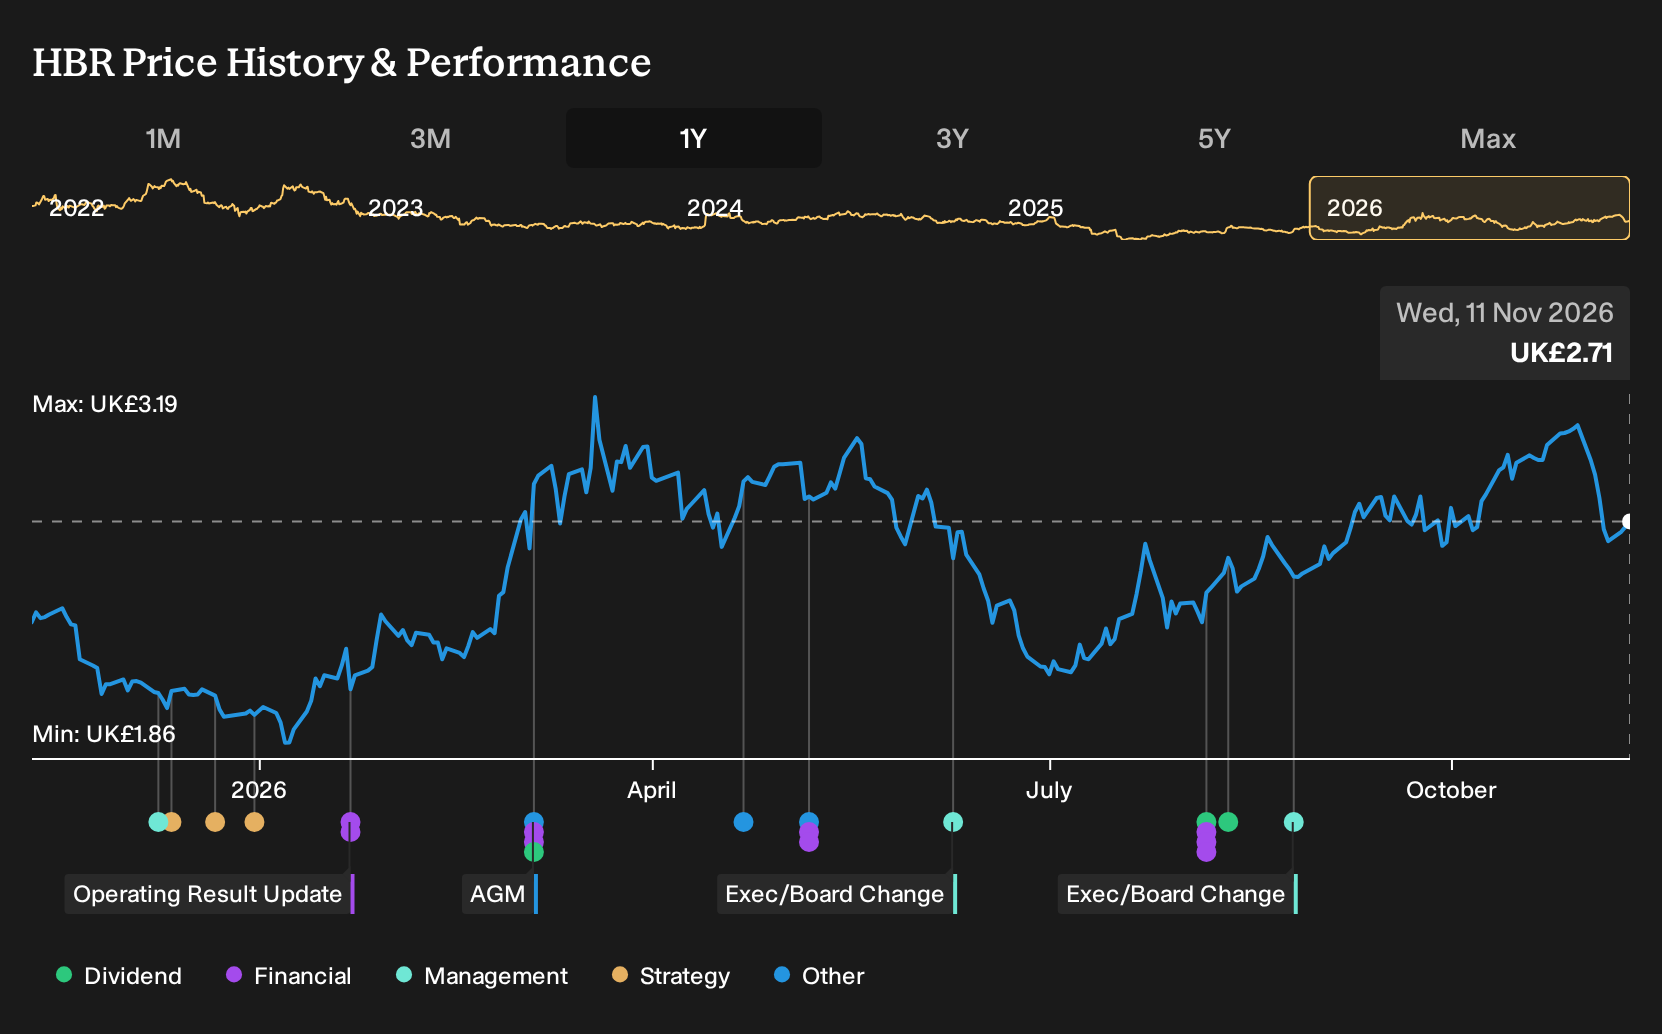
- Harbour Energy reported strong recent financial results, with 21.6% revenue growth, a very large earnings per share increase and a net cash position of US$461.2 million.
- The completed integration of the Wintershall Dea assets has shifted Harbour Energy toward a larger, more diversified production base that relies less on mature UK North Sea fields.
- We now look at how Harbour Energy's margin recovery and return to profit could influence the investment narrative that investors focus on.
Harbour Energy Investment Narrative Recap
To own Harbour Energy today, you need to buy into a story of a larger, more diversified producer that is trying to turn recent margin recovery into steadier earnings. The analyst consensus Narrative on Simply Wall St leans on that shift toward higher margin barrels and a portfolio less tied to mature UK North Sea fields. The most immediate swing factor remains realized oil and gas prices, with about 40% of output tied to European gas benchmarks.
The biggest operational risk is that UK fiscal pressure or weaker safety performance cuts into that margin recovery, especially after reported increases in injury rates. Recent revenue and earnings strength supports the idea of a sustainable profit base, but any pullback in TTF gas prices or higher remedial spending would test that thesis in the near term.
The most relevant backdrop to this news is the Wintershall Dea integration. The analyst consensus Narrative on Simply Wall St treats this as a core accelerator of scale and diversification. That deal has shifted Harbour Energy toward regions like Norway, Mexico and Argentina, where management aims to focus on higher margin, lower tax barrels, while letting some higher cost UK volumes roll off over time.
For you, the key question is whether Harbour Energy can turn that bigger footprint into consistent free cash flow while handling regional tax and safety risks. Execution on cost reductions, LNG and carbon capture projects, plus keeping injury rates under control, will likely drive how durable this recent profit recovery looks when the next set of results lands.
Harbour Energy's narrative projects US$9.8b revenue and US$724.9m earnings by 2029. This aligns with analyst assumptions that revenue may decline 4.9% a year and that earnings may increase by about US$392.9m from US$332.0m today.
Uncover how Harbour Energy's fair value indicates a 30% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view places greater emphasis on the risk that Harbour Energy may struggle to keep production close to the planned 475,000 to 500,000 boe/d plateau. In this scenario, the lowest analyst estimates model revenue of about US$8.4b and earnings of roughly US$293.3m by 2029, far below consensus. This gap highlights how widely opinions differ and provides a reason to explore several competing narratives as fresh results and integration updates potentially reshape expectations.
Explore 3 other Harbour Energy fair value estimates, including one that suggests it could be worth just £3.52!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Harbour Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Harbour Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harbour Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harbour Energy?
Once you understand where Harbour Energy fits in your portfolio, it can help to scan a broader set of opportunities with similar financial qualities. The Simply Wall St Screener lets you filter the market by balance sheet strength, earnings profile and risk level so you can line up Harbour Energy against a wider peer group.
- For investors who want potential mispricings with quality fundamentals at the core, review a curated 17 high quality undervalued stocks that may fit a value driven approach.
- If income is a priority and you prefer companies with higher yields, check out a focused set of 4 dividend fortresses that may suit a cash flow oriented portfolio.
- For a calmer ride when markets get choppy, survey a group of 5 resilient stocks with low risk scores that score well on financial resilience and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com