


- Herc Holdings appointed Luis Machado as senior vice president, chief legal officer and secretary, placing an experienced public company lawyer in charge of contracts, transactions, regulatory matters, litigation, governance and statutory reporting.
- The addition of a veteran legal executive with M&A, governance and multi-industry experience may support execution on Herc Holdings' expansion and integration plans while reinforcing corporate oversight.
- The focus now turns to how Herc Holdings' investment narrative around mega projects, specialty growth and integration efficiency is influenced by Machado's appointment.
Scan how Herc Holdings' governance shift compares with peers preparing for big project pipelines by reviewing a hand-picked list of solid balance sheet and fundamentals (24 results).
Herc Holdings Investment Narrative Recap
To stay invested in Herc Holdings, you need to believe the rental platform can turn mega project demand, specialty branches and digital tools into healthier profitability. The analyst consensus Narrative on Simply Wall St points to a mix of catalysts such as H&E integration synergies and balance sheet deleveraging that depend heavily on day to day execution.
In the short term, the key swing factor is whether Herc Holdings can defend margins despite higher fuel and transport costs and a history of weaker operating margin and EPS. Machado’s appointment looks incremental rather than transformational in the near term, although tighter governance might help keep integration spending, one off items and interest coverage risk in check.
The recent recognition of Herc Holdings as a leading employer for military veterans and spouses looks most relevant alongside this leadership change. A rental network that relies on field level decision making benefits when workforce retention and training are treated as core operating priorities rather than HR branding exercises.
For investors, the interest is practical. A veteran friendly culture can support safety, fleet care and service reliability, which matter when the analyst consensus Narrative on Simply Wall St leans on mega projects, specialty mix and digital adoption as earnings catalysts. It does not solve leverage or margin pressure, but it can affect how well those plans are carried out.
Herc Holdings' narrative projects US$6.4b revenue and US$665.1m earnings by 2029. This rests on analysts assuming 8.9% yearly revenue growth and an earnings increase of about US$542.1m from US$123.0m at present.
Uncover how Herc Holdings' fair value indicates a 15% potential upside to its current price before the market closes that gap.
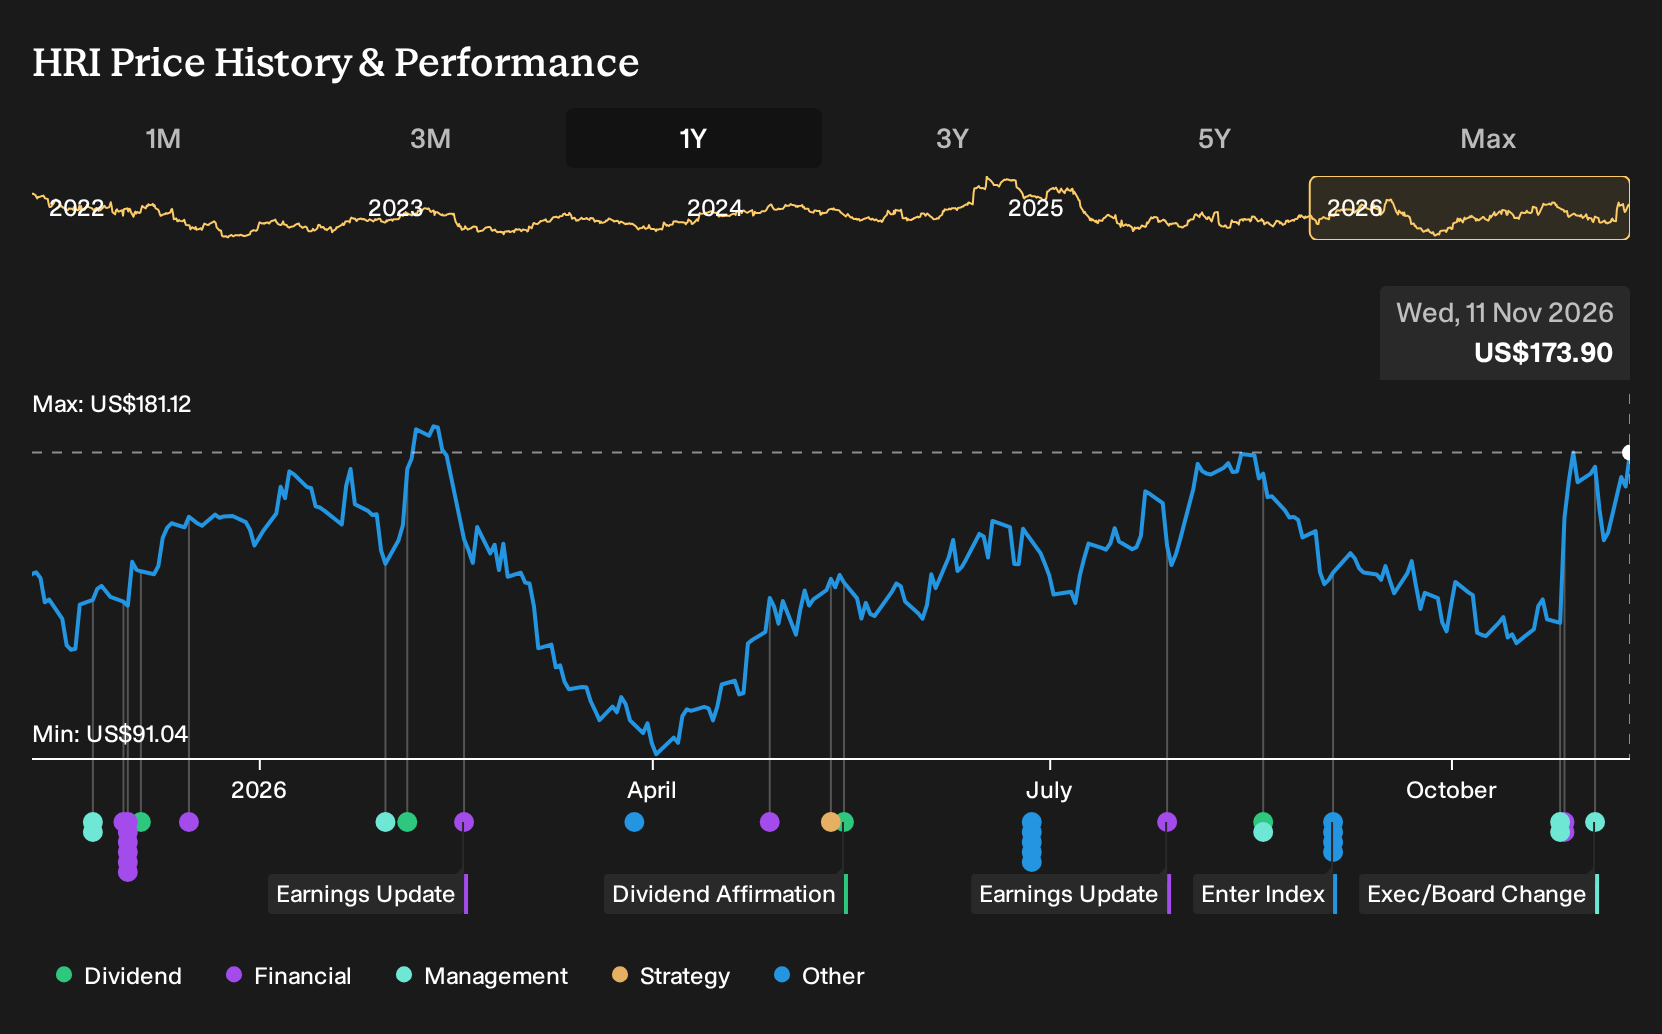
Exploring Other Perspectives
One alternate view puts less weight on mega projects and more on Herc Holdings’ leverage risk. Those more cautious analysts were penciling in about US$5.8b of revenue and US$483.2m of earnings by 2029, well below the consensus path. Your own take may shift as Machado’s governance role starts to influence future updates.
Explore 2 other Herc Holdings fair value estimates, including one that suggests as much as 25% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Herc Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Herc Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Herc Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Herc Holdings?
Once you have a handle on Herc Holdings, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- If you prefer resilient balance sheets and steadier fundamentals, scan a curated list of solid balance sheet and fundamentals (24 results) that may offer a different mix of financial strength than Herc Holdings.
- For readers hunting for quality at a reasonable price, review a hand picked set of 36 high quality undervalued stocks that analysts see as combining solid fundamentals with potentially attractive pricing.
- Income focused investors who want yield alongside robustness can check a 5 dividend fortresses and compare those payouts and balance sheets to what Herc Holdings offers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com