


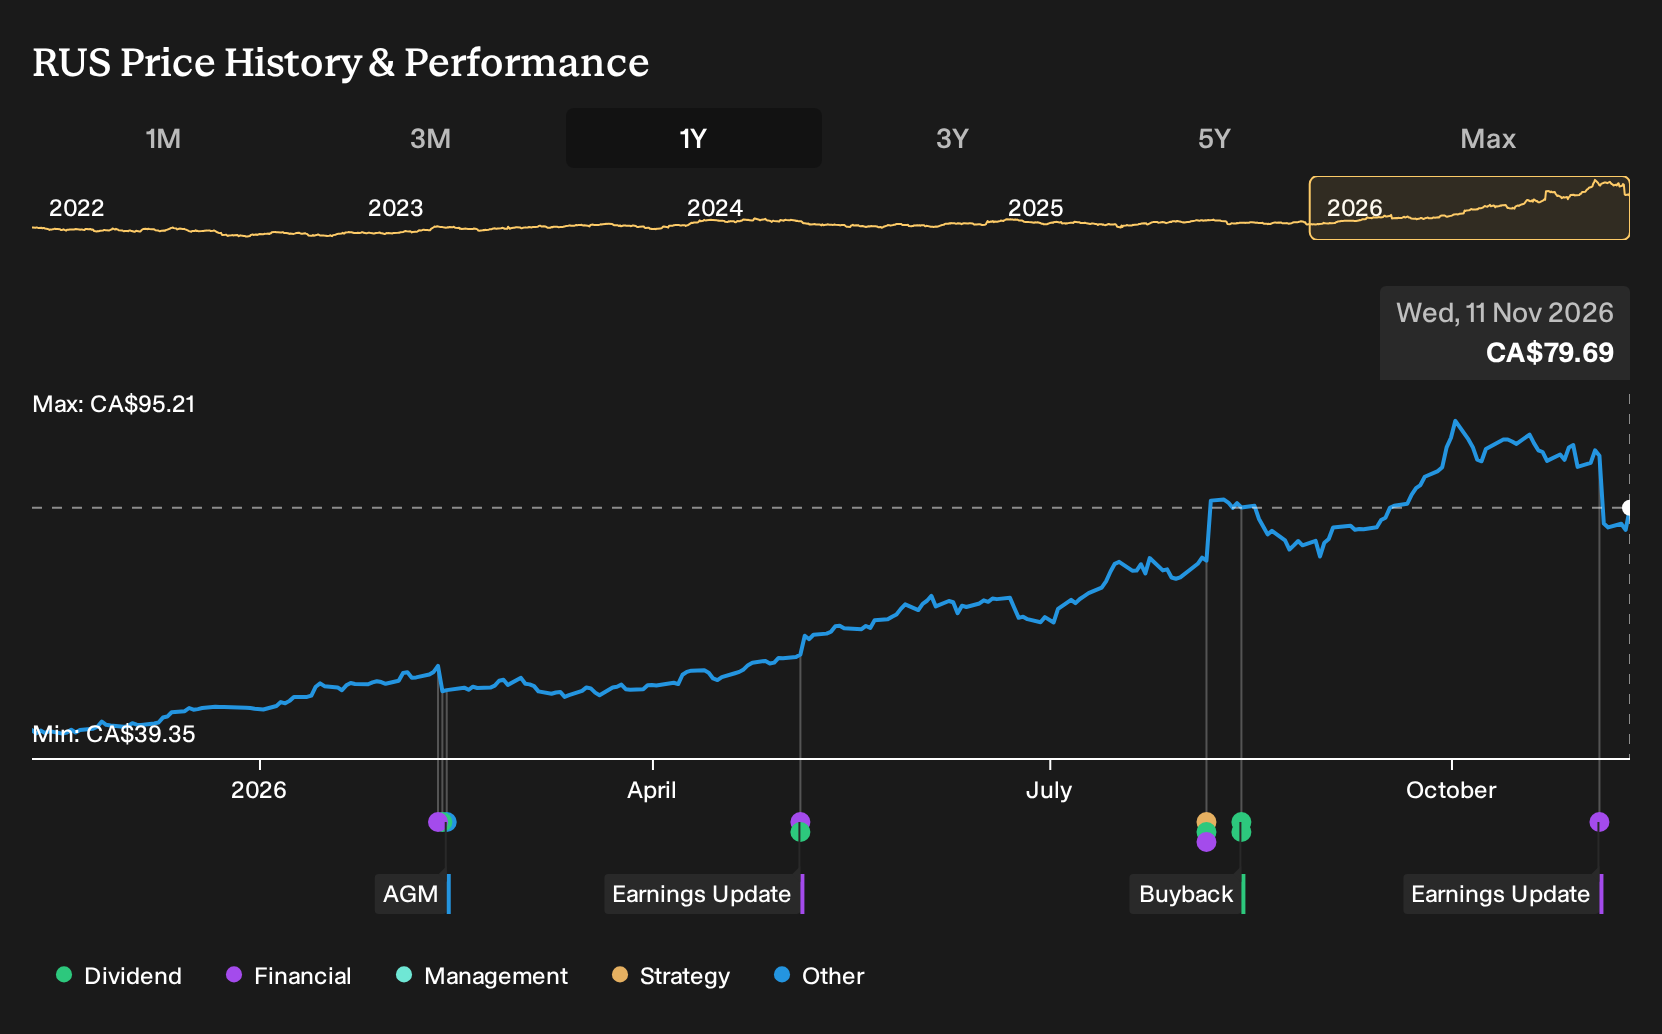
- Russel Metals reported third quarter 2026 results showing sales of C$1,819.1 million and net income of C$125.5 million, with basic and diluted EPS from continuing operations at C$2.29, all higher than the same period in 2025.
- Over the first nine months of 2026, Russel Metals generated C$4,892.4 million in sales and C$275.8 million in net income, reflecting stronger profitability compared with the prior year on both absolute earnings and per share metrics.
- Next, the focus will be on how Russel Metals' sharp year over year increase in quarterly net income may influence the existing investment narrative.
Scan Russel Metals' earnings surge against a curated 5 high quality undervalued stocks that pairs strong fundamentals with prices that may not fully reflect current performance.
Russel Metals Investment Narrative Recap
To own Russel Metals, an investor needs to be comfortable with a metals distributor that leans heavily on construction, energy and industrial demand. The latest quarterly earnings show strong sales and profit for both the quarter and year to date, which supports the analyst consensus Narrative on Simply Wall St that focuses on operational efficiency and value added processing as key levers. The near term catalyst still sits in how well management can sustain volumes and pricing as activity levels shift.
The biggest near term risk remains clear. Management has previously flagged that part of the margin strength comes from temporary inventory cost lag effects that could unwind, on top of exposure to softer purchasing manager data and seasonally lower volumes. The latest profit jump does not remove those pressures. It gives the business more breathing room while it adjusts to demand and potential trade policy swings.
Recent earnings are the most relevant disclosure here. For the nine months to September 30, 2026, Russel Metals recorded C$4,892.4 million of sales and C$275.8 million of net income, with basic and diluted EPS from continuing operations of C$5.02. Those numbers compare with lower sales and earnings a year earlier and align with the narrative that the distributor has been growing profit or revenue recently.
For catalysts, that year to date performance matters because analysts in the analyst consensus Narrative on Simply Wall St expect Russel Metals' revenue to grow 7.4% per year and see the shares trading on a P/E below both the Canadian market and North American Trade Distributors averages. Against that backdrop, the stronger earnings base can help the company absorb cyclicality, address integration and trade risks and still pursue value added and U.S. expansion if volumes or tariffs shift.
Russel Metals' current earnings of CA$197.6 million are set against analyst forecasts for earnings of CA$257.9 million by 2029, an increase of about CA$60 million. That same year is also tied to projected revenue of CA$6.6 billion, supported by an assumed 10.4% yearly revenue growth rate.
Discover why Russel Metals' fair value indicates a 23% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between C$61.50 and about C$75, which illustrates the range of views private investors can hold on Russel Metals. Consider these in the context of the latest earnings jump and the ongoing exposure to cyclical construction and energy demand, and then explore multiple viewpoints before forming your own stance.
Explore another Russel Metals fair value estimate, including one that suggests it could be worth as much as CA$75.01.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Russel Metals research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Russel Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Russel Metals' overall financial health at a glance.
Looking for more Russel Metals sized investment ideas?
If Russel Metals has sharpened your interest in what strong fundamentals can look like in practice, use that momentum to widen your watchlist with a few focused stock shortlists from the Simply Wall St Screener.
- For investors who want quality at a sensible price, start with a curated set of companies that combine robust fundamentals with valuations that may still be catching up by reviewing the 5 high quality undervalued stocks.
- If capital preservation and steadier profiles are a priority, consider companies that screen well on resilience and financial risk by checking the 9 resilient stocks with low risk scores.
- When the goal is to find strong businesses that fewer people are talking about, broaden your opportunity set with a 8 high quality undiscovered gems that highlights underfollowed stocks with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com