


Kimberly-Clark (KMB) has just posted fresh third quarter figures that barely shifted sales yet sharply changed the income line, putting the spotlight on how those earnings details line up with the current share price.
The fresh earnings release landed as Kimberly-Clark’s 1 month share price return of 10.2% pulled the stock toward the upper end of its recent range, despite a 1 day share price decline of 1.73% after the numbers.
That near term momentum contrasts with a 90 day share price return that is down 1.68%, while the 1 year total shareholder return of 9.88% and 3 year total shareholder return of 1.32% point to a more subdued longer run outcome once dividends are included.
Investors have also been digesting the Kenvue acquisition, new debt issuance and board changes in recent weeks, which together may be reshaping how the market prices Kimberly-Clark’s earnings profile and balance sheet risk at the current US$108.84 share price.
Scan how Kimberly-Clark's earnings reset compares with peers by reviewing the hand picked list of solid balance sheet and fundamentals (24 results), which may better balance income resilience and debt loads.
Kimberly-Clark now trades about 8% below the average analyst target after a sharp profit reset and the Kenvue deal. Is that a genuine discount, or a fair warning label on new balance sheet risk?
Most Popular Narrative: 6% Undervalued
Kimberly-Clark's analyst consensus Narrative on Simply Wall St marks out a fair value of $116.33 per share. This sits above the latest $108.84 close and frames the current pullback as a discount that depends on execution of its margin and mix plans.
The main requirement is that Kimberly-Clark converts its productivity program, alternative fiber rollout, and the Arbex and Kenvue initiatives into lasting margin gains without eroding category share, particularly as it aims for price net of cost neutrality.
The current valuation suggests the market is not fully reflecting this narrative’s view that Kimberly-Clark may be undervalued and that its mix shift, structural cost efforts, and portfolio reshaping could support a higher share price over time.
See why 106 investors see Kimberly-Clark as 6% undervalued.
Result: Fair Value of $116.33 (UNDERVALUED)
Still, the narrative can crack if reduced 2026 organic growth guidance and brand pressure in China on diaper quality claims continue to drag on Kimberly-Clark’s volumes and margins.
Find out about the key risks to this Kimberly-Clark narrative.
Another View: What Kimberly-Clark’s P/E Is Telling You
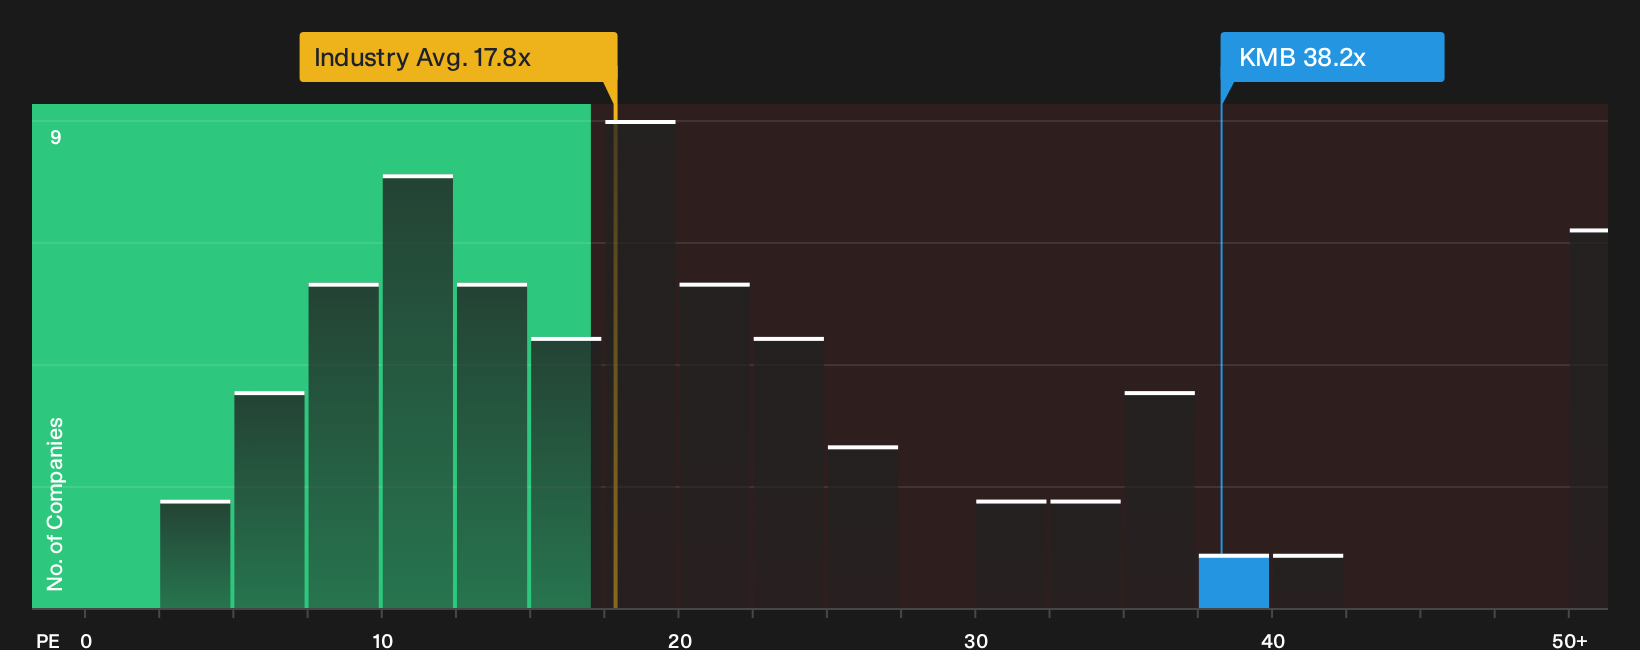
The narrative around Kimberly-Clark leans on a fair value of $116.33, yet the current P/E of 38.2x raises a very different question. That multiple sits above the estimated fair ratio of 31x, the Global Household Products average of 17.8x and a 29x peer group level. A richer valuation like that can signal confidence in the earnings path, or it can leave less room for error if margins or growth assumptions slip.
To understand how much of this gap is explained by fundamentals rather than storytelling alone, it is worth seeing what the numbers say in a structured valuation breakdown. This includes how the fair ratio could act as a gravity point for the P/E over time, via See what the numbers say about this price — find out in our valuation breakdown..
For a clearer visual on how Kimberly-Clark’s current pricing stacks up against industry valuation markers, review the latest comparison in
Next Steps
Mixed about whether Kimberly-Clark’s recent moves add up to an opportunity or a warning label? Put the earnings reset in context quickly and stress test your own view against the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Kimberly-Clark?
Do not stop with Kimberly-Clark alone. Use a few targeted screens to pressure test your thinking and uncover opportunities that better match your risk and income preferences.
- Target resilient balance sheets and steadier fundamentals by running a focused filter using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underappreciated quality by scanning the 32 high quality undervalued stocks that blends stronger cash flows with more conservative pricing.
- Stack your portfolio toward income strength by reviewing a hand picked group of high yield payers through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com