


NEXT (LSE:NXT) reported an 8.1% rise in full price sales for the thirteen weeks to 31 October 2026, alongside updated guidance on fourth quarter trading and full year earnings.
At a £157.9 share price, NEXT has delivered a 30 day share price return of 7.27% and a year to date share price gain of 16.66%, while the 5 year total shareholder return of 127.87% highlights longer term momentum that recent trading updates and guidance tweaks are now testing in the market’s eyes.
Compare NEXT’s latest trading momentum with a hand picked set of retailers showing resilient sales trends and solid balance sheets through our list of solid balance sheet and fundamentals (9 results).
Recent gains in NEXT capture two live stories: a business putting up solid full price sales, and a market reassessing what that consistency is worth. Which one is really driving the current valuation?
Most Popular Narrative: 3% Undervalued
On the analyst consensus Narrative on Simply Wall St, NEXT carries a fair value of £162.95 against the latest £157.90 close, which frames a modest undervaluation and focuses the discussion on what needs to go right operationally.
The main factor that has to go right is that heavy ongoing investment in automated warehousing, AI-enabled systems, and higher marketing spend continues to translate into lower unit costs and profitable online and Total Platform growth, rather than margin pressure.
The anticipation of improved sales in certain international territories, alongside cautious management of surplus cash and strategic acquisitions, is now accompanied by Total Platform subsidiaries that delivered a 40% profit increase and are on track for about a 26% return on capital, which can support earnings growth and cash returns to shareholders.
See why 27 investors see NEXT as 3% undervalued.
Result: Fair Value of £162.95 (UNDERVALUED)
Still, pressure on UK store sales and the hit to retail margins from higher wage costs could quickly challenge the optimistic NEXT valuation narrative.
Find out about the key risks to this NEXT narrative.
Another View on NEXT’s Valuation
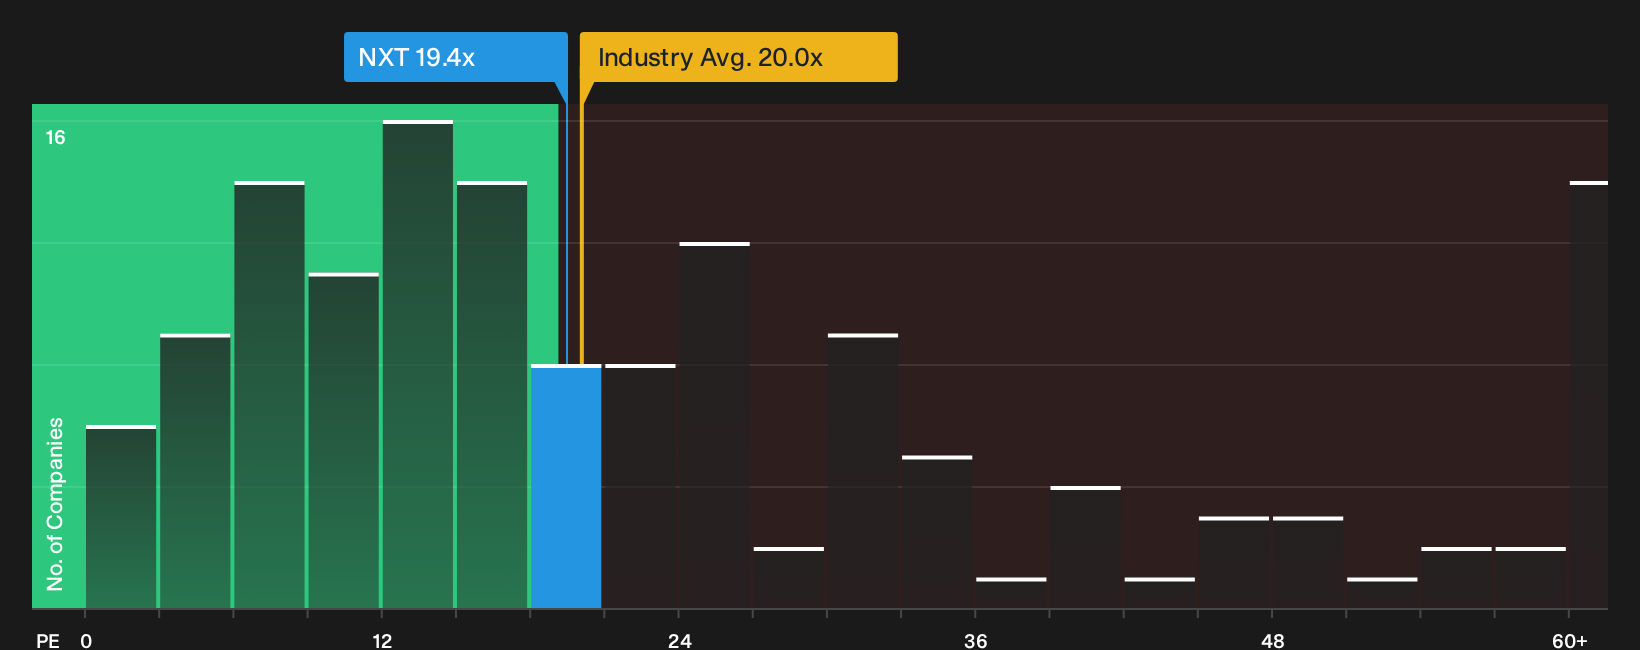
The first narrative suggests NEXT looks about 3% undervalued against a £162.95 fair value. On earnings multiples, the picture is less forgiving. The shares trade on a 19.4x P/E, compared with a 17.6x fair ratio, a 14.3x peer average and a 16.8x UK multiline retail level, which points to some valuation risk if sentiment cools.
When a stock already carries a richer multiple than peers and the fair ratio it could move towards, investors are effectively paying upfront for much of the expected progress. The question is whether the resilience in NEXT’s operations justifies keeping that premium in place or whether a reset toward the lower ratios becomes more likely.
For a closer look at how this earnings multiple stacks up and what the gap to the fair ratio might mean for future returns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of risks and rewards around NEXT feels finely balanced, move quickly to check the underlying data and pressure test the assumptions yourself. To see how both sides of the story line up in one place, start with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond NEXT?
Once you have weighed up NEXT, broaden your watchlist with fresh angles so you do not miss opportunities that match your style and risk comfort.
- Target value opportunities using a curated set of companies trading below their assessed worth through the 17 high quality undervalued stocks.
- Strengthen your income focus by finding businesses with robust yields through the 4 dividend fortresses.
- Prioritise resilience by screening for companies with lower risk profiles and steadier fundamentals using the 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com