


Endeavour Silver (TSX:EDR) just posted a sharp earnings swing for Q3 2026, moving from a loss to a profit on higher sales and updated silver and gold production guidance.
The Q3 swing back to profit has arrived after a choppy year for Endeavour Silver, with the share price down 19.4% over 90 days and 6.7% year to date, yet supported by a very large 3-year total shareholder return of about 3x. Recent catalysts include the strong Q3 beat on earnings and revenue, revised 2026 production guidance for silver and gold, and a new revolving credit facility of up to US$100 million that gives the miner more flexibility to fund projects like Pitarrilla while investors reassess both growth potential and risk around its expanding mine portfolio.
Scan beyond Endeavour Silver and compare its Q3 turnaround against hand-picked peers in the precious metals space with the 10 top silver producer stocks.
After a sharp earnings rebound and a share price still well below both fair value estimates and analyst targets, is Endeavour Silver cheap for a reason, or has caution been pushed too far?
Most Popular Narrative: 23% Undervalued
On the bearish analyst Narrative on Simply Wall St, Endeavour Silver screens as undervalued, with a Fair Value of CA$15.00 against a last close of CA$11.58. The key question is how much of that gap you think is justified by execution and cost risks.
Although Endeavour Silver now has the liquidity and credit facilities to pursue Pitarrilla and other growth projects, the plan to reinvest cash flow alongside an estimated US$500 to US$600 million build cost before considering dividends or buybacks points to a prolonged period where equity holders may see limited cash returns, even as capital intensity pressures free cash flow.
See why 1 investors see Endeavour Silver as 23% undervalued.
Result: Fair Value of CA$15.00 (UNDERVALUED)
Still, stronger than expected production and cleaner execution at Guanaceví or Terronera could challenge this cautious Endeavour Silver narrative and reset expectations around costs and reliability.
Find out about the key risks to this Endeavour Silver narrative.
Another View: What Multiples Say About Endeavour Silver
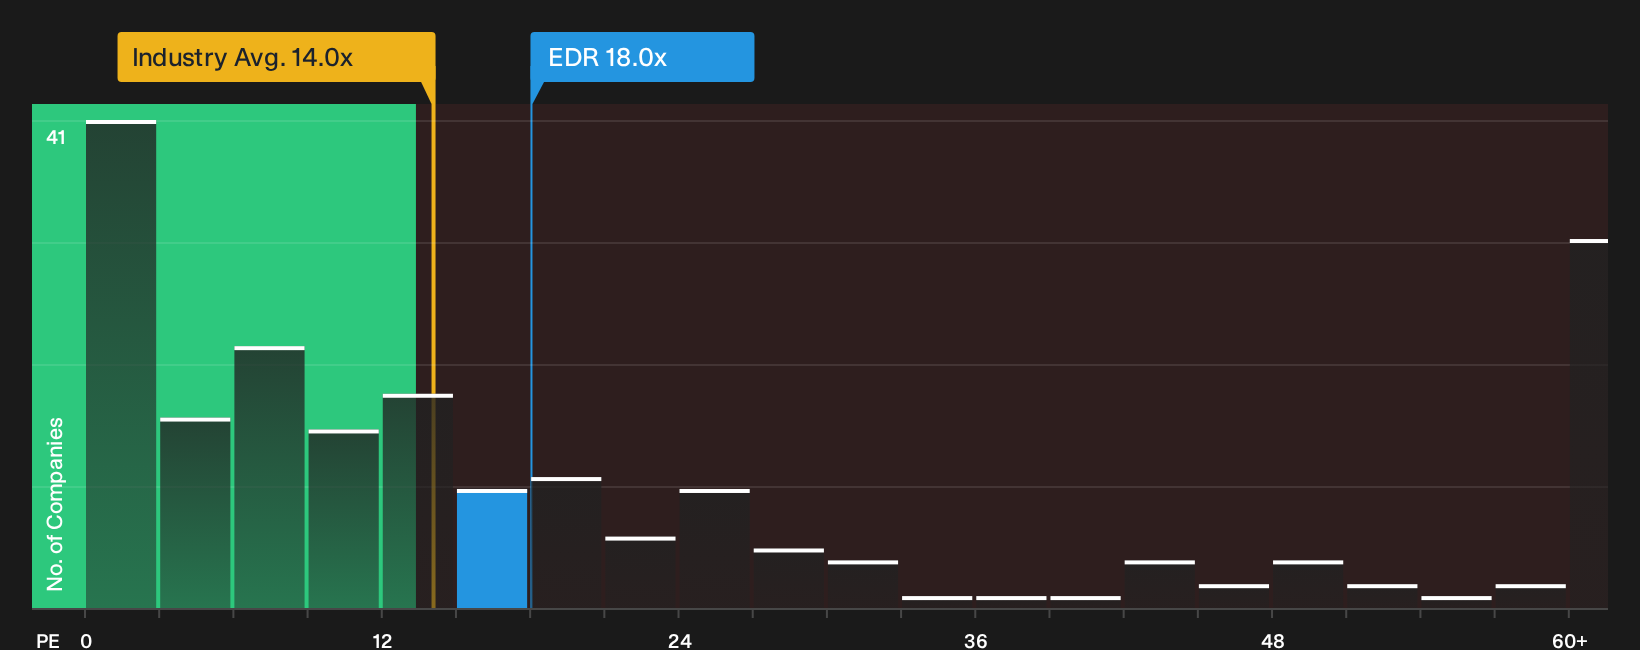
Fair value models point to Endeavour Silver trading below intrinsic worth, yet the market is not giving the stock away cheaply. At a P/E of 18x versus a fair ratio of 16.2x and an industry average of 14x, the shares carry valuation risk if expectations soften or execution stumbles.
For a closer look at how that gap between current P/E, peers and the fair ratio could close in either direction, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on Endeavour Silver leaves you unsure, rely on the numbers, act promptly while the data is fresh, and test your own thesis with the 3 key rewards
Looking for more investment ideas beyond Endeavour Silver?
If Endeavour Silver has sharpened your focus, do not stop here. Broader opportunity often shows up where you are not currently looking.
- Expand your opportunity set with resilient businesses that pair strong balance sheets with durable fundamentals through the list of solid balance sheet and fundamentals (5 results).
- Target potential mispricings by scanning companies that combine quality metrics with discounted valuations using the 5 high quality undervalued stocks.
- Strengthen income potential by searching for reliable cash distributions and higher yields through the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com