


Vistry Group has spent this year in the headlines for restructuring plans, debt reduction efforts, and a reshaped land bank, all while searching for a new finance chief after reporting a large goodwill impairment. Investors who held Vistry Group over the past year are down 61.9%, including dividends. If you had committed fresh money back on 11 November 2025, how should you now think about a smaller, cash focused business that is still reliant on government backed housing partnerships?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Vistry Group harder to judge, start where the gap is still open and scan 17 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Vistry Group
The shares cost £6.68 at the start of the period, and you had to decide which future for Vistry Group felt more convincing.
The bullish case pointed to a Fair Value of £7.73 and focused on UK affordable housing demand, with analysts assuming revenue could rise 11.9% a year and margins lift from 2.0% to 6.1% by 2028.
The more cautious view put Fair Value at £6.23 and accepted partnerships growth, while stressing high net debt and ongoing building safety cash outflows as central risks.
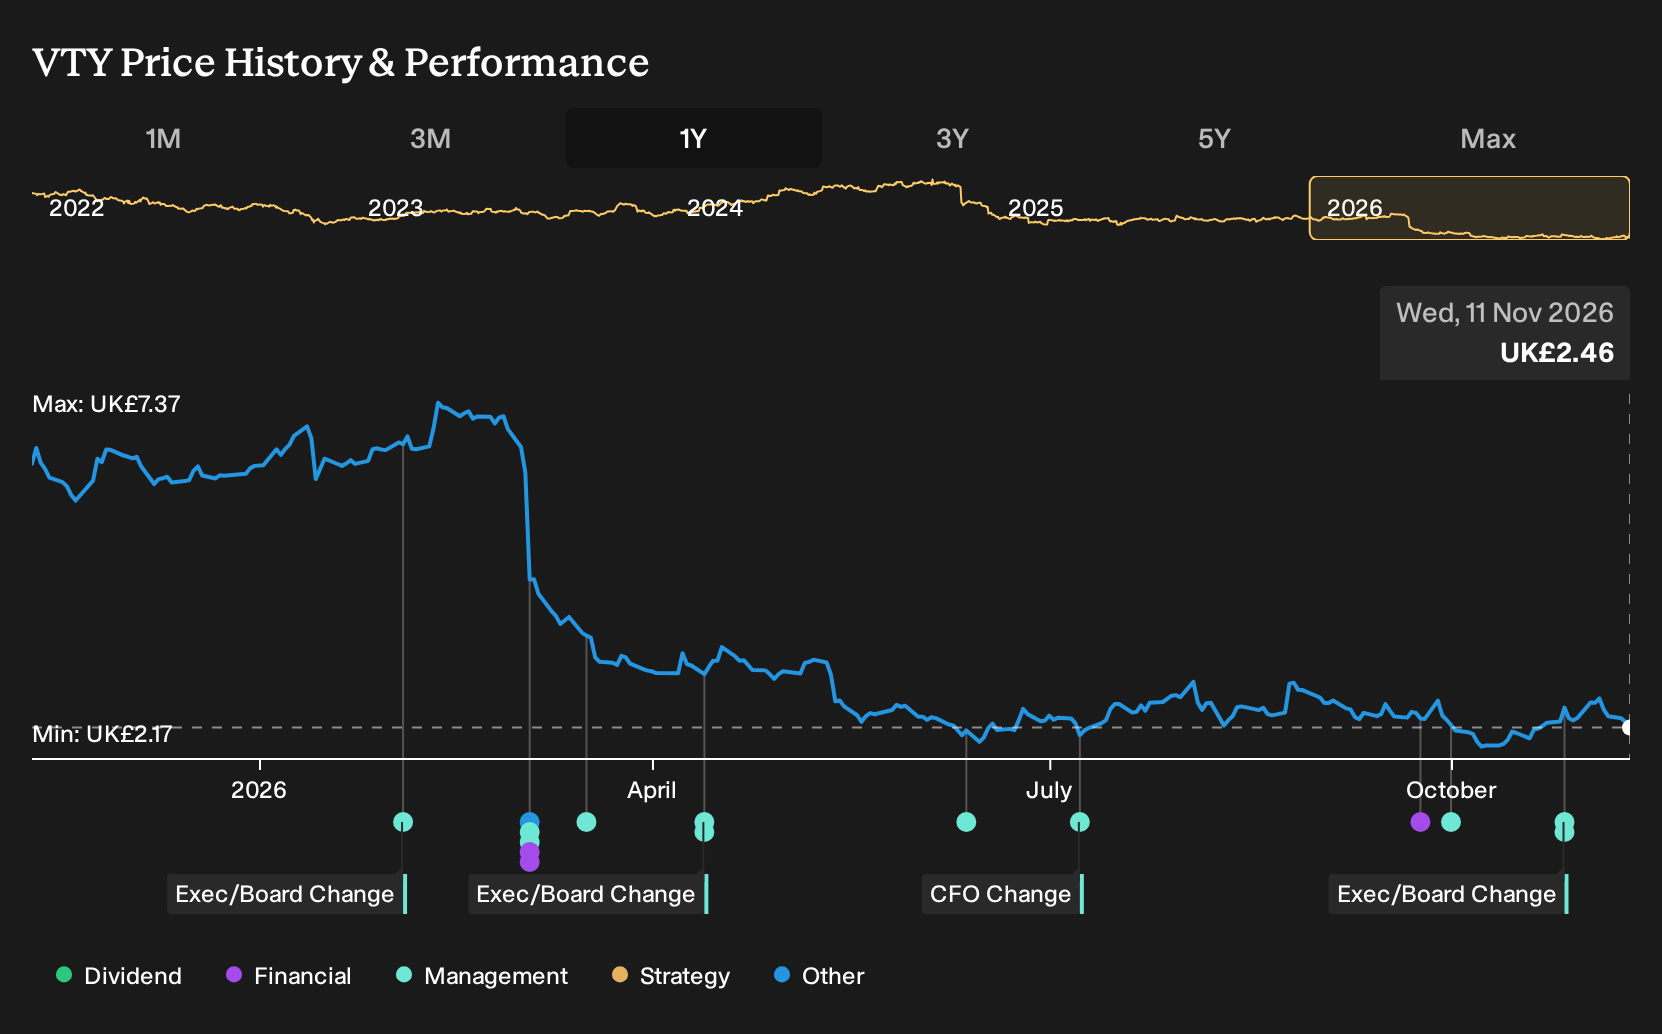
What The Results Put To The Test For Vistry Group
For Vistry Group, the clearest fresh fact was the swing in profitability. H1 2026 net income moved from a £31.3 million profit in H1 2025 to a £607 million loss, with net margin falling from 1.9% to 42.8% in the red. That undercut both the bullish and cautious margin improvement stories, even as the business pressed on with restructuring and debt reduction plans.
The lesson is that any upbeat story about a margin rebuild lives or dies on reported net income and net margin. When you test a similar pitch elsewhere, track whether losses are shrinking or expanding and whether management actions show up in that bottom line within a reasonable period.
What You Would Be Paying For In Vistry Group Today
Vistry Group now trades at £2.46, after a 61.9% loss over the past year, and the bullish analyst Narrative on Simply Wall St sees Fair Value above that market level.
This Narrative leans on more partnership sites reaching stronger margin territory and assumes buyers today weigh whether that execution shift is realistic.
"The main thing that has to go right is consistent execution of the simplified 12 region structure and Linden product range so that more of the 12,000 unit medium term target delivers the 12% operating margin and greater than 30% ROCE that management is aiming for."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 24% below our estimate - builds recurring software tools that automate testing, security checks and payroll compliance for enterprise workflows.
- Company 2 - 31% below our estimate - manages capital that flows into renewable infrastructure projects, private equity deals and listed real asset strategies.
- Company 3 - 28% below our estimate - runs low cost investment platforms as customers shift savings and advice relationships onto mobile tools.
Three companies from the same screener. Open every one of the 9 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com