


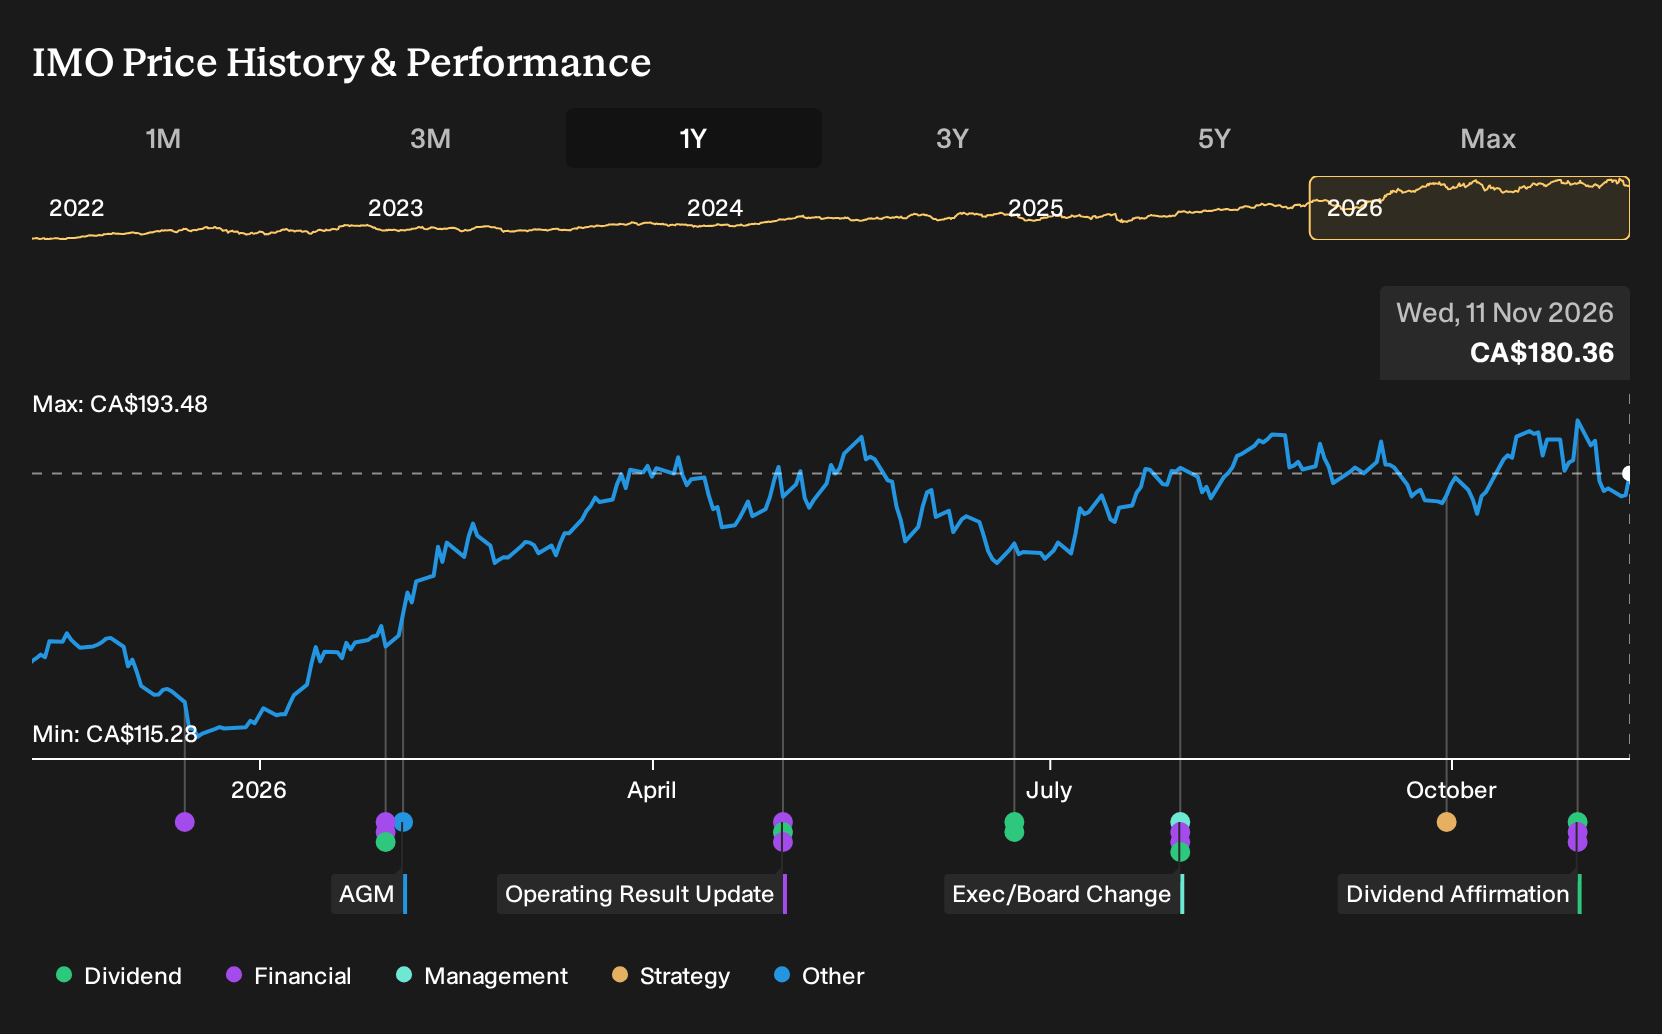
- Imperial Oil reported third quarter 2026 sales of C$16,205 million and net income of C$2,454 million, alongside oil equivalent production of 418,000 barrels per day, and affirmed a quarterly dividend of C$0.87 per share payable on January 1, 2027.
- The combination of higher earnings per share, strong nine month profitability and an active C$2,086 million buyback that retired 2.4% of shares highlights Imperial Oil's focus on cash returns, even as production volumes shifted year on year.
- We will look at how Imperial Oil's investment narrative lines up with this sharp jump in third quarter net income and earnings.
Scan beyond Imperial Oil's latest dividend and earnings jump and size up other cash generative operators with the 5 high quality undervalued stocks that pair balance sheet strength with disciplined capital returns.
Imperial Oil Investment Narrative Recap
To own Imperial Oil, you need to be comfortable with a long life oil sands and refining story where efficiency and cost control matter more than headline volume growth. The analyst consensus narrative on Simply Wall St leans on technology and process gains at Kearl and Cold Lake, along with restructuring, to keep margins resilient. The latest quarter shows earnings power at current utilization, while the near term catalyst still sits in hitting those unit cost and overhead targets rather than chasing higher output.
The biggest operational risk right now is that heavy maintenance needs at Kearl, Syncrude and Cold Lake absorb more cash than expected and squeeze room for future projects or emissions spending. Third quarter production volumes were lower than a year ago, so any further reliability issues or tighter emissions rules would pull against that margin focused narrative without changing it overnight.
The buyback update is the most relevant piece of news for this story. Imperial Oil retired 11,600,000 shares for C$2,086 million in the quarter, taking out 2.4% of the equity base. For a business where analysts already see modest revenue pressure over the next few years, that shrinking share count can matter a lot for per share metrics and for your thesis on capital discipline.
That capital return sits alongside the reaffirmed C$0.87 quarterly dividend and the strong third quarter and nine month earnings that funded both. It also intersects with the key catalysts around Kearl efficiency, Cold Lake solvent projects and the restructuring program. If those projects hold operating costs in check while production stays broadly stable, sustained buybacks could remain a meaningful part of the Imperial Oil investment case.
Imperial Oil's analyst narrative points to CA$53.3b in revenue and CA$5.0b in earnings by 2029. This outlook is built on an assumed 1.1% yearly increase in sales and an earnings uplift of about CA$0.8b from the CA$4.2b reported today.
Uncover why Imperial Oil's fair value signals an 8% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Imperial Oil’s buyback and cash return track record rather than maintenance risk. Before this earnings jump, they were modelling roughly CA$76.1b of revenue and CA$5.6b of earnings by 2029. You can treat this dividend affirmation and profit surge as fresh information that might reshape those views in either direction.
Explore 3 other Imperial Oil fair value estimates, including one that suggests as much as 44% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Imperial Oil research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Imperial Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Imperial Oil's overall financial health at a glance.
Looking for more ideas beyond Imperial Oil?
If Imperial Oil has sharpened your focus on cash generation and disciplined capital allocation, it can help to line it up against other candidates that fit your style. The Simply Wall St Screener lets you scan the market for companies that match the mix of quality, resilience and income you care about, rather than whatever happens to be in the headlines today.
- Prefer stability and defense first? Filter for sturdier businesses and stress test your watchlist with a 9 resilient stocks with low risk scores that keeps downside risk in focus.
- Want stronger balance sheets next to Imperial Oil in your portfolio? Build a shortlist using the list of solid balance sheet and fundamentals (5 results) to see which operators pair financial strength with consistent execution.
- Hunting for future standouts before the crowd pays attention? Run a screen across the 8 high quality undiscovered gems and see which stories deserve a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com