


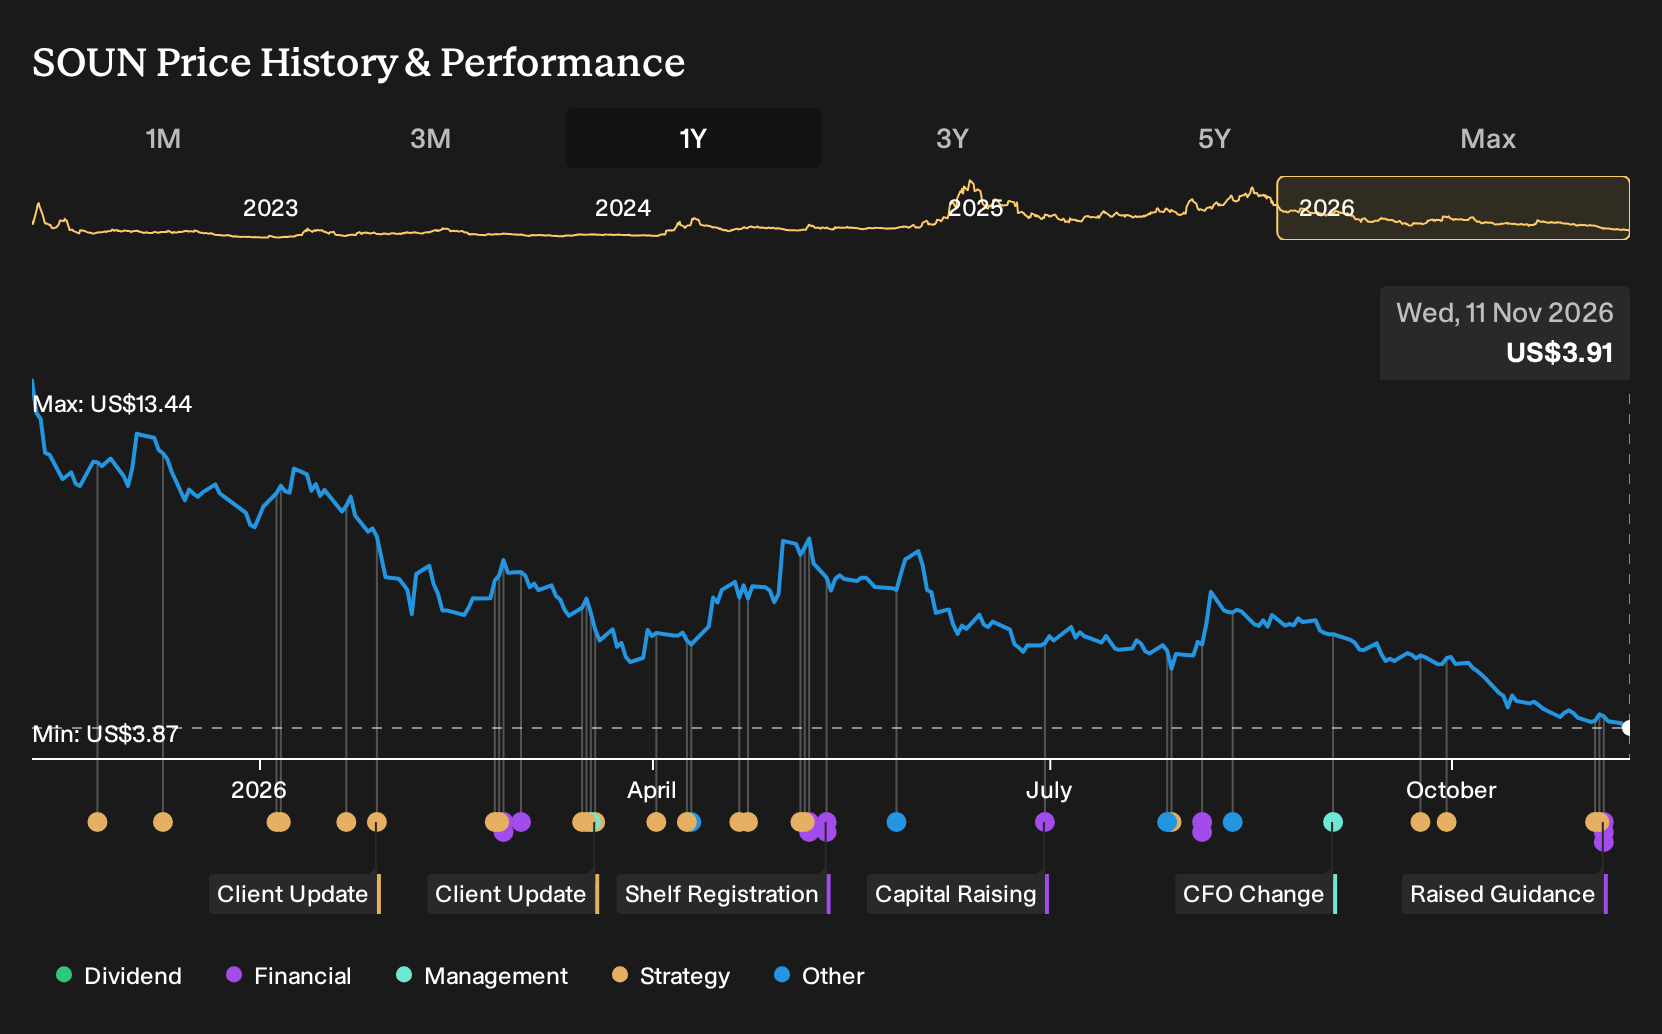
- SoundHound AI reported third quarter 2026 sales of US$62.43 million with a net loss of US$46.37 million and raised its 2026 revenue outlook to a range of US$250 million to US$260 million, while also issuing 2027 revenue guidance of US$350 million to US$400 million.
- Management is reshaping SoundHound AI’s earnings profile by targeting at least US$120 million in annualized cost savings after the LivePerson acquisition and by reducing reliance on one-time license deals in favor of recurring revenue.
- This article examines how SoundHound AI’s investment narrative intersects with its cost savings initiatives following the LivePerson acquisition and its 2027 targets.
Scan how other AI players are priced and positioned by sizing up our curated list of 39 AI small caps that share themes with SoundHound AI's voice and agentic platforms.
SoundHound AI Investment Narrative Recap
To own SoundHound AI today, you need to be comfortable with an unprofitable, fast-scaling operation that is leaning on cost cuts and integration to reshape its earnings profile. Management is targeting at least US$120 million in annualized savings and is guiding to sustainable positive adjusted EBITDA in the second half of 2027. The key near term catalyst is clear execution on integration and recurring revenue mix. The biggest risk remains ongoing losses and potential funding or dilution pressure if that path slips.
According to DanielOliveira, an investor in the Simply Wall St Community, the crux of the story is how investors read the next few quarters rather than a long term valuation debate. That lens still applies after Q3 2026. Revenue guidance for 2026 and 2027 sets explicit hurdles, so any wobble on subscription momentum or slippage on the cost program could weigh heavily on sentiment.
The LG Electronics partnership is one recent announcement that slots neatly into the current catalyst mix. SoundHound AI is working to extend restaurant and merchant ordering into roughly 20 million LG Smart TVs in the US, using its existing merchant network and transaction routing stack. For a business trying to lean into recurring, transaction linked income, this is a practical test of that thesis.
Investors watching the Q3 miss against analyst expectations, the tightened 2026 guidance and the 2027 revenue range will likely connect those numbers to execution on deals like LG. Uptake by large restaurant chains and smooth integration with point of sale systems could support the revenue ambition. Slow merchant adoption or technical friction would raise questions about how quickly newer channels can offset reliance on one time license activity.
For fair value, the narrative from DanielOliveira simply pins SoundHound AI at US$4.12 because the model is not trying to price long term cash flows. It presents US$4.12 as a marker for interpreting the next two quarters, rather than treating it as a full valuation exercise.
Uncover why SoundHound AI's fair value indicates a 5% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One big swing factor bullish analysts focus on is revenue potential. Before this Q3 update, the most optimistic group was modeling SoundHound AI reaching about US$506.1 million of sales and US$59.5 million of earnings by 2029, which supported a US$17.00 target. Those forecasts did not yet factor in the latest guidance shift, so you may see opinions move as new data lands.
Explore 4 other SoundHound AI fair value estimates, including one that suggests as much as 117598% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your SoundHound AI research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SoundHound AI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SoundHound AI's overall financial health at a glance.
Looking for more investment ideas beyond SoundHound AI?
If you want to stress test your thesis on SoundHound AI, a smart next step is to line it up against other opportunities that match your risk profile, income needs, or balance sheet preferences. The Simply Wall St Screener can help you quickly surface stocks that share some of the qualities you care about, without relying on headlines or hype.
- For investors hunting for potentially mispriced opportunities with stronger financial quality, start by scanning our curated set of 32 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and calmer drawdowns matter more to you than excitement, you can filter for 30 resilient stocks with low risk scores that score well on resilience and lower risk profiles.
- Readers who care most about balance sheet strength and fundamentals can shortlist companies using the list of solid balance sheet and fundamentals (24 results) to see which businesses look better equipped to handle bumps in the cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com