


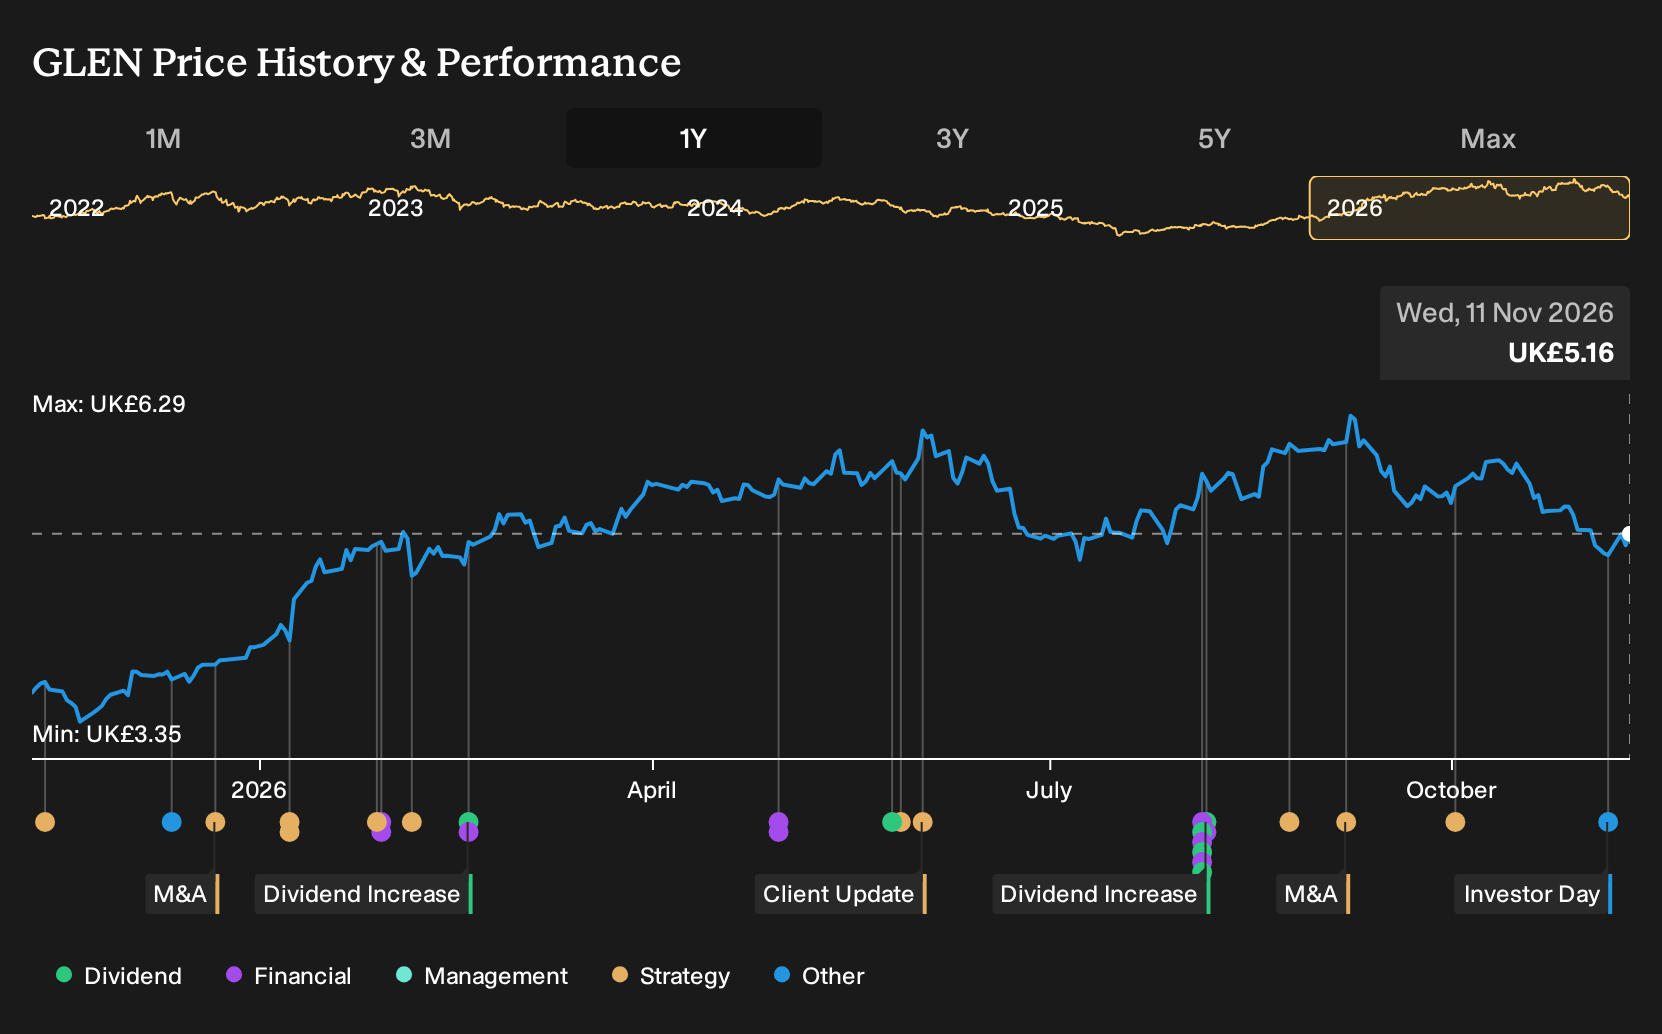
- Glencore has recently been highlighted in separate industry reports on e scrap and non ferrous scrap recycling, as miners benefited from higher metals prices supported by a weaker US dollar and easing bond yields in London trading.
- The focus on recycling critical raw materials and non ferrous scrap points to Glencore’s growing role in supplying secondary metals, as regulators push for more sustainable sourcing and tighter control of electronic waste flows.
- This article examines how Glencore's investment narrative is affected by stronger metals pricing tied to a weaker US dollar and improved sentiment.
Scan beyond Glencore to track other recyclers tied to metals pricing and e scrap momentum with our curated list of 33 best rare earth metal stocks
Glencore Investment Narrative Recap
To own Glencore, you need to buy into a story where copper growth, marketing earnings and now recycling scale together to offset swings in commodity prices. The analyst consensus Narrative on Simply Wall St leans on that mix. Recent support from higher metals prices tied to a weaker US dollar helps sentiment, but it does not fundamentally change the central copper and cost execution test.
The biggest short term catalyst remains Glencore hitting volume and cost targets in core copper operations while keeping the marketing arm inside its guided EBIT range. The key risk is renewed commodity price softness while fuel and reagent costs stay high, which has already shown up in adverse cost variance and would squeeze industrial margins again.
The most relevant development here is Glencore being flagged in global reports on e scrap and non ferrous scrap recycling. Those markets are projected to reach about US$74.4b and US$70.8b respectively by 2032, pointing to a larger pool of secondary metals where Glencore already participates, especially in copper and other critical raw materials.
For catalysts, that recycling exposure ties directly into the longer term copper growth and cost story. More access to secondary feedstock could help volume resilience if mined output faces regulatory or geopolitical friction. The flip side is execution risk. Scaling complex recycling and meeting tighter environmental rules adds capital needs on top of existing copper and coal commitments.
Glencore is framed around analyst expectations that revenues will reach about US$274.1b and earnings will be about US$7.3b by 2029. This implies a yearly revenue decline of 3.5% and an earnings increase of roughly US$1.9b from current earnings of about US$5.4b.
Uncover why Glencore's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on copper cost cuts and more on Glencore’s potential recycling upside. Before this e scrap news, they were already pencilling in revenue of about US$362.2b and earnings of US$10.8b by 2029. That is far above consensus, and this latest market spotlight could push opinions even further apart.
Explore 4 other Glencore fair value estimates, including one that suggests as much as 52% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Glencore research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Glencore. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Glencore's overall financial health at a glance.
Looking For More Investment Ideas Beyond Glencore?
If you want to stress test your thesis on Glencore and see how it stacks up against other opportunities, cast the net wider with the Simply Wall St Screener and compare different types of businesses side by side.
- If you care most about valuation support and balance between quality and price, scan through 17 high quality undervalued stocks that pass tight fundamental checks.
- For investors who prioritise resilience and want to sleep well at night, filter for companies in the 5 resilient stocks with low risk scores and see which ones fit your preferred risk profile.
- When you are hunting for under followed opportunities with solid fundamentals, shortlist ideas from the 5 high quality undiscovered gems to expand your watchlist beyond the usual large caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com