The Zhitong Finance App learned that CITIC Securities released a research report saying that the global economy remains resilient this year, the situation in the Middle East is showing the dawn of peace, and the blue wave of the midterm elections is expected to influence the market's narrative trend next year. The US economy is expected to grow more evenly and moderately next year, domestic demand in the EU should continue to expand, and the Japanese economy is expected to recover. The impact of the oil price shock will weaken next year. The overall inflation rate in Europe and the US may fall after experiencing a sluggish peak, and Japan's apparent inflation rate will be clearly suppressed by policies. European and American central banks are close to the end of the current rate hike cycle, while the Bank of Japan may raise interest rates quarterly until the first half of next year. The US federal government's deficit rate is expected to be generally stable, data center construction will face stronger restrictions at the state level, and there is a risk that France's fiscal consolidation will fall short of expectations. US stocks may be more suited to the strategy of falling out next year. They prefer a balanced allocation approach. US bond interest rates and the US dollar index have a slight downside, and gold prices are expected to recover as expectations of liquidity contraction weaken.
Economic growth: Momentum is more moderate.
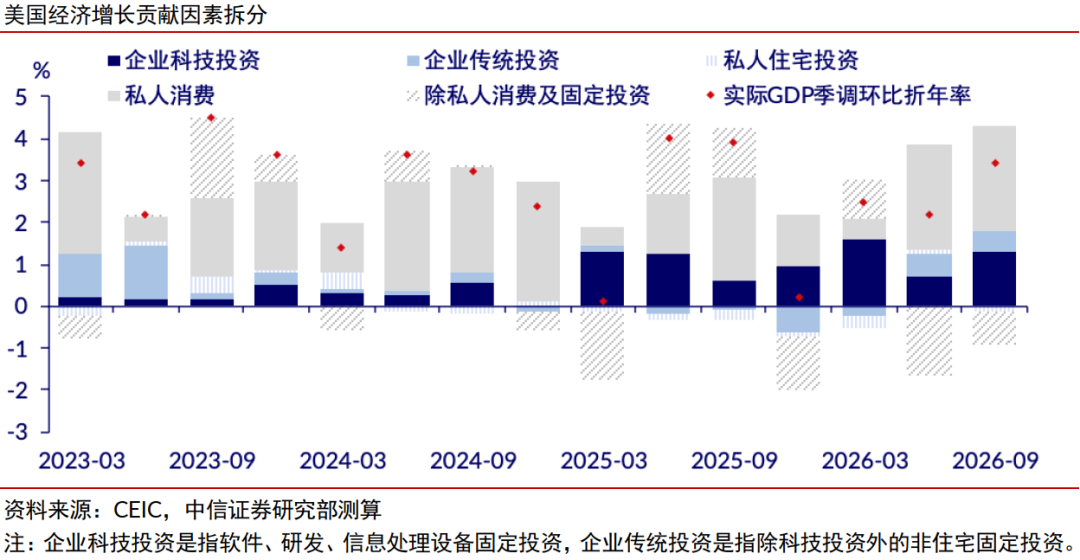
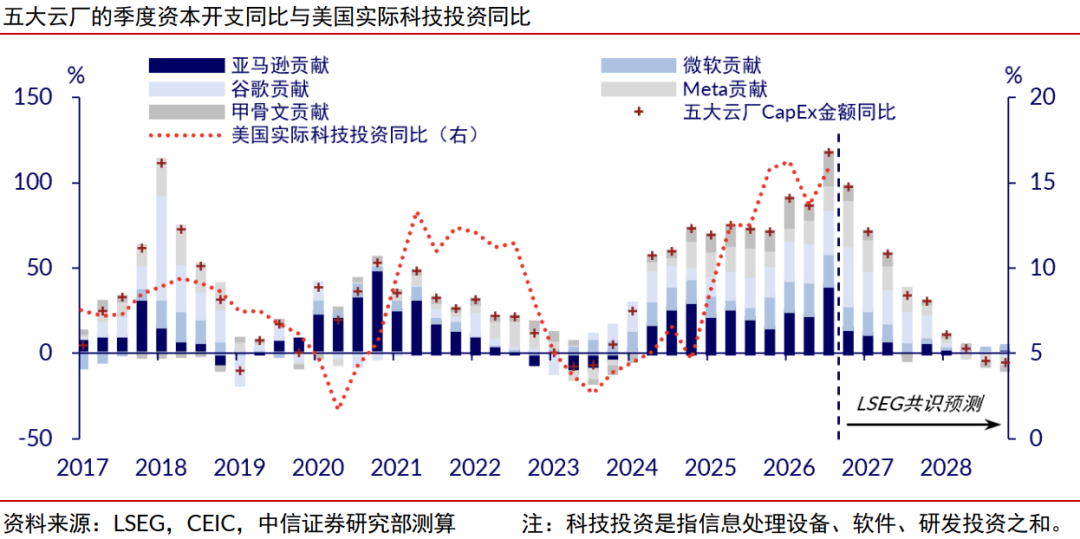
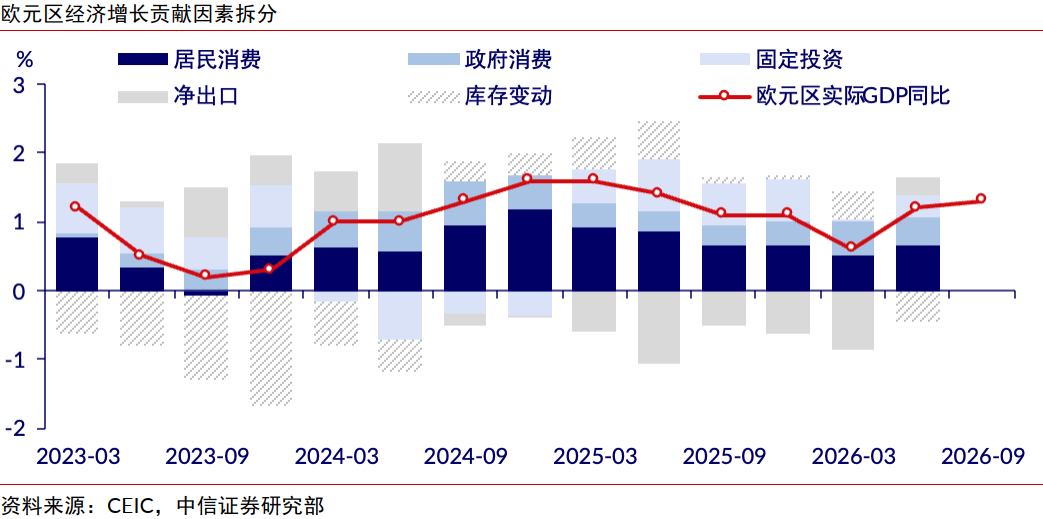
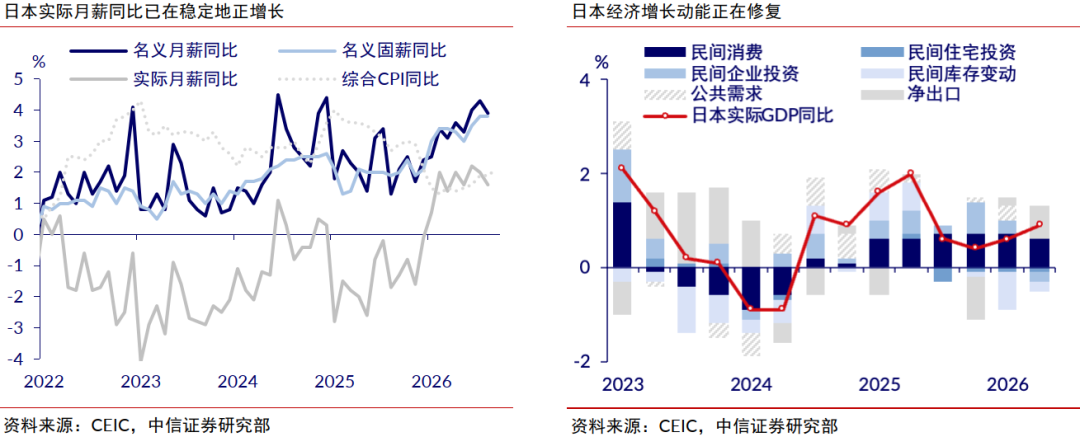
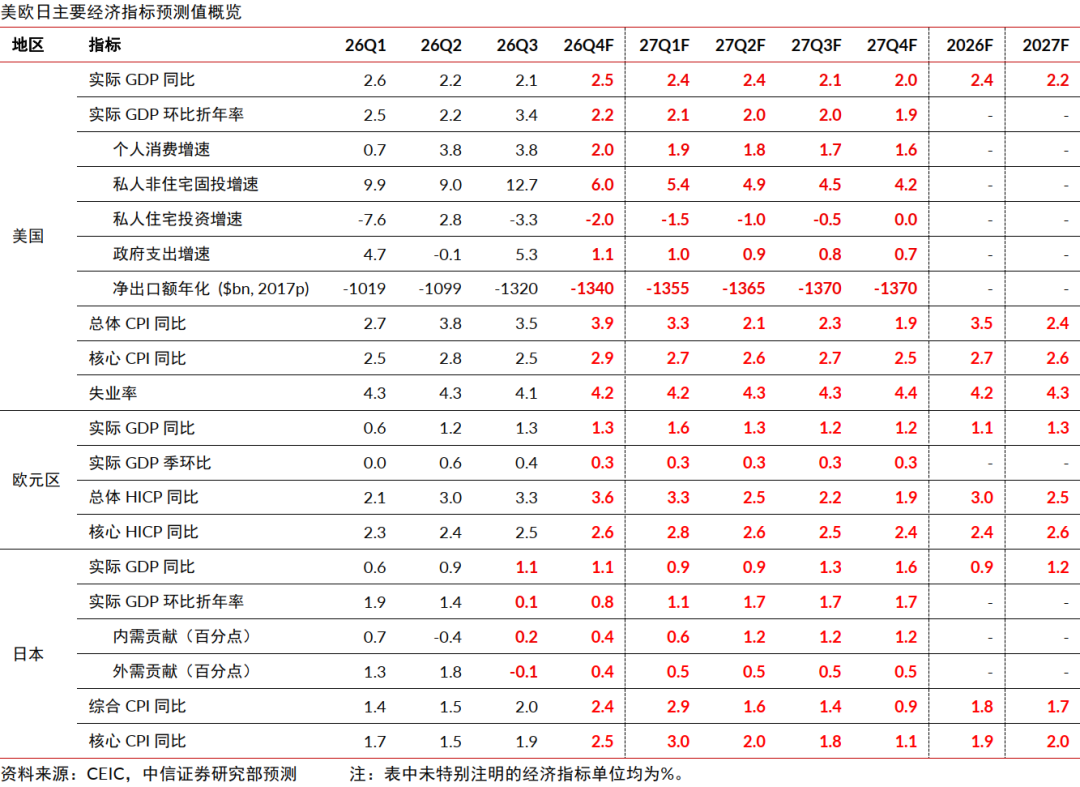
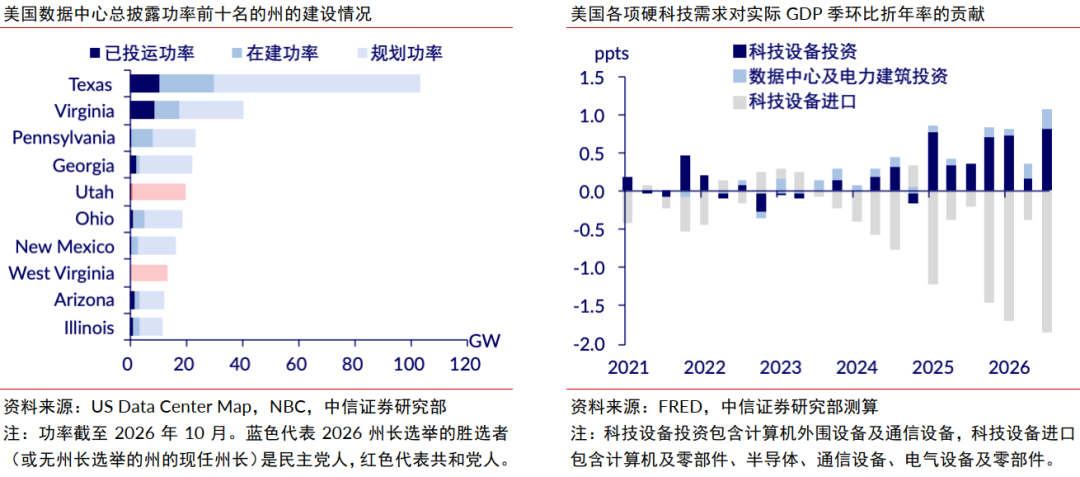
CITIC Securities anticipates that the growth momentum of the US economy next year will be more moderate and the demand structure will be more balanced. The technology investment boom should cool down under a stricter financing and regulatory environment, traditional commercial investment is expected to recover, housing investment is expected to remain weak, consumption momentum may slow slightly, and the vitality of the labor market may decline slightly. Domestic demand in the EU should continue its steady expansion trend, and the trade deficit with China may narrow as trade barriers are implemented. The Japanese economy may recover as the energy shock wanes, and the continued tight job market will support the momentum for wage increases and the demand for investment in enterprise automation.
Inflation: Fears will abate.
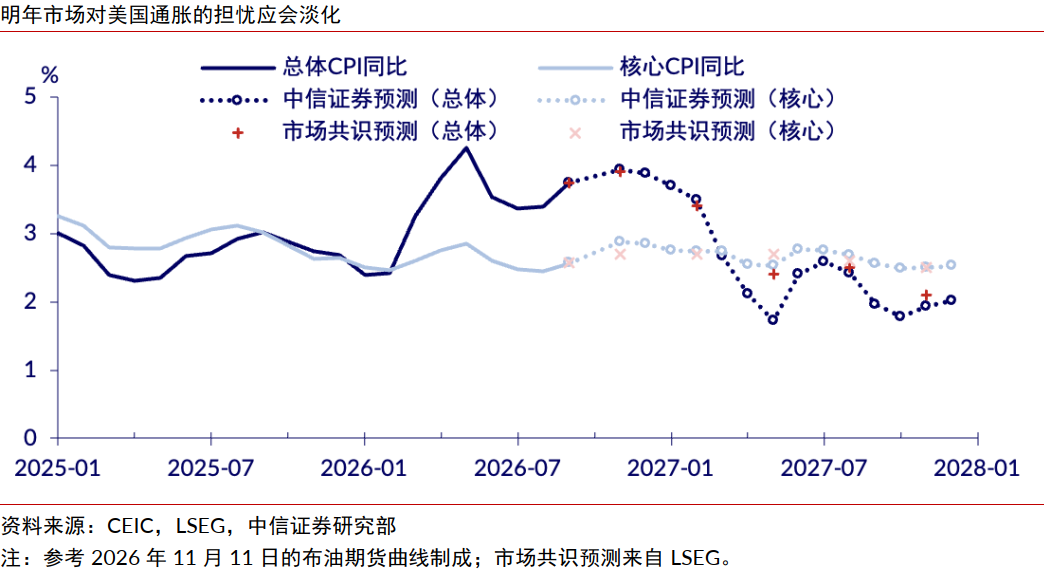
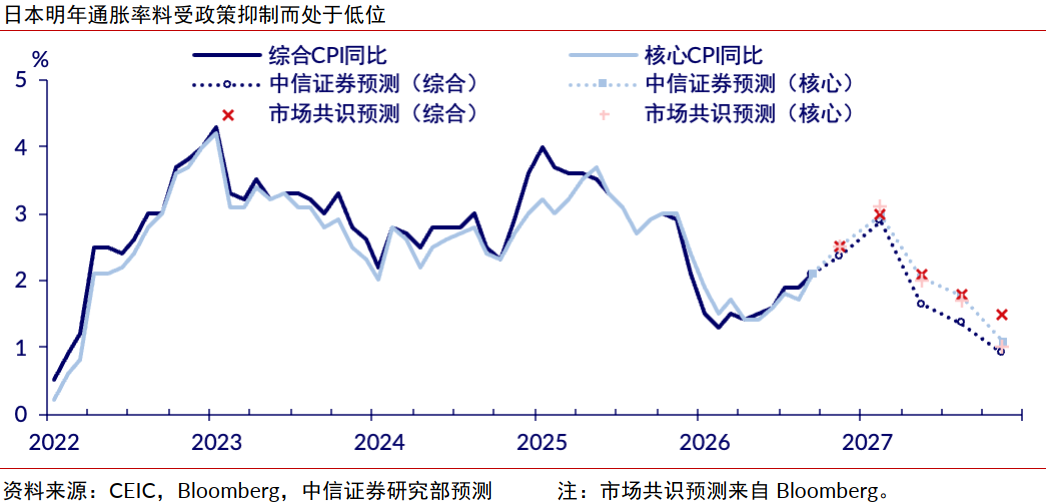
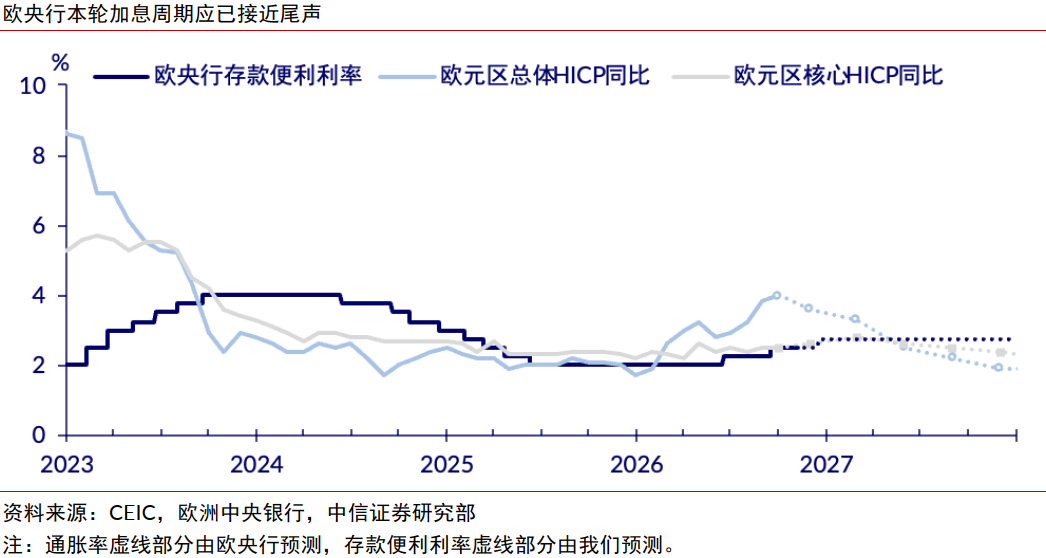
The oil price center is more likely to fall back rather than rise, and there is little risk that core inflation will accelerate again. We expect the overall US CPI to peak at 26Q4 year on year. Starting next March, it is expected to decline rapidly due to the base effect, and then enter a moderate phase of fluctuation. The Eurozone wage growth center is expected to remain steady, and the decline in the overall inflation rate should only be a matter of time. The positive cycle of price and wage increases in Japan is expected to continue for a long time. The apparent inflation rate is expected to be low from 27Q2 due to obvious suppression of food tax cuts, and will show a clear trend of high and back throughout the year.
Economic policy: Clearer borders.
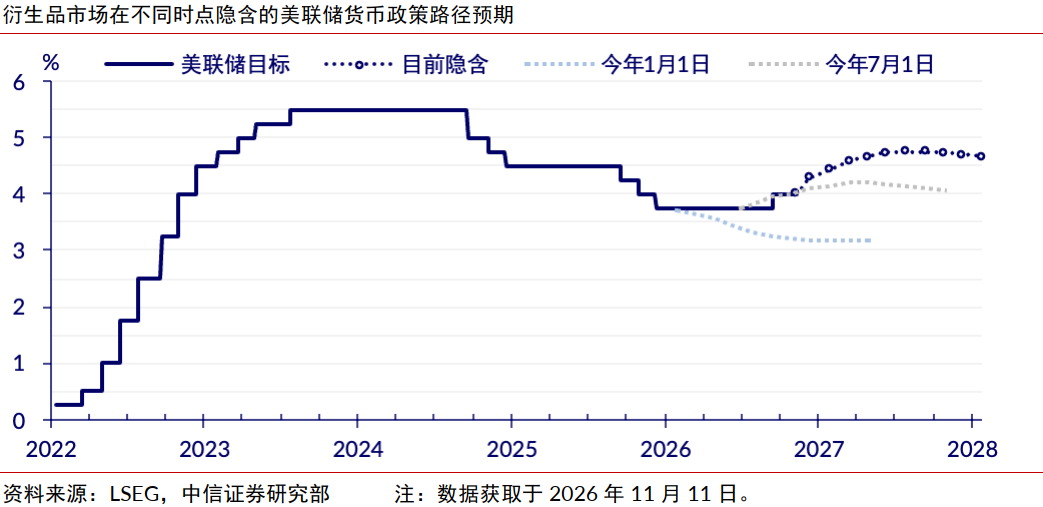
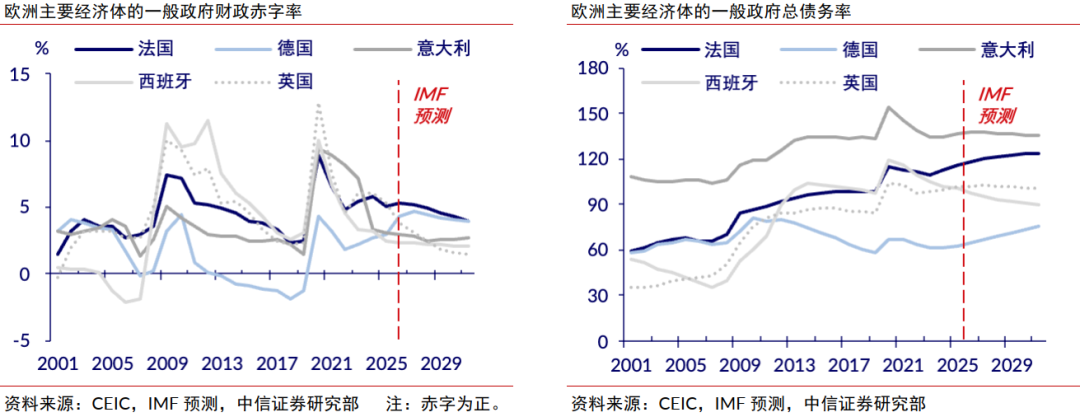
The European and American central banks are close to the end of the current rate hike cycle. We expect the Federal Reserve to raise interest rates at most once next year after raising interest rates by 25 bps in December this year, the ECB will end this round of interest rate hikes after raising interest rates by 25 bps in December this year, and the Bank of Japan may maintain a quarterly rate hike of 25 bps until the first half of next year. The US political arena will enter a stage of high internal consumption after the Democratic Party sweeps through both houses, and data center construction will face stronger restrictions at the state level. We believe that states are more likely to adopt appropriate systems to resolve the negative externalities of related projects rather than putting the approval process on hold for a long time. America's fiscal expansion capacity next year is insufficient, and the will to consolidate its fiscal consolidation is not strong. The federal government's deficit rate is expected to stabilize around 6%, and the debt limit issue does not pose much of a risk. The Eurozone's overall fiscal position may be tightened next year. Among them, France should consolidate its finances, but there is a risk that it will fall short of expectations, while Germany's fiscal expansion is expected to continue. Japan's high cabinet's tax reduction plan is under pressure to implement financial resources, and uncertainty about fiscal financing may continue to support interest rates on Japanese bonds.
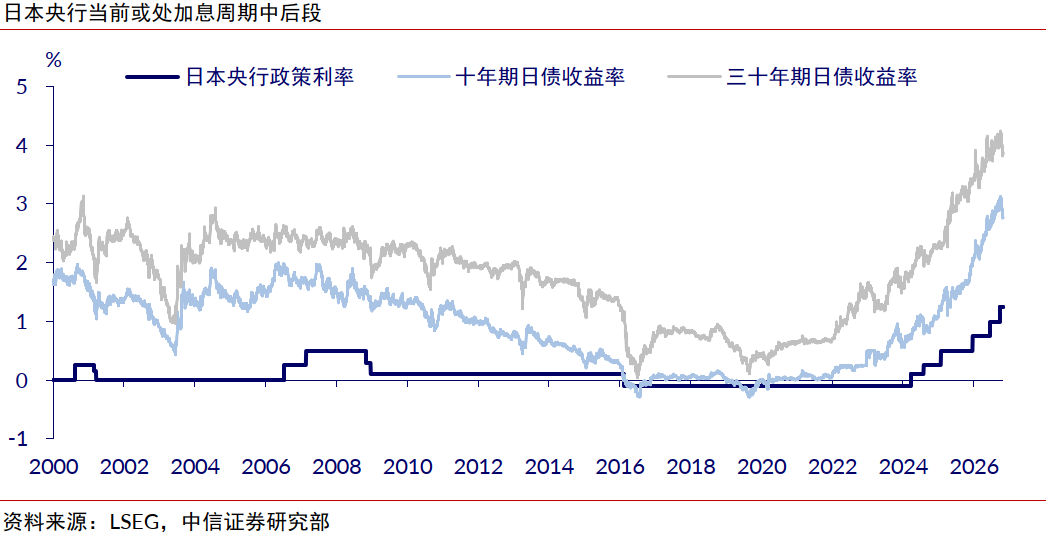
Asset allocation: More balanced opportunities.
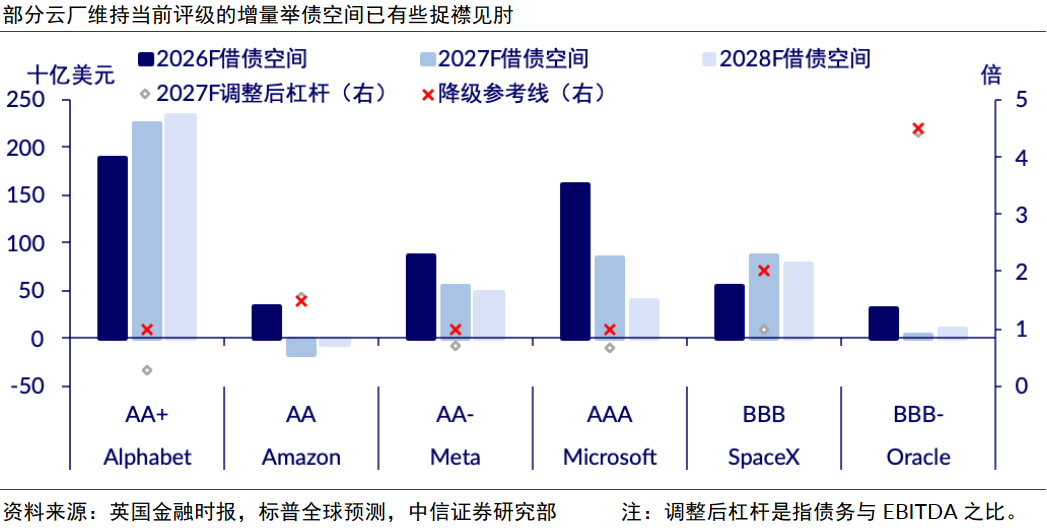
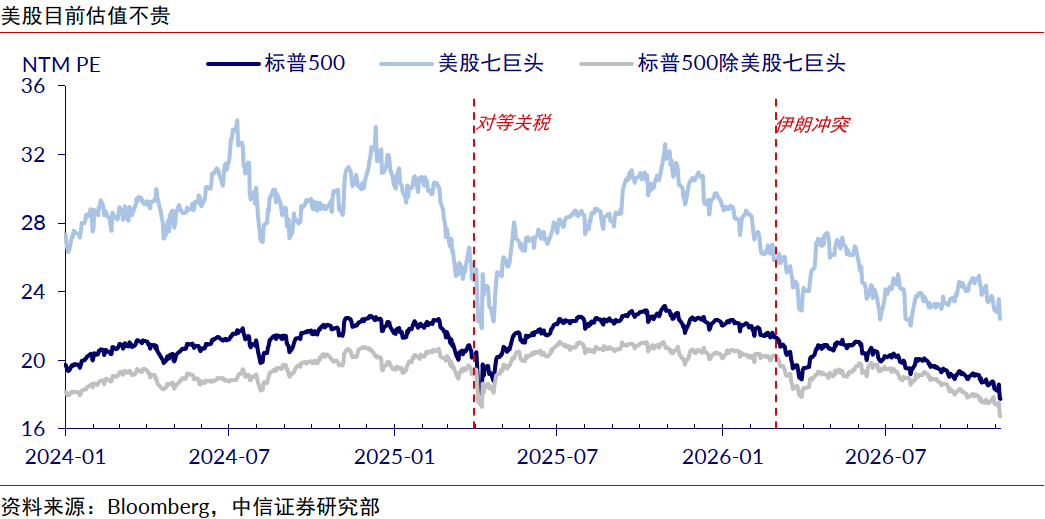
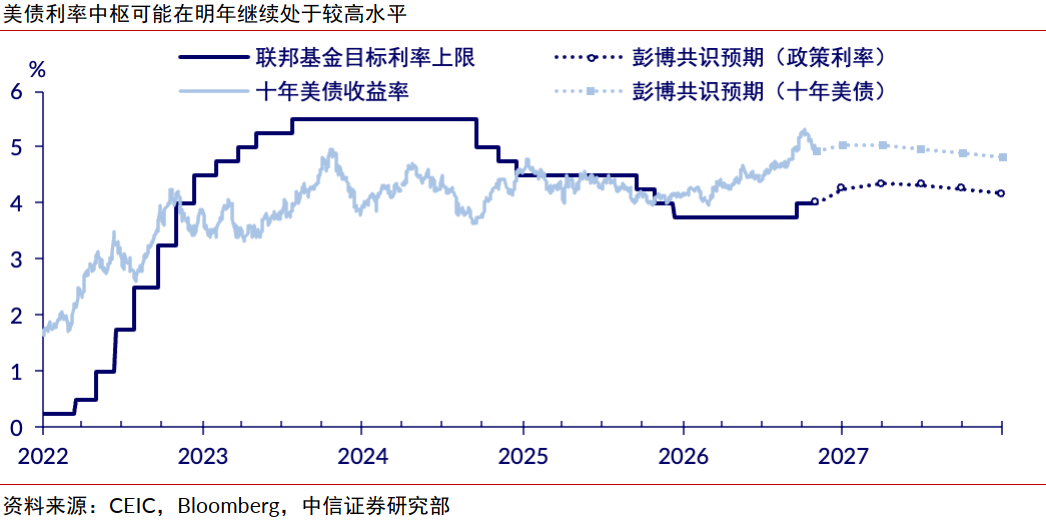
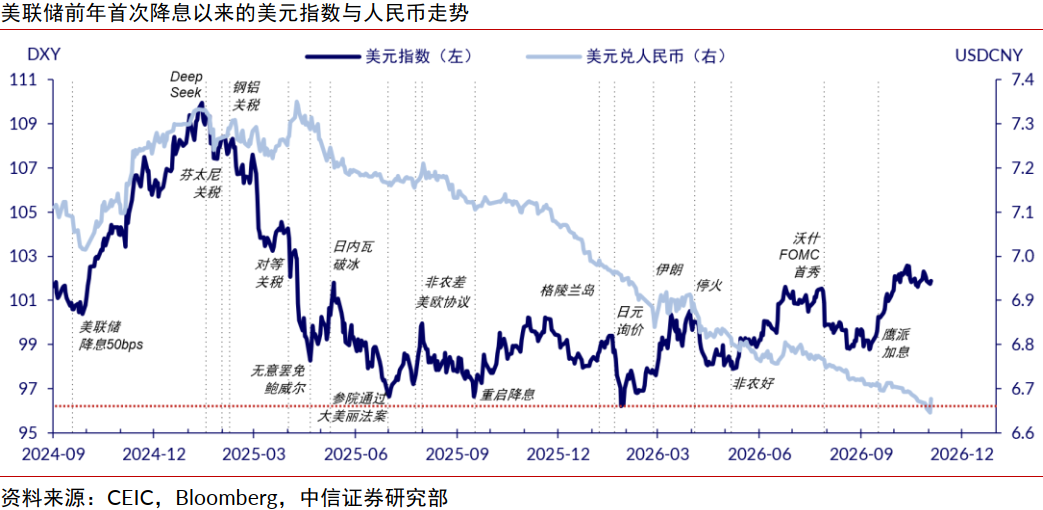
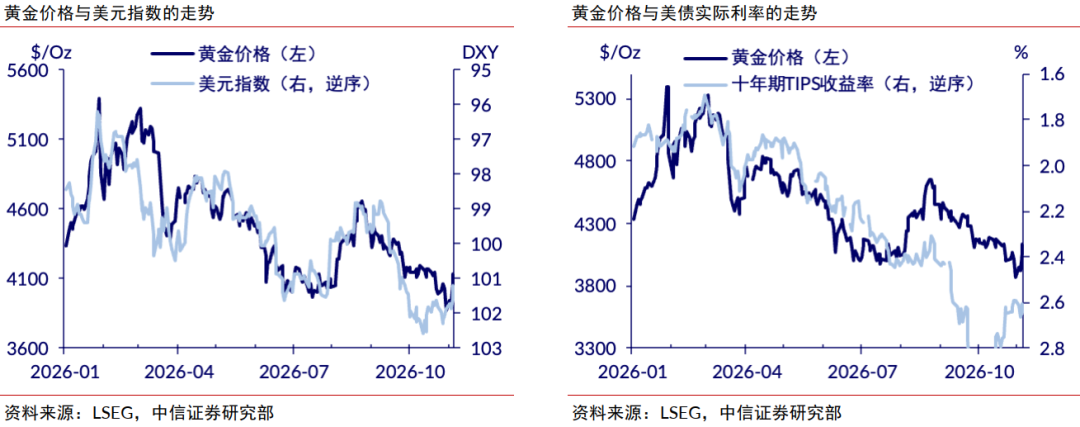
The market's view of technology companies is becoming more strict. US stocks may face more frequent or drastic fluctuations next year. We are cautious about the financial risks of new cloud vendors and the room for price increases for computing power hardware, but the growth narrative in the middle and downstream of the computing power chain should still hold true. The traditional sector has no shortage of attractive valuations, and it is expected that next year it will benefit from weakening expectations of liquidity contraction and the support of economic momentum. The strategy for US stocks is suitable for a dips layout, and we prefer a balanced layout idea. The 10-year US Treasury yield should have confirmed its peak. The restoration of market confidence in US fiscal discipline and the improvement in dollar liquidity expectations after the midterm elections may reduce it to around 4.5%. The US dollar index is likely to fall slightly next year and fluctuate weakly below the 100 mark. Gold may once again have the necessary conditions for capital inflows by the end of this year. Gold prices are expected to recover, and the timing for a turning point in sentiment is worth grasping.