


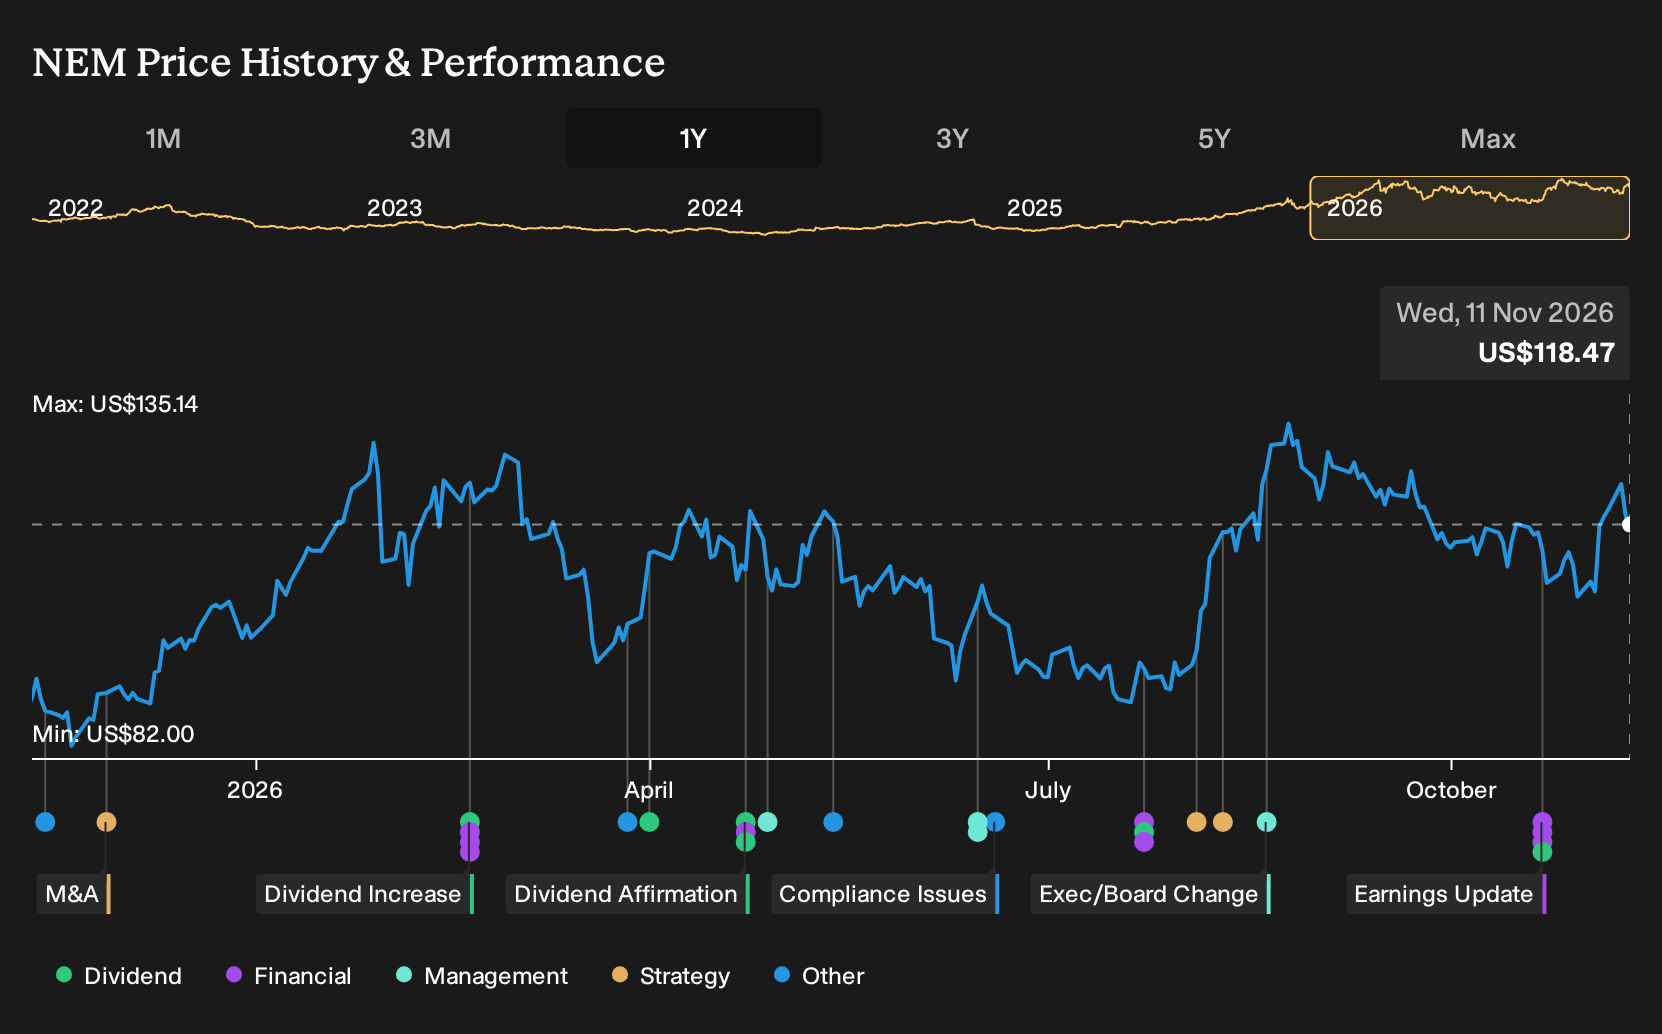
- Newmont recently faced sharp gold price swings after higher than expected U.S. inflation data and renewed talk of Federal Reserve rate hikes, while also updating investors on rising all in sustaining costs and a softer near term production outlook.
- The combination of inflation driven pressure on input costs, a planned increase in capital spending, and guidance for lower 2026 output highlights how closely Newmont’s profitability is tied to both its cost reset efforts and day to day moves in the gold market.
- We will examine how Newmont’s investment narrative holds up in the context of higher reported all in sustaining costs and a weaker production outlook.
Scan how other gold producers are reacting to the same rate and cost pressures hitting Newmont by reviewing the hand picked 33 elite gold producer stocks that fit this theme.
Newmont Investment Narrative Recap
Owning Newmont means buying into a business that lives and dies by its ability to keep costs in line while turning a multi asset gold and copper portfolio into consistent cash. The analyst consensus Narrative on Simply Wall St highlights a reset of the cost base and projects like Red Chris and Tanami Expansion 2 as key to that story. The latest inflation surprise and gold pullback hit the share price, but the bigger swing factor in the near term is whether Newmont can steady all in sustaining costs after the recent 25% year on year jump.
The main short term catalyst is progress on cost discipline and operational stability across sites like Penasquito, Lihir and Boddington. The biggest risk is that higher energy and consumable prices or further safety and geotechnical issues at assets such as Red Chris force more spending just as 2026 production is expected to be softer. If gold remains volatile, that cost and volume mix will matter more than this specific inflation headline.
One update that ties most directly to this news is Newmont’s recent guidance that all in sustaining costs rose about 25% year on year in Q3 2026, with expectations for another step up in Q4 as capital spending peaks and silver output at Penasquito eases. Those numbers explain why gold price swings quickly feed into earnings sensitivity when the cost base is under pressure.
For you as a shareholder or prospective investor, that AISC reset sits alongside the longer project list mentioned in the analyst consensus Narrative on Simply Wall St, from Red Chris and Lihir investments to brownfield expansion at Tanami. Execution on those projects, and whether the firm can keep cost inflation from eating into the forecast 4.41% annual earnings growth, will likely be more important catalysts than any single Fed meeting.
Newmont's current analyst narrative points to forecast revenues of $31.4b and projected earnings of $11.9b by 2029. These figures are based on assumptions for 5.7% yearly revenue growth and an earnings increase of about $2.7b from $9.2b today.
Uncover why Newmont's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Newmont’s capital returns as the real catalyst, not just cost control. Before this inflation surprise, the bullish cohort was penciling in about US$40.2b of revenue and US$14.8b of earnings by 2029, a much stronger path than consensus. Views clearly vary, so explore several narratives before you decide how this news might reshape them.
Explore 8 other Newmont fair value estimates, including one that indicates potential upside of up to 39% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Newmont research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Newmont. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newmont's overall financial health at a glance.
Looking For More Ideas Beyond Newmont?
If this Newmont update has sharpened your view on gold exposure, broaden the opportunity set and pressure test your thesis against other listed businesses using the Simply Wall St Screener.
- For investors focused on quality at a reasonable price, review a curated 32 high quality undervalued stocks that combines strong fundamentals with potentially appealing valuations.
- If dependable income is your priority, scan a hand picked group of 6 dividend fortresses that aim to pair higher yields with resilient payouts.
- For those who care most about resilience, start with a 30 resilient stocks with low risk scores that concentrates on companies with sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com