


Cardinal Energy (TSX:CJ) just paired a detailed third quarter earnings release with a fresh dividend declaration, putting production growth, cash generation and payout sustainability in sharper focus for income oriented investors.
Recent price action reflects that tension between strong reported results and shifting expectations. The share price is now at CA$11.45, with a 1-day share price return of 2.42% but a 30-day share price return down 12.8%. Even so, the year to date share price return of 30.11% and a 1-year total shareholder return of 39.42% point to momentum that has built over a longer stretch, with the 3-year total shareholder return of 119.93% and 5-year total shareholder return of 264.17% showing how earlier investors have already seen substantial compounding.
Scan other income focused energy plays that show similar earnings momentum and dividend stories with our curated list of 3 dividend fortresses.
Cardinal Energy is reporting higher earnings and maintaining an ongoing dividend, while the share price has slipped over the past month. Is the stronger cash story still underappreciated, or has most of the upside already played out in the valuation on offer?
Most Popular Narrative: 38% Undervalued
Measured against the current CA$11.45 share price, the most followed Simply Wall St Community view on Cardinal Energy points to a fair value of CA$18.51, which implies meaningful upside if that narrative proves accurate. According to BrandonH, an investor in the Simply Wall St Community who set out this thesis, the key question is how management uses cash and balance sheet flexibility over the next few years.
Low debt, with room to issue more to cover dividend or existing growth project if needed by YE 2025 as a low fiscal risk position. This allows for strategic M&A if a downturn occurs for pulling ahead of competition.
See why 22 investors see Cardinal Energy as 38% undervalued.
Result: Fair Value of CA$18.51 (UNDERVALUED)
Still, higher debt usage, slower cash generation, or delays to growth projects could chip away at the 38% undervalued Cardinal Energy narrative.
Find out about the key risks to this Cardinal Energy narrative.
Another View: Cardinal Energy Through The P/E Lens
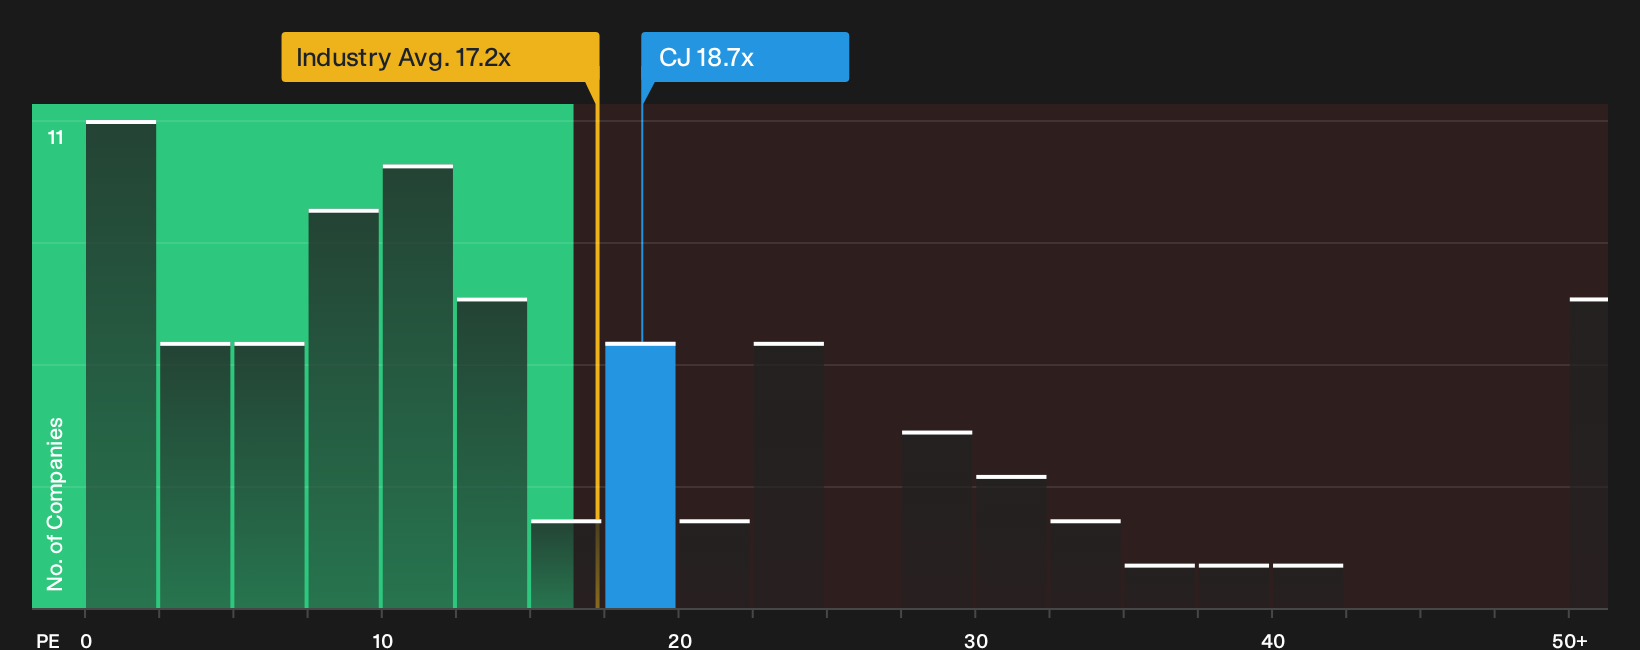
DCF fans see Cardinal Energy as materially undervalued at a CA$25.05 future cash flow value versus the CA$11.45 share price. The P/E picture is cooler. CJ trades at 18.7x earnings, slightly above the 18x fair ratio and the 17.2x Canadian Oil and Gas average, which signals less obvious upside if sentiment turns.
That kind of small premium to both the fair ratio and sector raises a practical question for you. Is the higher multiple a reasonable price for recent 40.5% earnings growth and a 6.29% dividend yield that is not fully covered by free cash flow, or is it a margin of error you are unwilling to pay for?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you test them against the numbers yourself and move quickly while the data is still fresh. To weigh Cardinal Energy's income potential against the concerns being raised and the upside that some investors still see, start by looking through the 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Cardinal Energy?
If you only focus on Cardinal Energy, you might miss other setups that fit your goals just as well. Use the Simply Wall St Screener to turn today’s research into a broader watchlist that works harder for you.
- Target stability first and hunt for companies that combine manageable risk with staying power through the 9 resilient stocks with low risk scores.
- Chase quality at a sensible entry point and sift for companies with strong fundamentals trading below estimated value using the 5 high quality undervalued stocks.
- Prioritise resilience and financial strength by scanning for businesses with cleaner balance sheets and solid fundamentals in the list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com