


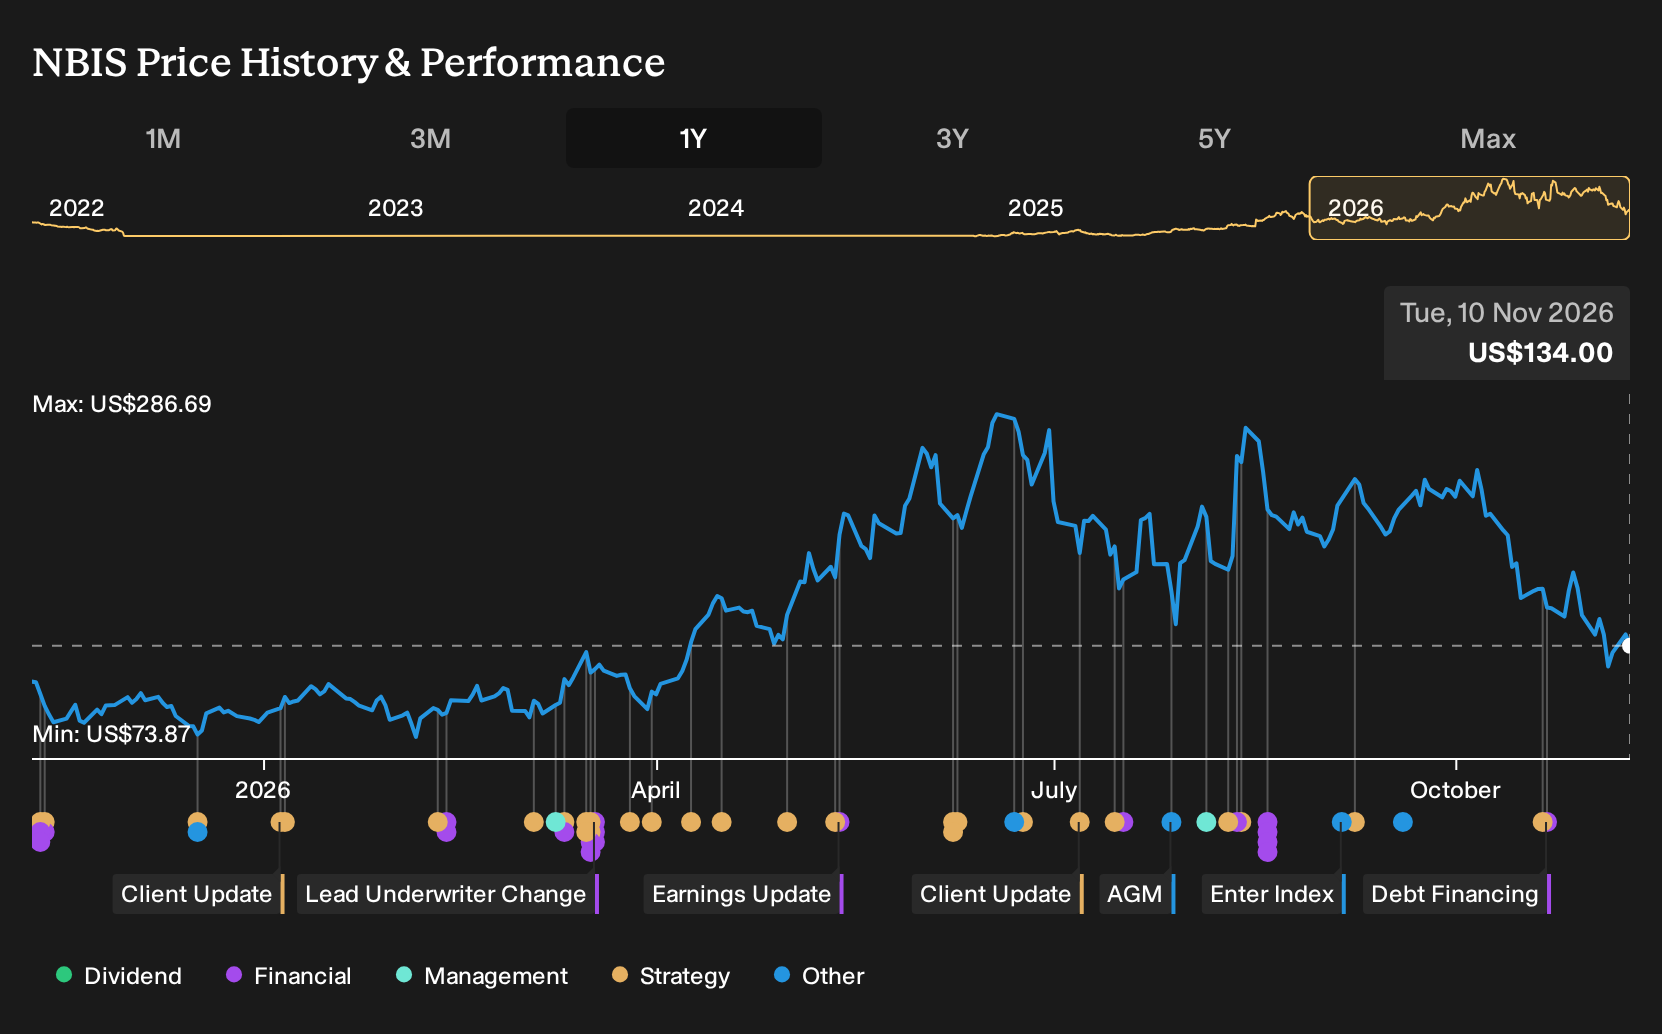
- Nebius Group shares reacted to CoreWeave's strong quarterly update and raised outlook, as investors focused on what this might signal for demand and financing conditions in AI cloud infrastructure ahead of Nebius' own Q3 release on 12 November 2026.
- The news sharpened attention on whether Nebius' large Microsoft contract, GPU build out and funding arrangements can translate strong sector demand into scalable and capital efficient AI cloud operations.
- We will now look at how Nebius Group's investment narrative could be affected by CoreWeave's results driven optimism around AI infrastructure demand.
Scan beyond Nebius Group and see how other AI infrastructure players are positioning for the next phase of this trade with the 53 AI infrastructure stocks.
Nebius Group Investment Narrative Recap
To own Nebius Group, an investor needs to believe AI cloud can stay the main engine and remain both high margin and capital efficient as the GPU build ramps. Womble, a Simply Wall St Community investor who wrote the narrative, argues that the thesis leans on AI Cloud staying dominant while TripleTen and Avride remain contained side bets. CoreWeave’s strong quarter signals firm sector demand, but the key near term catalyst is still Nebius’ own Q3 print and clarity on utilisation, cash burn and whether Microsoft related workloads are scaling cleanly.
The biggest operational risk right now is execution on a highly leveraged expansion plan in a very volatile stock. Debt, heavy capex and high non cash earnings leave little room for missteps if utilisation, margins or Microsoft related revenue timing disappoint. The CoreWeave read across does not remove that risk. It just raises the bar for Nebius to prove its model can turn contracted demand and its US$3.5b facility into sustainable cash generation.
The most relevant recent disclosure is Nebius’ US$3.5b financing facility to expand GPU and data center capacity, which sits directly in focus after CoreWeave’s upbeat comments on funding conditions. That facility underpins the attempt to reach multi gigawatt scale AI infrastructure and is effectively the fuel behind the current earnings catalyst investors are waiting on this week.
Womble sees that spending as a double edged catalyst. It can accelerate AI Cloud revenue if capacity is deployed on time and filled; yet it also increases exposure to under utilisation, lower AI Cloud EBITDA margins and prolonged weak free cash flow. With the stock already highly volatile and priced for strong execution, the way Nebius updates on capex, drawdowns under that facility and any change in Microsoft related commitments in Q3 will likely shape how investors treat both the upside story and the balance sheet risk.
Womble’s narrative arrives at its fair value of US$259.97 per Nebius Group share by applying a scenario where revenue increases 21.8% a year and the business eventually reaches a future profit margin of 3.1%.
Find out why Nebius Group's fair value suggests a 68% potential upside to its current price before that gap begins to close.
Exploring Other Perspectives
One contrasting angle focuses on funding risk. The lowest Nebius Group analysts already assumed revenue could climb to about US$23.9b with earnings near US$3.0b by 2029, yet still saw the stock as stretched. Those expectations were set before CoreWeave’s upbeat update, so your own view might shift as fresh information comes through.
Explore 12 other Nebius Group fair value estimates, including one that suggests as much as 30% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nebius Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking for more Nebius Group style investment ideas?
If Nebius Group has you rethinking how AI and infrastructure fit in your portfolio, use that same framework to scan the wider market. The Simply Wall St Screener can help you filter for different risk and return profiles in a few clicks so you are not relying on a single story.
- For investors who want potential upside in smaller companies but still care about balance sheet strength and fundamentals, start with this list of solid balance sheet and fundamentals (24 results) as a quality filter.
- If capital preservation ranks high on your list and you prefer steadier profiles, take a look at companies in the 30 resilient stocks with low risk scores to find stocks with more resilient risk characteristics.
- When you are hunting for opportunities that the market may not be fully focused on yet, use the 19 high quality undiscovered gems to surface lesser known businesses with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com