


- Canadian National Railway reported third quarter 2026 sales of C$4.77b and net income of C$1.21b, alongside a confirmed Q4 dividend and continued share repurchases, and also outlined an upcoming CFO transition.
- The combination of higher earnings per share, ongoing capital returns and a planned handover from long serving CFO Ghislain Houle to Jamie Lockwood gives investors fresh data points on Canadian National Railway’s profit engine and leadership continuity.
- We will look at how Canadian National Railway’s stronger quarterly earnings and CFO succession plans reshape its longer term investment narrative.
Canadian National Railway Investment Narrative Recap
To own Canadian National Railway, you need to believe that core freight demand, Western Canada export volumes and efficiency gains under programs like Fast Track can support the analyst consensus Narrative on Simply Wall St, which points to higher earnings power over time. The latest quarter, with C$4,771 million in sales and C$1,209 million in net income, supports a picture of a network that is still fully in use.
The short term swing factor remains how uneven end markets such as lumber, overseas intermodal and industrial freight evolve from here. Recent earnings do not remove the risk that weaker segments could pressure revenue and margins, especially with a high debt load that limits room for error.
The most directly relevant update for catalysts is the third quarter 2026 earnings print, alongside nine month figures. Basic EPS from continuing operations of C$2.00 for the quarter and C$5.94 for the first nine months gives you fresh reference points for whether Western Canada capacity projects, new Mexico related corridors and cost savings are flowing through to the bottom line yet.
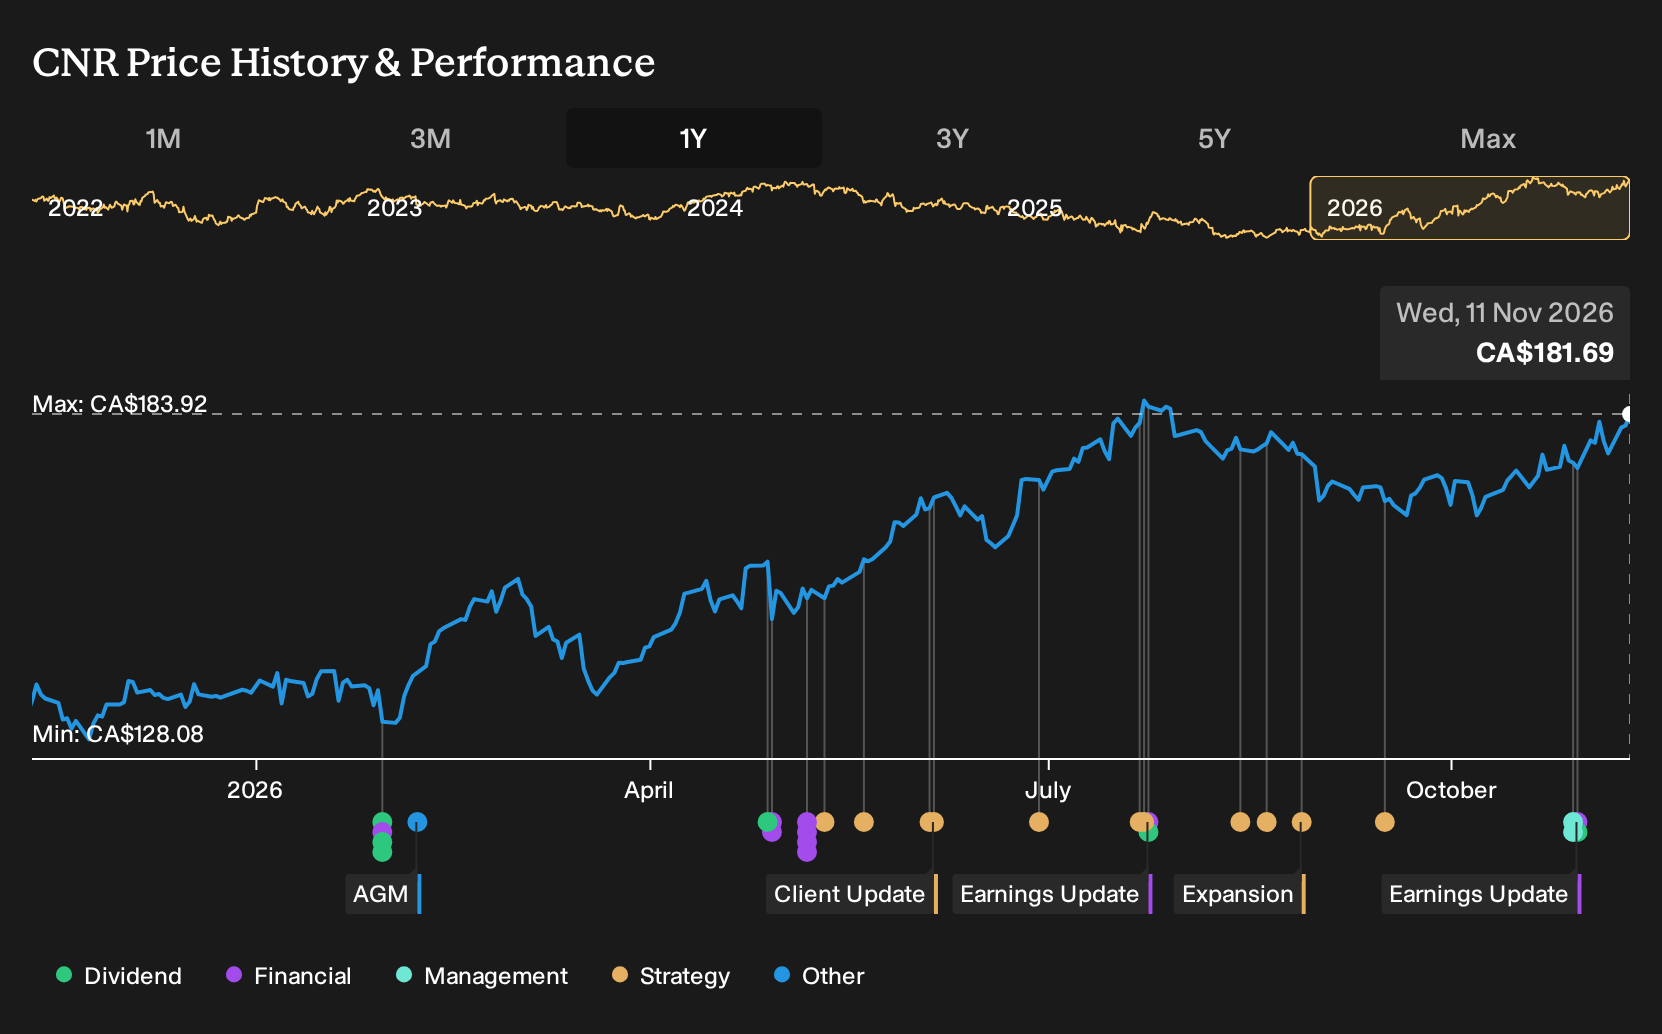
Those same results sit beside a confirmed C$0.9150 fourth quarter dividend and ongoing buybacks, which shows management using cash for both shareholder returns and balance sheet leverage. For anyone focused on execution risk, the upcoming CFO transition to Jamie Lockwood adds a governance angle that matters for capital allocation, funding decisions and how confidently Canadian National Railway can pursue its growth and efficiency catalysts.
Canadian National Railway's current analyst narrative points to revenue of CA$20.9b and earnings of CA$5.8b by 2029, based on forecasts that call for 5.5% yearly revenue growth and an earnings increase of about CA$1.0b from the CA$4.8b level cited for today.
Uncover why Canadian National Railway's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between C$156.88 and C$191.49, so you are seeing a tight band rather than outliers. That leaves Canadian National Railway’s recent earnings beat, stepped up buybacks and the CFO transition as the swing factors that could shift how different investors frame future performance. Explore the full range of community views before leaning on any single narrative.
Explore 2 other Canadian National Railway fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian National Railway research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian National Railway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian National Railway's overall financial health at a glance.
Looking for more investment ideas beyond Canadian National Railway?
Once you have formed a view on Canadian National Railway, it can help to test that thesis against a broader watchlist. The Simply Wall St Screener lets you quickly compare financial strength, dividends and valuation across hundreds of other businesses so you can see where the risk and reward trade offs look most attractive to you.
- If capital preservation is a priority, you might want to focus on sturdier balance sheets and steadier fundamentals using the 9 resilient stocks with low risk scores.
- If income is central to your plan, you can zero in on higher yielding payers with robust financials by scanning through the 3 dividend fortresses.
- If you prefer hunting for less crowded situations with solid metrics, filter for financially sound outliers using the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com