


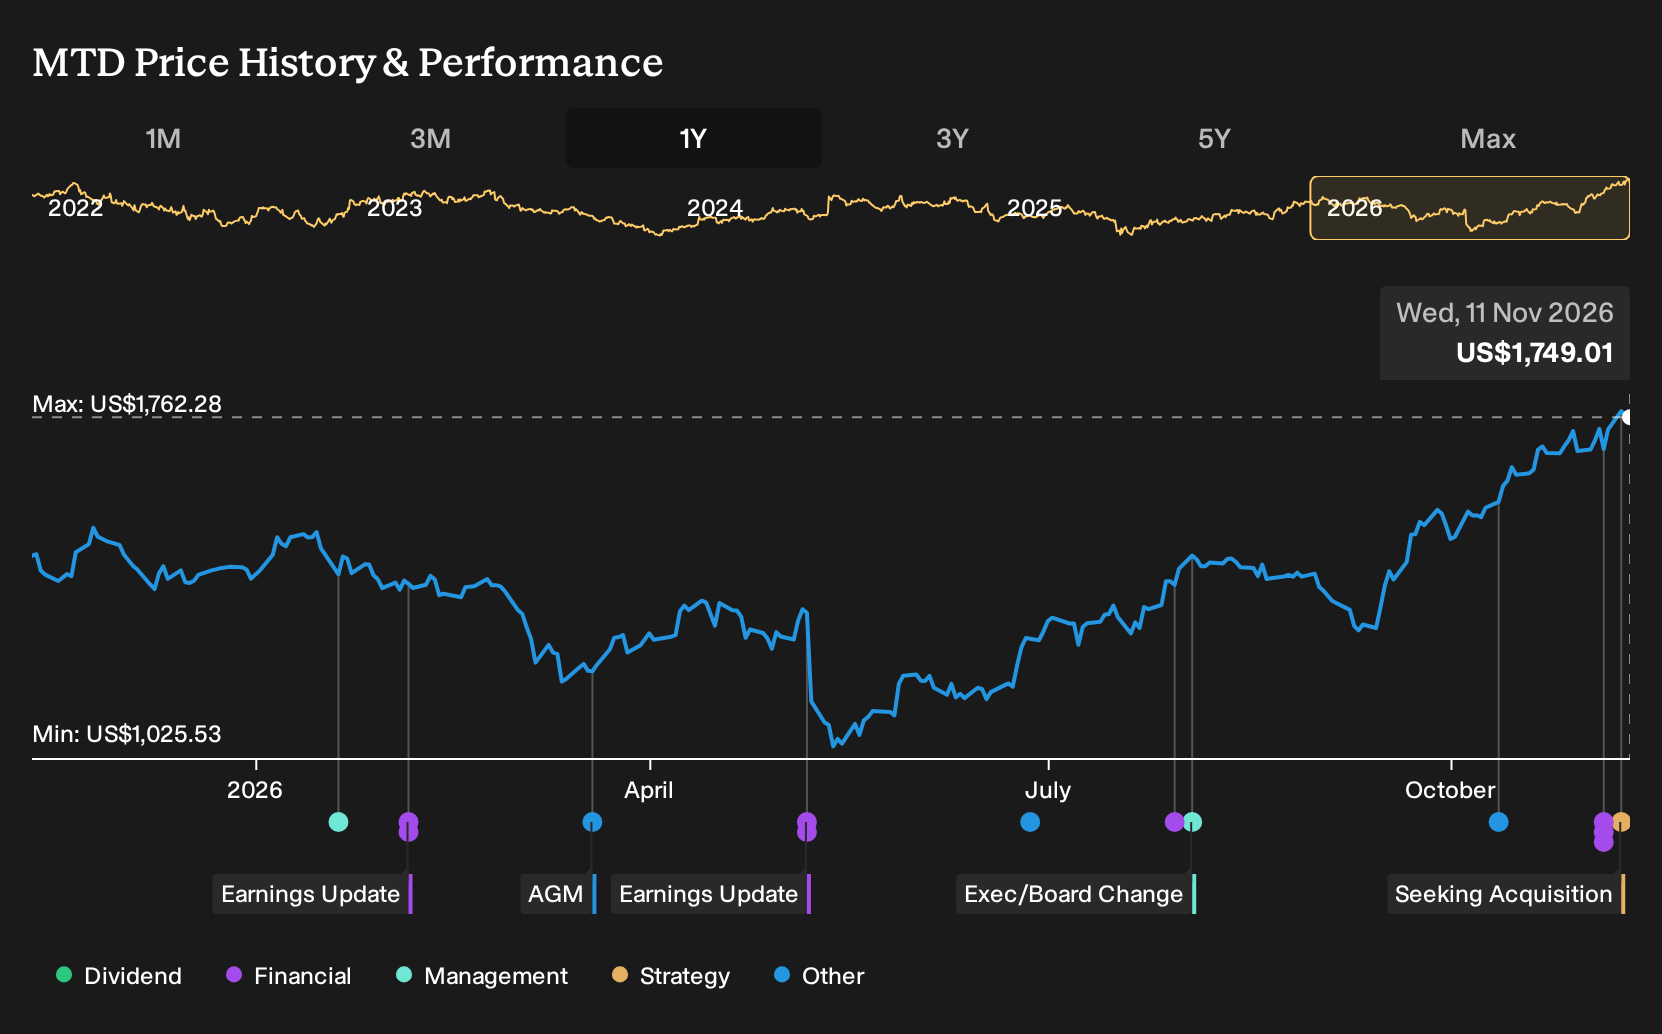
- Mettler-Toledo International reported third quarter 2026 sales of US$1,094.29 million and net income of US$245.95 million, with management also lifting full year local currency sales guidance to about 5% growth.
- Alongside these results, the company outlined an active bolt on acquisition agenda focused on life science tools adjacencies and distribution assets that could extend its sales and service reach.
- The next area of focus is how Mettler-Toledo International's raised sales guidance could influence its existing investment narrative around automation and services.
Scan Mettler-Toledo International's automation and life science tools story against a curated set of peers by running through the 89 robotics and automation stocks that could be lining up their next leg of growth.
Mettler-Toledo International Investment Narrative Recap
To own Mettler-Toledo International, you need to believe its automation, bioprocessing and high value service lines can keep pulling more weight than softer specialty chemical and European markets, as described in the analyst consensus Narrative on Simply Wall St. The raised local currency sales outlook of about 5% growth leans on that view and keeps the short term focus on execution rather than any reset in expectations.
The key near term catalyst is whether Laboratory, Industrial and service activity stay strong enough to absorb tariff and end market pressure that has already hit margins in prior periods. The biggest risk remains tariff volatility and any renewed slowdown in capital spending that could restrain organic sales and limit operating leverage.
The clearest recent signal is management’s guidance that full year 2026 local currency sales are expected to rise about 5%, slightly above the prior 4% to 5% range. This sits alongside commentary that automation, digitalization and emerging markets helped Q3 performance. Together, these factors present a business leaning on internal programs and demand pockets rather than one dependent on a cyclical rebound.
For you as an investor, this updated outlook and bolt on acquisition appetite in life science tools and distribution put execution under the microscope. Integrating any deals while keeping tariffs, debt and softer European demand in check will likely shape how closely the business tracks the earnings and margin path embedded in the analyst consensus Narrative on Simply Wall St.
Mettler-Toledo International's current earnings are reported at US$934.1 million, with analysts forecasting earnings of US$1.1 billion by 2029, which implies an increase of about US$165.9 million. This projection is presented alongside expectations for revenue to reach US$4.8 billion by 2029, based on an assumed 4.8% yearly rise in sales over the next few years.
Uncover why Mettler-Toledo International's fair value indicates a 9% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view focuses on valuation risk rather than tariffs. The most cautious analysts already assumed Mettler-Toledo International would reach about US$4.8b of revenue and US$1.1b of earnings by 2029, yet they still used a much lower 25.1x P/E. That led to a fair value estimate of US$1,200. These forecasts all pre date the stronger Q3 and new acquisition ambitions, so use this range of opinions as a cue to compare several narratives before deciding what you think might change next.
Explore another Mettler-Toledo International fair value estimate, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mettler-Toledo International research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mettler-Toledo International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mettler-Toledo International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mettler-Toledo International?
Once you have a view on Mettler-Toledo International, it can help to benchmark that thesis against other companies with different balance sheets, cash flow profiles and income streams. A focused screener lets you move quickly from a single stock story to a short list of alternatives that fit the risk and return profile you actually want.
- If capital preservation and smoother price swings matter most to you, start with a set of companies flagged for resilience by running through the 30 resilient stocks with low risk scores.
- If you care about financial strength before anything else, filter for businesses with cleaner balance sheets and steadier fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for underfollowed opportunities with solid numbers, broaden your watchlist with a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com