


Why Topaz Energy’s latest earnings are drawing attention
Topaz Energy (TSX:TPZ) just delivered a quarterly earnings surprise alongside higher year over year revenue and net income, supported by stronger production volumes. This is putting fresh focus on how the stock reflects these updated results.
Topaz Energy’s share price has been relatively steady around CA$29.02 this year, with a 1-day share price return of 1.22% and a 7-day gain of 1.97% following the earnings. The 1-year total shareholder return of 14.22% and 5-year total shareholder return of 112.08% highlight momentum that has built over a longer horizon, despite a softer 90-day period in which the share price fell 4.79%.
Compare Topaz Energy’s earnings surprise with other potential opportunities and scan a curated list of 5 high quality undervalued stocks showing strong fundamentals and financial resilience.
Bulls are pointing to Topaz Energy’s earnings surprise and long term return record, while bears focus on the flat near term share move. Which case does the current valuation lean toward?
Most Popular Narrative: 20% Undervalued
Topaz Energy’s fair value in the analyst consensus Narrative on Simply Wall St is pinned at around CA$36.35, compared with the latest close of CA$29.02, which frames the current debate around how durable its royalty and infrastructure cash flows really are.
The main thing that has to go right is that royalty growth from Clearwater and Montney activity, paired with high utilization and margins in the infrastructure portfolio, continues to cover rising dividends and modest acquisition spending within the targeted payout and leverage ranges.
The current premium P/E multiple relative to the wider oil and gas sector implies the share price already embeds confidence that Topaz Energy’s capital light model, dividend track record, and royalty plus infrastructure growth will be sustained.
See why 16 investors see Topaz Energy as 20% undervalued.
Result: Fair Value of CA$36.35 (UNDERVALUED)
Still, the Topaz Energy story hinges on commodity prices and debt. A prolonged pricing slump or slower cash flow could pressure margins, dividends, and the company’s premium P/E ratio.
Find out about the key risks to this Topaz Energy narrative.
Another View: Topaz Energy looks expensive on earnings
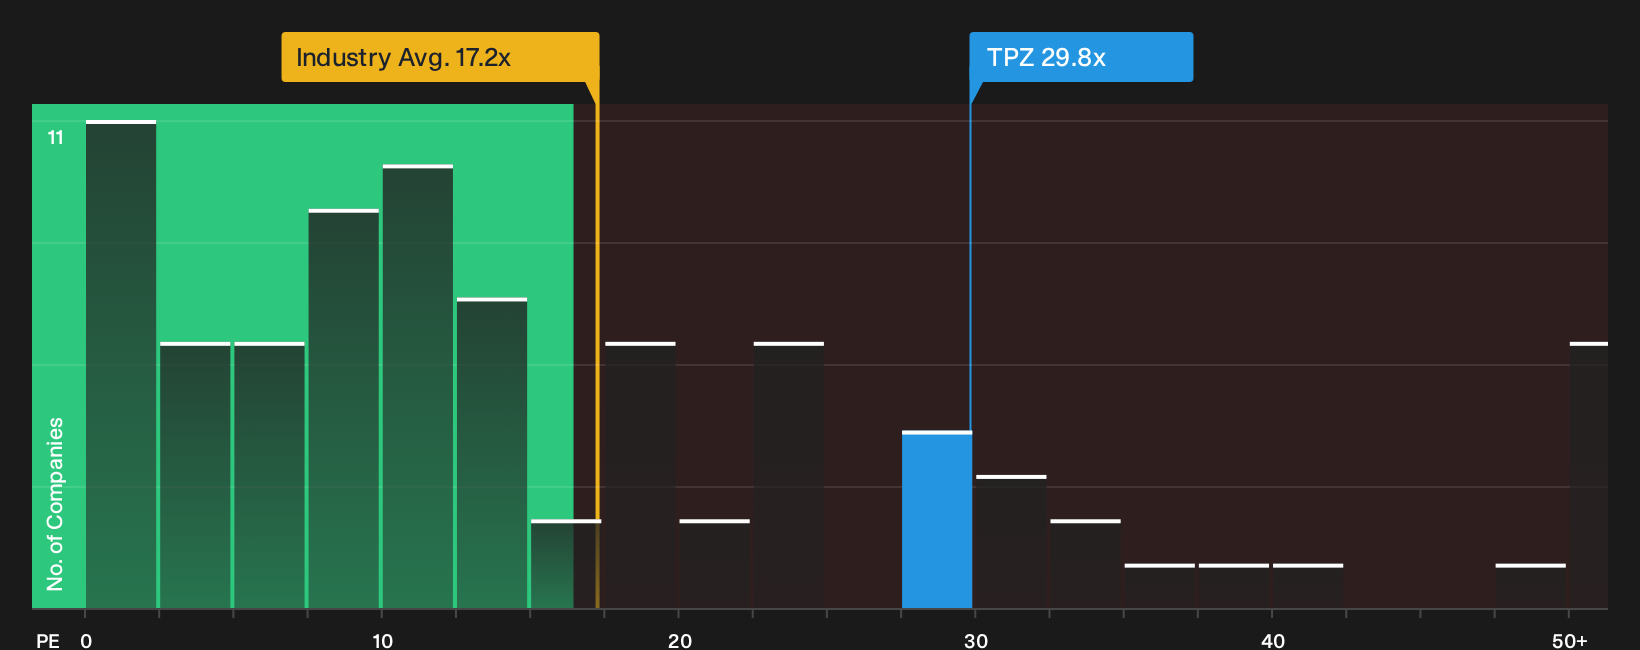
The SWS fair ratio for Topaz Energy’s P/E sits at 16.7x, while the stock trades around 29.8x. That is also richer than the Canadian oil and gas industry at 17.2x and a peer average of 21.6x, which points to meaningful valuation risk if sentiment cools.
Our ratio model suggests the market could shift closer to that 16.7x fair ratio if royalty and infrastructure cash flows lose some of their shine. The key question is whether you think this premium can hold or will eventually compress.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and fundamentals usually split opinion quickly. Assess Topaz Energy’s trade off between caution and optimism and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Topaz Energy?
Consider looking beyond Topaz Energy, as there are many other candidates that could align with your goals across quality, income, and risk control.
- Target resilient balance sheets and disciplined fundamentals through a curated list of solid balance sheet and fundamentals (5 results) that can help you stress test your portfolio before the next period of market volatility.
- Explore potential income streams by scanning a focused set of high yielding 3 dividend fortresses that combine meaningful payouts with underlying business strength.
- Review a hand picked pool of 7 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com