


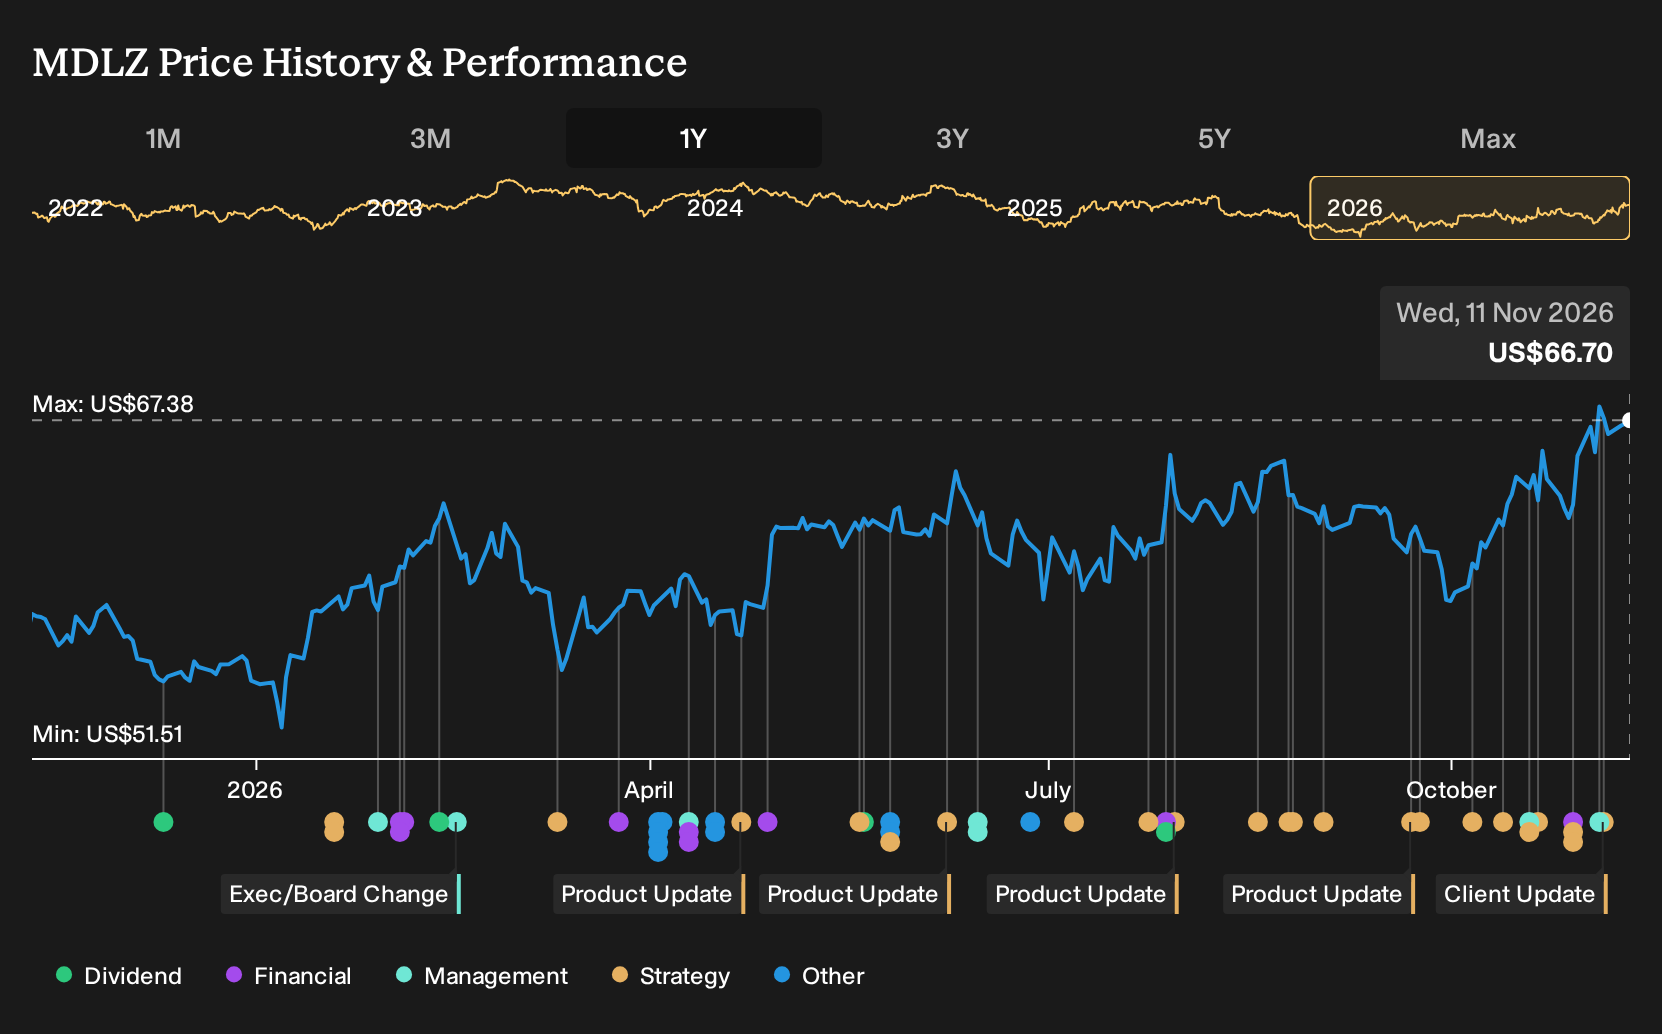
- Mondelez International reported third quarter 2026 sales of US$9,967 million and net income of US$1,305 million, together with a collaboration with Accenture to apply agentic AI across its Order to Cash operations.
- The AI led overhaul of Order to Cash targets faster collections, lower operating friction and richer real time data, directly linking Mondelez International's commercial execution, cash generation and customer experience.
- This article considers how Mondelez International's reported earnings, together with the agentic AI rollout, could influence the broader investment narrative.
Compare Mondelez International's AI driven efficiency push with other companies reshaping operations through automation. Scan our hand picked 53 AI infrastructure stocks for potential ideas.
Mondelez International Investment Narrative Recap
To own Mondelez International, you need to believe its global snacking portfolio, pricing and brand investment can offset input cost swings and consumer trade downs. The analyst consensus Narrative on Simply Wall St leans on steady revenue expansion and modest margin improvement, with AI linked productivity and supply chain work aiming to keep earnings quality resilient.
The Accenture agentic AI rollout sits squarely on the short term catalyst list because it targets cash conversion, working capital and issue resolution speed. Execution risk sits on the other side. If cocoa costs or lower income demand worsen again while Mondelez International keeps spending heavily on brands and tech, earnings could feel a squeeze.
The new Order to Cash collaboration with Accenture is the clearest near term operational swing factor tied to the recent update. Management is wiring AI into customer service, supply chain and finance to improve visibility on millions of transactions, with an eye on faster collections, fewer errors and more precise decisions across the commercial engine.
If the project delivers cleaner cash flow and better working capital, it can support the reinvestment pattern analysts already bake into the analyst consensus Narrative on Simply Wall St. Any delays or complexity in rolling this approach into other functions would keep Mondelez International more exposed to classic risks like cocoa volatility, retailer behavior and debt leverage.
Mondelez International's current narrative centers on analysts expecting revenues of US$43.2b and earnings of US$4.7b by 2029. These projections are based on a forecast 2.8% yearly revenue growth rate and an earnings increase of US$1.2b from about US$3.5b today.
Uncover why Mondelez International's fair value indicates a 4% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Fair value estimates for Mondelez International from three private investors in the Simply Wall St Community span roughly US$69 to US$112, which is a wide gap for the same business. These views sit beside risks like renewed cocoa cost pressure or demand weakness, so you are seeing sharply different opinions. Explore several viewpoints before leaning on any single fair value.
Explore 2 other Mondelez International fair value estimates, including one that suggests it could be worth just $69.13.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Mondelez International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mondelez International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Mondelez International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mondelez International?
Once you have formed a view on Mondelez International, it can help to set it alongside other opportunities that fit different risk and return profiles. The Simply Wall St Screener gives you a structured way to compare businesses rather than hunting ticker by ticker.
- If capital protection is front of mind, start with a shortlist of companies that tend to score well on stability metrics by reviewing 30 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and underlying fundamentals, widen the lens with a list of solid balance sheet and fundamentals (24 results) that can support long term compounding.
- If you are searching for mispriced opportunities backed by solid cash generation and quality indicators, scan through a focused set of 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com