


- Capital Clean Energy Carriers reported third quarter 2026 sales of US$138.14 million and net income of US$34.61 million, with basic and diluted earnings per share of US$0.57 from continuing operations, all higher than the same period a year earlier.
- The third quarter strength contrasts with softer nine month earnings, where sales reached US$341.04 million but net income was US$85.48 million and earnings per share trailed the prior year. This highlights how recent operational performance may be improving against a tougher year to date base.
- We will now see how Capital Clean Energy Carriers’ stronger third quarter earnings profile could influence the existing investment narrative around contracted growth.
Scan how Capital Clean Energy Carriers’ earnings profile compares with peers by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) that may offer similar financial resilience.
Capital Clean Energy Carriers Investment Narrative Recap
To own Capital Clean Energy Carriers, you need to believe its multi decade gas and LCO₂ fleet build can turn the current charter backlog into steady earnings even as financing remains demanding. The third quarter result, with higher sales and profit than a year earlier, supports that contracted model and suggests the fleet is being put to work effectively.
The key short term catalyst remains clean execution on vessel deliveries and charters while leverage sits around the low 50% range and interest costs are sensitive to floating rates. Nine month earnings, which trail the prior year despite higher sales, show that funding and margin pressure are still the biggest live risks.
The analyst consensus narrative on Simply Wall St focuses on the multi year orderbook, charter coverage and forecast earnings growth. The latest quarterly report, which shows US$138.14 million in revenue and US$34.61 million in net income for the period, speaks directly to whether the existing fleet and contracts are supporting that thesis in real time.
At the same time, the softer nine month net income of US$85.48 million against higher sales of US$341.04 million keeps the spotlight on interest expense, capex and cash conversion. For catalysts to keep working in your favor, Capital Clean Energy Carriers still has to balance the orderbook, funding needs and dividend ambitions without letting leverage or uncovered floating rate exposure constrain future flexibility.
Capital Clean Energy Carriers’ analyst narrative points to forecast revenue of US$892.5 million and projected earnings of US$263.3 million by 2029, based on an assumed 31.0% annual revenue growth rate and an earnings increase of about US$165.0 million from earnings today of US$98.3 million.
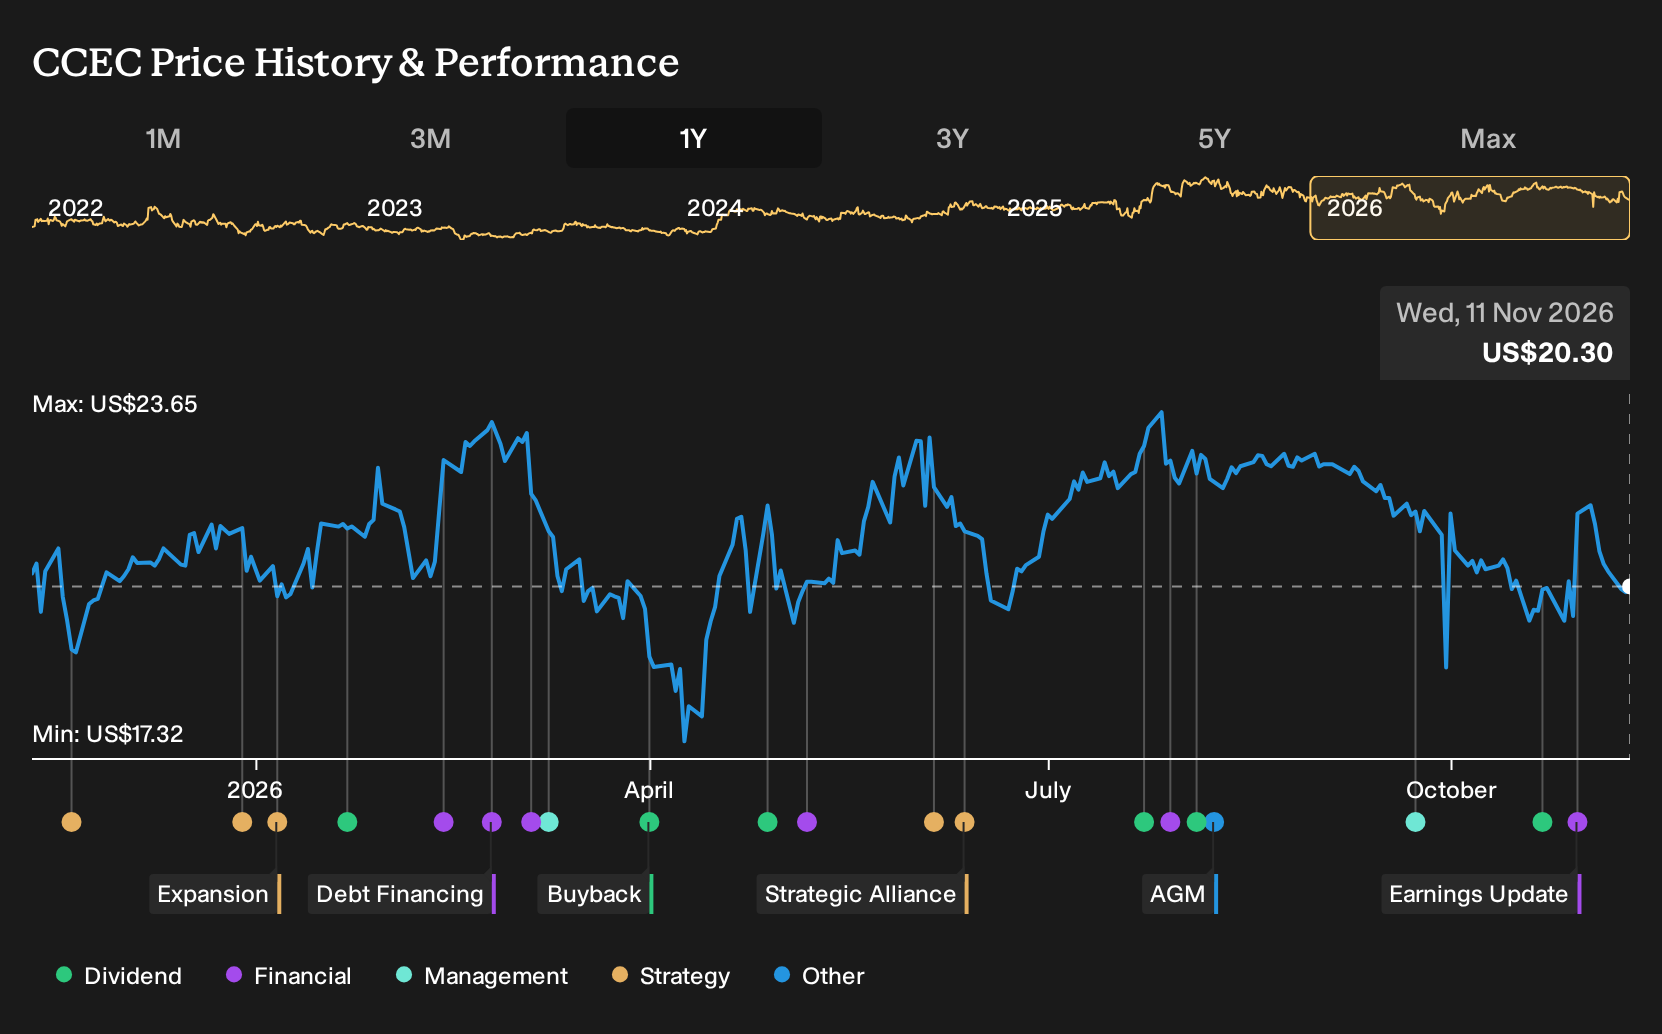
Uncover why Capital Clean Energy Carriers' fair value indicates a 27% potential upside to its current price, suggesting a discount that could close sooner than you might expect.
Exploring Other Perspectives
One bullish twist on Capital Clean Energy Carriers focuses on how quickly earnings could scale if charter coverage deepens. The most optimistic analysts were penciling in about US$905.0 million of revenue and US$274.0 million of earnings by 2029 before this latest quarter. Use this fresh earnings news as your cue to compare that upbeat script with more cautious views.
Explore 2 other Capital Clean Energy Carriers fair value estimates, including one that suggests as much as 54% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Capital Clean Energy Carriers research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Clean Energy Carriers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Clean Energy Carriers' overall financial health at a glance.
Looking for more investment ideas beyond Capital Clean Energy Carriers?
If this update on Capital Clean Energy Carriers has sharpened your thinking, use it as a springboard to broaden your watchlist. The Simply Wall St Screener lets you quickly filter for other businesses that match the risk, quality and income profile you want, so you can compare Capital Clean Energy Carriers against a wider field rather than viewing it in isolation.
- For investors who care most about balance sheet strength and staying power, scan a curated list of solid balance sheet and fundamentals (24 results) that share similar financial resilience traits.
- If you are hunting for opportunities where quality and price may be out of sync, review a focused 32 high quality undervalued stocks that might offer more attractive entry points.
- Income focused readers who want cash flow today as well as potential capital gains can check a targeted 6 dividend fortresses built around higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com