


Fukui Bank (TSE:8362) raised its earnings guidance for the fiscal year ending March 2027, citing stronger than expected net interest income associated with rising policy rates and its regional Marugoto Support customer initiatives.
At a share price of ¥6,850, Fukui Bank has surged this year, with a year to date share price return of 162.25% and a one year total shareholder return of 215.49%. However, the recent 30 day share price move, down 9.39%, hints that momentum has cooled after a strong run into this guidance upgrade.
Capitalize on the earnings momentum story around Fukui Bank by reviewing a curated 24 high quality undervalued stocks that combines strong cash generation with balance sheet strength.After a rapid rerating followed by a cooling 30 day pullback, Fukui Bank now sits at a crossroads. Investors may now be asking whether the current price still offers a favourable trade off between risk and reward as attention turns to valuation.
Price-to-Earnings of 14.2x: Is it justified for Fukui Bank?
On a P/E of 14.2x against a last close of ¥6,850, Fukui Bank trades at a premium to peers and the broader JP Banks industry.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a regional lender like Fukui Bank, that figure often reflects how durable investors think its net interest income and fee streams are, given its focus on comprehensive financial services in Japan.
Here, the stock is described as expensive both versus a peer average P/E of 13.3x and the JP Banks industry average of 13.4x. That indicates the market is paying more relative to sector norms, which may reflect strong conviction in recent profit growth or confidence that current earnings quality can be maintained, even though there is insufficient data on how revenue and earnings might evolve versus the wider JP market.
Against its own history and sector context, the premium looks meaningful. Earnings have grown 89.9% over the past year, compared with 28% per year over five years and 41.5% for the Banks industry, which can help explain why investors are accepting a higher multiple. Even so, the valuation description still points to Fukui Bank being more expensive than both direct peers and the domestic banking group.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 14.2x (OVERVALUED)
Still, the story around Fukui Bank can change quickly if policy rates reverse course or if regional credit quality pressures its net interest income and capital buffers.
Find out about the key risks to this Fukui Bank narrative.
Another View on Fukui Bank's Valuation
The earlier P/E check paints Fukui Bank as expensive, yet the SWS DCF model tells a slightly different story. On this view, the share price of ¥6,850 sits above an estimated future cash flow value of ¥4,299.3, which frames the stock as overvalued rather than cheap on cash generation.
That gap implies less room for error if earnings or interest margins soften from here, since a lot of optimism is already reflected in the quote. The question for you is simple: which signal do you trust more, earnings multiples or long term cash flow value?
Look into how the SWS DCF model arrives at its fair value.
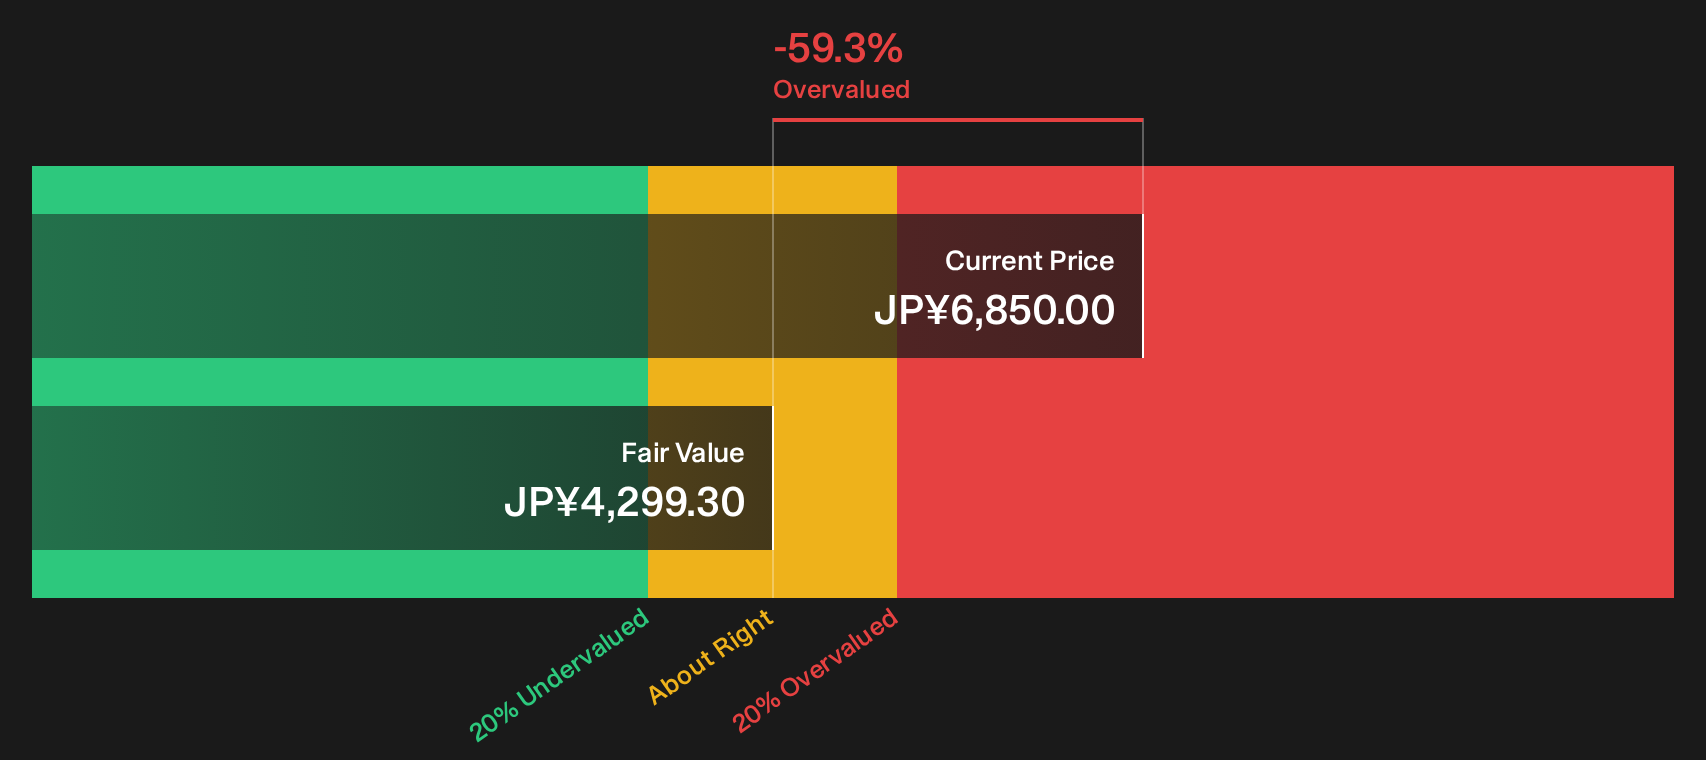
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fukui Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 24 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether this upbeat earnings story for Fukui Bank really balances the upside and the risks? Act now by reviewing the two sides of the ledger with our 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Fukui Bank?
If Fukui Bank has sharpened your focus on pricing, cash flow and balance sheet strength, then broadening your watchlist can help you spot opportunities you might otherwise miss.
- Target resilient cash generators by scanning a curated 24 high quality undervalued stocks that pairs strong earnings with disciplined capital structures.
- Strengthen your income focus by reviewing a hand picked 29 dividend fortresses that emphasizes higher yields supported by underlying fundamentals.
- Stay a step ahead by tracking a forward looking 19 resilient stocks with low risk scores built around companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com